1. Key takeaways from the earnings fortnight
Between Oct 23 and Nov 2, 2026, the Q3 earnings week (Oct 28–29) put hard numbers behind the AI build-out. Five conclusions explain the window; the chapters named in brackets carry the detail.

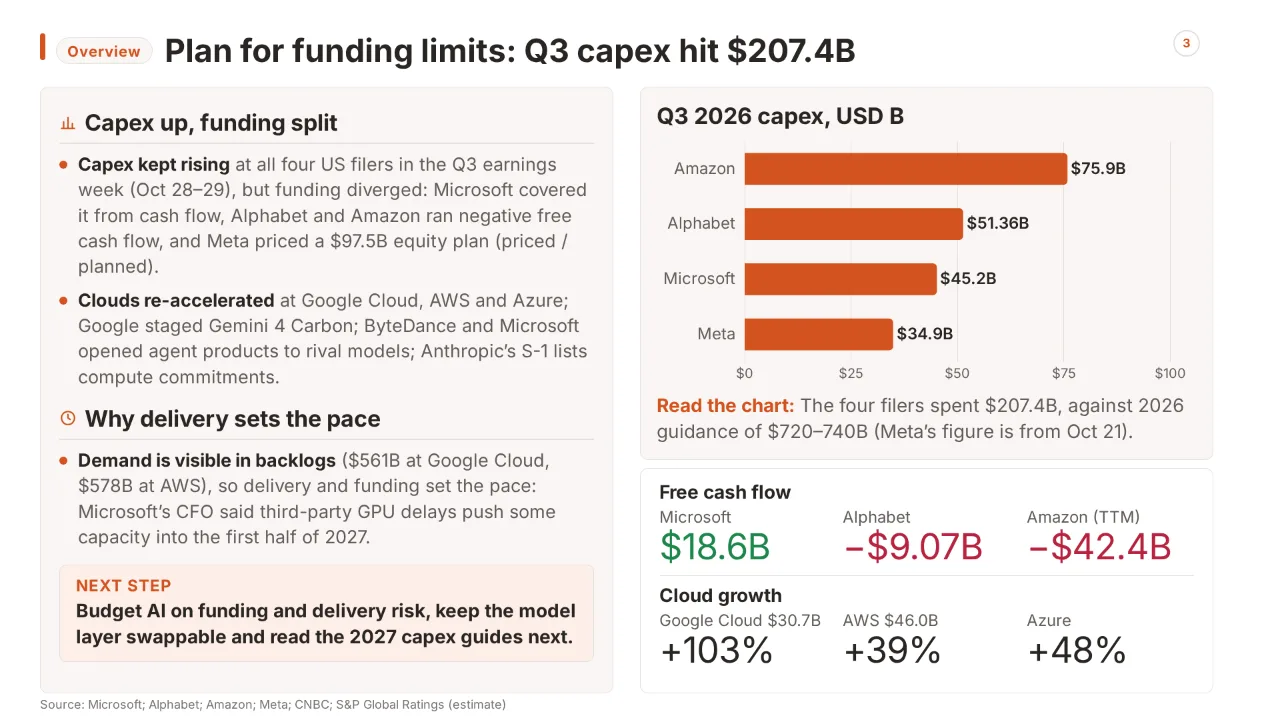
1. Capex is still rising, but the money comes from different places. The four US filers spent $207.4B in the quarter by our sum (45.2 + 51.36 + 75.9 + 34.9; Meta's figure is from Oct 21), against 2026 guidance of $720–740B. Only Microsoft covered it from cash flow (free cash flow $18.6B); Alphabet's was −$9.07B and Amazon's trailing-twelve-month figure −$42.4B. Meta priced a $37.5B equity raise inside a plan of up to $97.5B, and S&P (estimate) moved its outlook to negative. [Chapters 2, 3, 4, 5, 8]
2. Cloud growth re-accelerated at all three clouds. Google Cloud revenue doubled to $30.7B (+103%) with backlog of $561B, AWS grew 39% to $46.0B with a $578B backlog, and Azure grew 48%. Microsoft's capex still came in below plan because third-party capacity arrived late, so supply, not demand, was the limit. [Chapters 2, 3, 5]
3. Google took the model lead, but only in a staged release. Gemini 4 Carbon scores 59 on the Artificial Analysis Intelligence Index v5, one point ahead of Claude Opus 5.5 (58) and two ahead of GPT-6 Astra (57), at $7.76 per task against Opus's $10.04. Access is limited to cyber defenders and Fairwind partners with no developer date, and its cyber scores are vendor-reported. Genie 4 (Oct 27) is a research preview for trusted testers. [Chapters 3, 7]
4. Agent products are opening to rival models. ByteDance's Doubao Work opened Kimi 3.1 Pro, GLM-5.3 and DeepSeek V4.1 Flash to Team and Enterprise customers on Oct 29, following Tencent's WorkBuddy. Microsoft sells GPT-6.1 Sol and Claude Sonnet 5.5 in Copilot beside its own MAI Code 1.1 Flash, an experimental preview, and Amazon's Bedrock Managed Agents (public preview) are powered by OpenAI. [Chapters 2, 6, 7]
5. The compute-contract web got denser, and suppliers are also financiers. Anthropic's S-1 (Oct 26) lists at least $114.5B with Google, $110B with Amazon and $44.9B with Microsoft, plus $161.2B of Broadcom leases, $430.6B of firm commitments by our sum. Nvidia said on Oct 27 it will invest $3B in Meta's offering, about 3% of the $97.5B ceiling, with no price or stake disclosed. Delivery is the weak link: Microsoft's CFO said third-party GPU delays push some capacity into the first half of 2027. [Chapters 4, 8]
1.1 What changed at a glance
| Company | Change | Date (2026) | Status on Nov 3 | Source |
|---|---|---|---|---|
| Microsoft | FY27 Q1: revenue $92.3B, Azure +48%; capex $45.2B incl. finance leases | Oct 28 | Reported | Microsoft; CNBC |
| Alphabet | Q3: Cloud $30.7B (+103%); capex $51.36B; 2026 guide $195–205B kept | Oct 28 | Reported; guidance | Alphabet release; CNBC |
| Gemini 4 Carbon announced; cyber defenders first | Oct 28 | Staged, limited preview | Google blog | |
| Meta | $12.5B preferred and $25.0B Class A priced; ATM up to $60B from Q1 2027 | Oct 26 | Priced; ATM planned | Meta release |
| Meta | S&P outlook negative, AA- affirmed | Oct 30 | In effect | S&P Global Ratings |
| Amazon | Q3: AWS $46.0B (+39%), backlog $578B; cash capex $75.9B | Oct 29 | Reported | Amazon release; Business Insider |
| Apple | Fiscal Q4 revenue $114.5B (+12%), first quarter under CEO Ternus | Nov 2 | Reported | Apple 8-K |
| ByteDance | Doubao Work opens Kimi 3.1 Pro, GLM-5.3, DeepSeek V4.1 Flash | Oct 29 | Announced (media) | BigGo |
| Anthropic | S-1 filed with compute commitments | Oct 26 | Filed | GeekWire |
2. Microsoft — fiscal Q1 results, capex and buyouts
Chapter 1 summarised the earnings fortnight; Microsoft's part is a quarter in which Azure beat, capex undershot plan, and a buyout offer to a quarter of the workforce arrived two days earlier.
2.1 Dated timeline
| Date (2026) | Event | Status on Nov 3 | Source |
|---|---|---|---|
| Sep 30 (context) | GPT-6.1 Sol and Claude Sonnet 5.5 rollout starts in Copilot Cowork and Copilot Studio | Rolling out | Dellenny |
| Oct 26 | Voluntary Exit Offer, about 60,000 eligible | In effect; decision window to early December (reported) | Reuters; Fortune |
| Oct 27 | MAI Image 2.7 preview; MAI Cyber 1.1 Flash; Excel update adds the two partner models | Preview / restricted / rolling out | Microsoft AI; Tech-insider |
| Oct 28 | FY27 Q1 results and call | Reported | Microsoft |
| Oct 28 | Copilot Fusion routes between local MAI Code 1.1 Flash and cloud models | Experimental preview, opt-in | GitHub |
2.2 Results and capex logic
Microsoft reported its first quarter of FY27 (ended Sep 30) on Oct 28, the first under two segments, Agents and Infra and Devices and Consumer. Figures below are the company release (reported).
| Metric | Q1 FY27 | Y/Y | Source |
|---|---|---|---|
| Revenue | $92.3B | +19% | Microsoft |
| Operating income | $45.9B | +21% | Microsoft |
| Microsoft Cloud revenue | $63.9B | +30% | Microsoft |
| Azure revenue | n/a in release | +48% | Microsoft |
| Agents and Infra | $76.8B | +25% | Microsoft |
| Devices and Consumer | $15.5B | -3% | Microsoft |
| Commercial RPO | $677B | +73% | Microsoft |
Azure. The release gives growth only. According to LicenseQ, Azure was $33.2B against $22.4B a year earlier, ahead of the roughly 45% Microsoft guided. StreetAccount expected $32.32B: 33.2 − 32.32 = $0.88B (+2.7%).
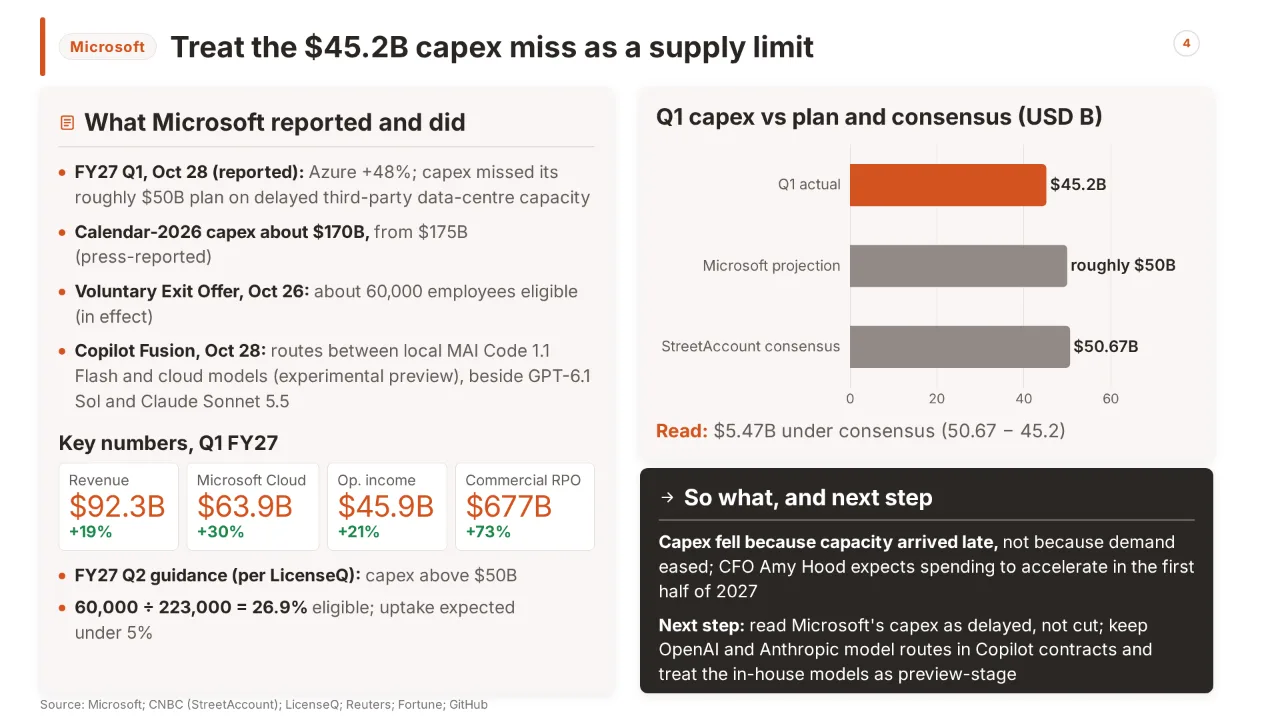
Capex. Capital expenditure including finance leases was $45.2B, up about 30%, according to LicenseQ and Fortune; the release excerpt omits it and no 10-Q is in our material, so no cash-only figure exists here. StreetAccount's consensus was $50.67B: 50.67 − 45.2 = $5.47B (10.8%) lower. Tech-insider (citing TechCrunch and Fortune) says Microsoft had itself projected about $50B and attributes the gap to delayed third-party data-centre capacity; CNBC quotes Hood on the same delays. Calendar-2026 capex is now about $170B, down from $175B stated by Reuters on Oct 26, before results; whether that figure includes leases is not stated. Capex equalled 45.2 ÷ 92.3 = 49% of revenue; free cash flow was $18.6B, down 27% (about $25.5B a year earlier, our arithmetic). Call guidance for FY27 Q2 (guidance, per LicenseQ): revenue $96B–$97.1B, Azure +49% to +50% constant currency, capex above $50B; a recap video says 49%, and we follow LicenseQ's range.
RPO. The release's $677B is +73%, so a year earlier it was about 677 ÷ 1.73 = $391B (our arithmetic). LicenseQ and Yahoo Finance cite $678B; that is the June-quarter figure, not a conflict, so RPO was flat sequentially, and commercial bookings fell 12% against large prior-year Azure commitments. LicenseQ also notes no new Microsoft 365 Copilot seat count (last disclosed: 30 million at end of FY26) and paid commercial seat growth of 5%.
Azure accelerated to +48% while capex came in at $45.2B, below a roughly $50B plan: the constraint was supply, not restraint.
2.3 Workforce and capital efficiency
On Oct 26, Chief People Officer Amy Coleman's memo introduced the Voluntary Exit Offer (VEO). Microsoft says it is time-limited and voluntary, open to employees in participating teams in Canada, India, the UK and the US at level 70 and below. About 60,000 are eligible: 60,000 ÷ 223,000 employees (June 30, 2026) = 26.9%.
An anonymous source told Reuters (reported) that eligible units include AI experiences, Copilot, finance, HR, Xbox and Windows + Devices, while marketing, commercial and security are excluded. A Microsoft spokesperson said some data-centre, sales and marketing staff are not eligible.
Microsoft expects under 5% uptake, below 5% × 60,000 = 3,000 people; Hood told staff on Oct 28 to expect "very few" takers (via Business Insider). The spring voluntary retirement program drew about 30% of roughly 8,700 eligible, about 2,600. Employees reportedly decide by early December and leave on Dec 31 (CNBC, via Fortune; upcoming).
The capital-efficiency logic is in Fortune's reading of the annual report: FY26 property-and-equipment spending was $115.9B against $64.6B (115.9 ÷ 64.6 = +79%) while headcount fell about 5,000. Our reading: even 3,000 exits is 1.3% of 223,000, so the offer changes workforce mix, not funding. The material has no cost or savings figure.
2.4 Models inside Copilot
GitHub's changelog (Oct 28) is the primary source. Intelligent local-model routing in GitHub Copilot Fusion ships as an opt-in experimental preview in Copilot CLI, the Copilot app and VS Code. On supported Windows devices, MAI Code 1.1 Flash downloads through the Windows ML provider, and "Standard" mode lets Copilot choose local or cloud models. Developers can also run it, or Qwen3.8 Flash Next, through a local OpenAI-compatible server; CLI routing then works on Windows, macOS and Linux, while the app routes only managed Windows ML models. Routing decisions still run in the cloud, and local models may have different safety protections. No Microsoft AI page for MAI Code 1.1 Flash is in our material, so size, benchmarks and licence are unknown.
| Model | Maker | Where | Status | Source |
|---|---|---|---|---|
| MAI Code 1.1 Flash | Microsoft (in-house) | Copilot Fusion, local | Experimental preview, Oct 28 | GitHub |
| MAI Image 2.7 | Microsoft (in-house) | Microsoft AI | Preview; No. 3 Arena Edit (vendor-reported) | Microsoft AI |
| MAI Cyber 1.1 Flash | Microsoft (in-house) | MDASH, verified defenders only | 18% less per scan on internal suite; interest registration | Microsoft AI |
| GPT-6.1 Sol | OpenAI | Cowork, Studio, Word, Excel, PowerPoint, Chat | Phased; since Sep 30 (context) | Dellenny |
| Claude Sonnet 5.5 | Anthropic | Same surfaces | Phased; needs Anthropic subprocessor | Dellenny |
According to Dellenny, Cowork and Copilot Studio use usage-based billing, the Office apps fall under the Microsoft 365 Copilot licence, and users at a limit can switch to Auto. Tech-insider dates an Excel update with both models to Oct 27 and says switching needs a commercial Copilot subscription or Microsoft 365 Premium; neither page is a Microsoft post, so treat dates as reported.
Judgement: Microsoft puts small in-house models on the device and sells OpenAI and Anthropic frontier models by choice; the in-house tier is still preview-stage.
3. Alphabet and Google — Q3 results, Genie 4 and Gemini 4 Carbon
Chapter 2 covered Microsoft's quarter; Alphabet reported the same day, Oct 28, 2026, pairing a cloud-led quarter with a cash-flow shock and a new frontier model.
3.1 Q3 numbers from Alphabet's own release
The table uses one source, Alphabet's Q3 release (8-K Exhibit 99.1, Oct 28, quarter ended Sep 30, 2026), in $ millions. Status: reported.
| Line | Q3 2025 | Q3 2026 | Change |
|---|---|---|---|
| Revenue | 102,346 | 127,577 | +25% |
| Google Search & other | 56,567 | 63,350 | +12% |
| Google Cloud revenue | 15,157 | 30,709 | +103% |
| Google Cloud operating income | 3,594 | 11,121 | +209% |
| Operating income (margin) | 31,228 (30.5%) | 40,576 (31.8%) | +30% |
| Net income to common | 34,979 | 26,170 | -25% |
| Diluted EPS ($) | 2.87 | 2.12 | -26% |
Cloud's operating margin was 11,121 ÷ 30,709 = 36.2%, up from 23.7% (our arithmetic); TPU system sales were "a meaningful contributor". Net income is $26.5B before $298M of preferred dividends and $26.2B to common holders: 26,468 - 298 = 26,170. We follow the release's $26.2B. Other income swung to -$8,221M, mainly an unrealized loss on the SpaceX stake (according to MarketBeat and NextGComm). Search growth slowed from 19% (Q1) and 17% (Q2) to 12%; Philipp Schindler cited foreign exchange and lower AI Mode monetization.
The capex series below comes from Alphabet's Q3 slides ($ millions, reported).
| Quarter | Capex | Y/Y | Free cash flow |
|---|---|---|---|
| Q3 2025 | 23,953 | +83% | 24,461 |
| Q4 2025 | 27,851 | +95% | 24,551 |
| Q1 2026 | 35,674 | +107% | 10,116 |
| Q2 2026 | 44,924 | +100% | (5,855) |
| Q3 2026 | 51,355 | +114% | (9,065) |
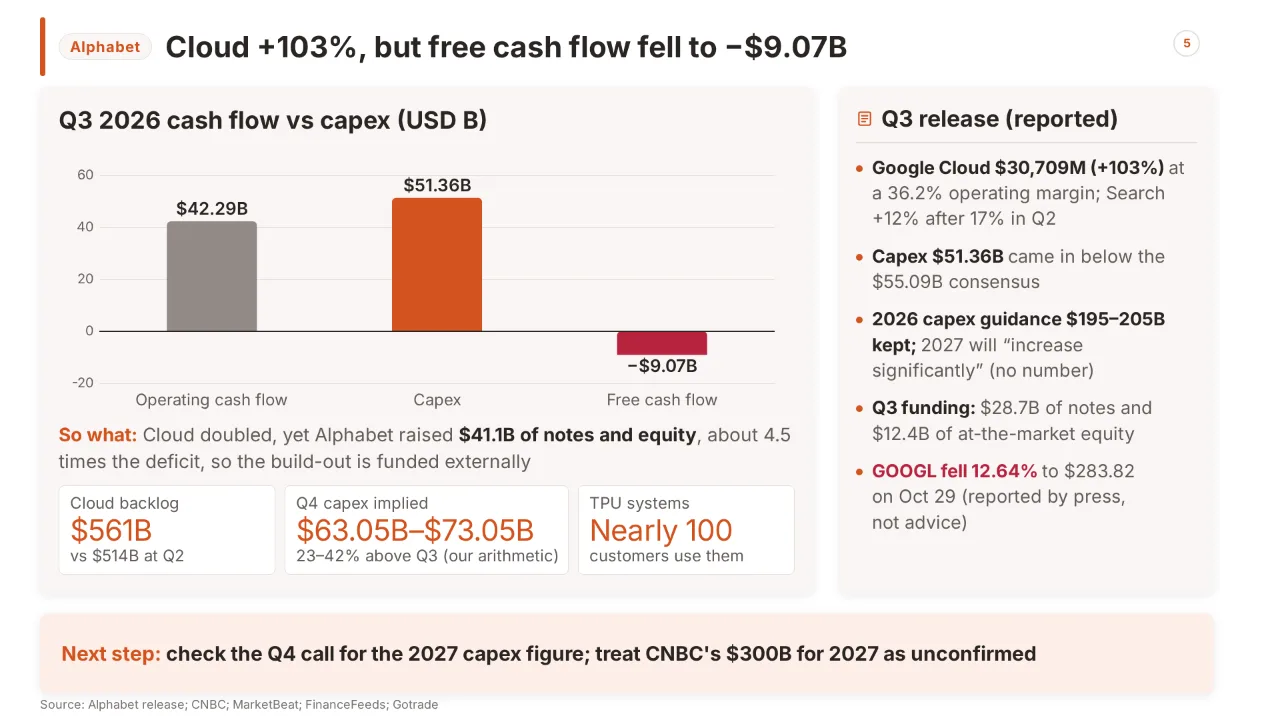
Cloud revenue doubled to $30.7B, but capex of $51.4B outran operating cash flow of $42.3B and pushed free cash flow to -$9.1B.
3.2 Cash flow, capacity, TPUs and margin: what the call said
Versus expectations. CNBC, citing LSEG and FactSet consensus, reports Cloud revenue of $30.7B against $28.7B expected, Search of $63.35B against $64.96B, operating income of $40.58B against $43.19B, capex of $51.36B against $55.09B and free cash flow of -$9.07B against -$2.70B. Capex fell $3.73B (6.8%) short of consensus, so the miss was in cash conversion and Search, not in spending.
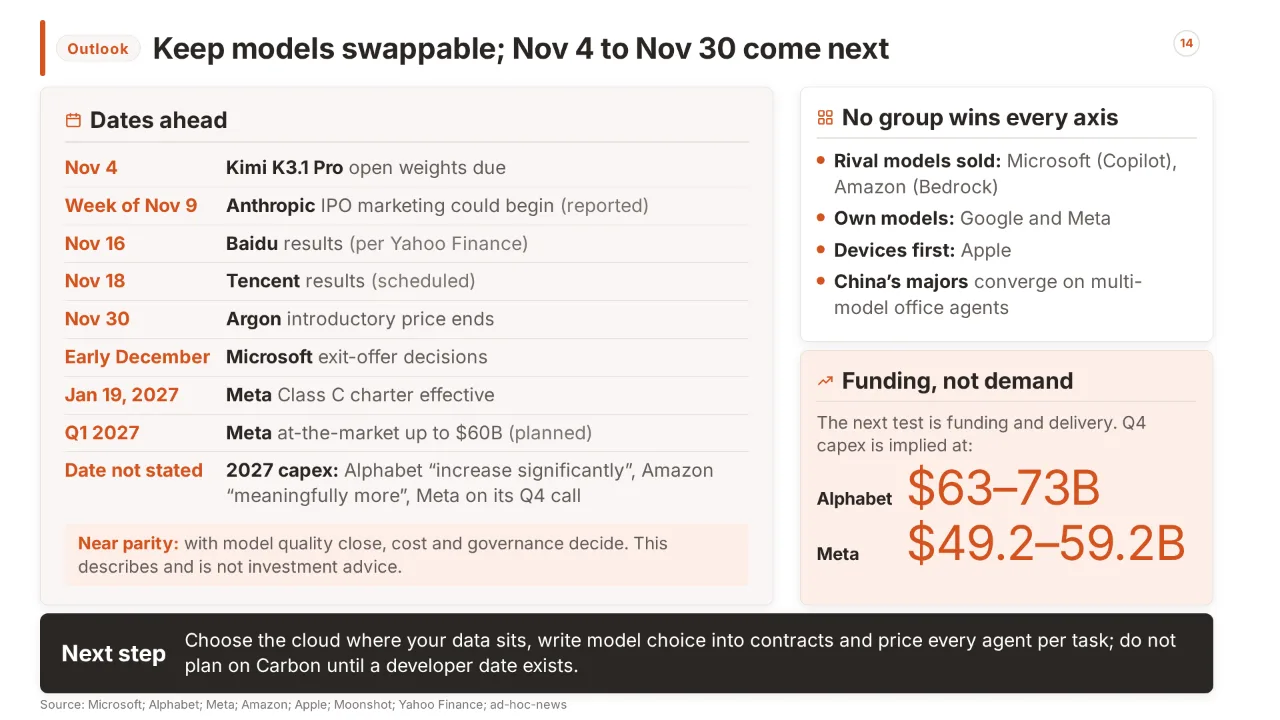
Capex arithmetic. Nine-month capex is 35,674 + 44,924 + 51,355 = $131.95B. Against the maintained 2026 guidance of $195-205B (company outlook), Q4 would be 195 - 131.95 = $63.05B to 205 - 131.95 = $73.05B, or 23-42% above Q3 (our arithmetic). For 2027, CFO Anat Ashkenazi said capex will "increase significantly", with details on the Q4 call. CNBC adds that annual capex is expected to exceed $300B in 2027, but it gives no source and Alphabet has given no figure, so we treat it as unconfirmed.
Cash and funding. Free cash flow is operating cash flow of 42,290 minus capex of 51,355 = -9,065; trailing-twelve-month FCF is $19.7B against $73.6B a year earlier (-73%). FinanceFeeds adds a $5.2B EU fine payment. Long-term debt is $125.1B against $21.6B a year earlier. Q3 funding included $28.7B of notes and $12.4B from the at-the-market program ($4.3B + $8.1B); Chapter 8 covers financing.
Backlog and TPUs. Cloud backlog was $561B (NextGComm, citing the 10-Q: $560.8B), against $514B at Q2, a rise of about $47B. Management expects to recognize just over 55% within 24 months: 0.55 × 560.8 ≈ $308B, or about $38.5B a quarter against Q3's $30.7B (our arithmetic). Nearly 100 customers use TPU systems, with Anthropic, Apple, Oracle and Crux AI named. Systems require inventory before revenue is recognized: inventory rose from $2.4B to $13.3B this year (according to NextGComm), and more TPU revenue is expected in 2027. TechTimes says TPU systems carry higher margins, but Alphabet said on its Q2 call (Jul 22, context) that it does not disclose product margins; we follow the company.
Third-party capacity and margin. Ashkenazi said third-party compute coming online in Q4 will create near-term Cloud margin headwinds, alongside higher depreciation and data-center costs. No margin figure was given; 36.2% is the baseline.
Reaction (reported, not advice). GOOGL closed Oct 28 at $324.89, traded at $292.50 after hours (-9.97%), and fell 12.64% to $283.82 on Oct 29; CNN Business called it the worst day on record (via Gotrade).
3.3 Genie 4 and Gemini 4 Carbon: what shipped, and to whom
Genie 4 (Oct 27, research preview). Google DeepMind announced a world model that generates interactive, real-time simulations with native audio, built on Gemini Omni and other Gemini models. It is a research preview for trusted testers; consumer and developer release follows, starting with Google AI Ultra subscribers in Project Genie and early-access Gemini API and AI Studio partners. There is a waitlist and no date or price. Pichai called it a building block for training robots and agents.
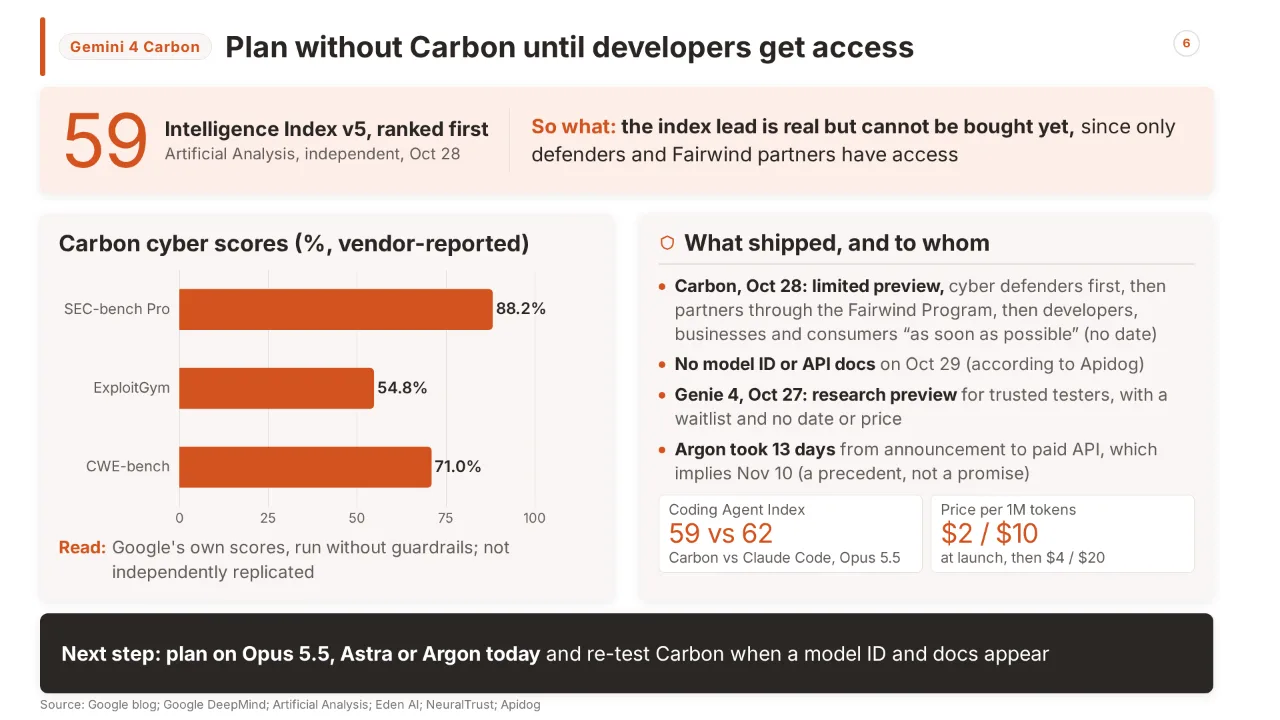
Gemini 4 Carbon (Oct 28, staged access). Google announced Carbon as its strongest model, focused on cybersecurity and long-horizon work. Access starts "this week" with a subset of cyber defenders, then trusted partners through the Fairwind Program, while Google takes part in the U.S. government's voluntary pre-release testing. Developers, businesses and consumers get it "as soon as possible", with no date. As of Oct 29 no model ID or API docs existed (according to Apidog). Status: limited preview, not GA. Argon took 13 days from announcement to paid API (Sep 30 to Oct 13, context); the same gap implies Nov 10, a precedent, not a promise. Launch price: $2 input and $10 output per million tokens, cached input 95% off, introductory; standard price is $4 / $20.
Vendor-reported and independent claims differ in kind. Google's cyber scores, run without guardrails, come from its own launch table (as listed by Eden AI):
| Benchmark (vendor-reported) | Carbon | Argon | GPT-6 Astra | Opus 5.5 |
|---|---|---|---|---|
| SEC-bench Pro | 88.2% | 83.4% | 85.4% | not reported |
| ExploitGym | 54.8% | 42.0% | 42.4% | 34.5% |
| CWE-bench | 71.0% | 68.0% | 68.0% | 67.0% |
These have not been independently replicated (according to NeuralTrust). The independent source is Artificial Analysis, Oct 28: Carbon scores 59 on Intelligence Index v5, ranked #1, and leads 4 of 9 evaluations, but its Coding Agent Index score of 59 trails Claude Code with Opus 5.5 (62). Its cost per task is $7.76, 23% below Opus 5.5's $10.04 (7.76 ÷ 10.04 = 0.77). Index v5 launched Oct 27, so earlier scores are not comparable. Chapter 7 compares models.
4. Meta — equity plan, Nvidia and the S&P outlook
Chapter 3 covered Alphabet's results and models; Meta's news in the window is about paying for the build-out, in three steps: an equity plan (Oct 26), Nvidia's investment (Oct 27) and a rating-agency warning (Oct 30).
4.1 The financing structure
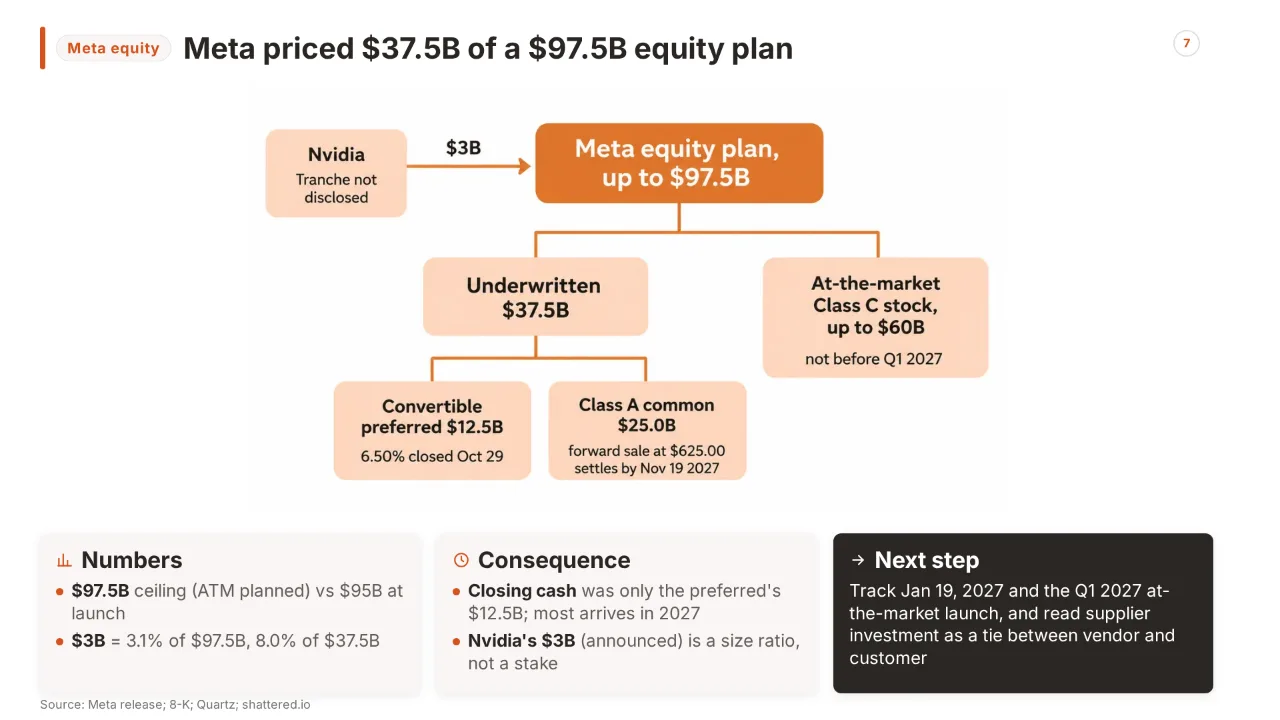
Meta's Oct 26 launch release described about $35B of underwritten offerings ($22.5B Class A common plus $12.5B preferred depositary shares) and a roughly $60B at-the-market (ATM) program, or $95B. Pricing the same day upsized the common tranche to $25.0B. Arithmetic: 25.0 + 12.5 = $37.5B underwritten; 37.5 + 60 = $97.5B ceiling. Press figures of $95B (WSJ via Quartz) are the pre-upsizing number; we follow the release.
| Instrument | Size | Price and terms | Status (vs Nov 3) | Source |
|---|---|---|---|---|
| 6.50% Series A mandatory convertible preferred ("METAM") | 250M depositary shares = $12.5B | $50 each; converts Aug 15, 2029 into 1.3620-1.6000 Class A shares per $1,000 preferred share | Priced Oct 26; closed Oct 29 | Meta release; 8-K |
| Class A common, forward sale | $25.0B (was $22.5B); 40M shares | $625.00 per share; forward price about $622.92; settles by Nov 19, 2027 | Priced Oct 26; closing expected Oct 29 | Meta releases |
| Over-allotment options | 37.5M depositary shares; $3.75B common | 30 days | Exercise not stated | Meta release |
| ATM, new Class C stock | up to $60B | Not before Q1 2027 | Planned; no agreement at Oct 26 | Meta releases |
Two mechanics matter. First, cash timing: Meta expects no initial proceeds from the common tranche, so the cash at the Oct 29 closing was the preferred's $12.5B; the $25.0B arrives at forward settlement (40M x $622.92 = about $24.9B, before agreement adjustments). S&P nonetheless counts $37.5B as raised. Second, Class C: the charter amendment was filed Oct 21, effective Jan 19, 2027, with a one-for-one Class C dividend on Class A and B shares contingent on it. S&P writes the ATM as "beginning in January 2027"; we follow Meta's "first quarter of 2027".

The preferred pays 6.50% on $12.5B, so $812.5M a year ($65 per $1,000 share x 12.5M shares), from Feb 15, 2027. Meta lists its funding mix as operating cash flow, investment-grade debt, partnerships and equity, with $97B operating cash flow in nine months, about $82B cash and Aa3/AA- ratings.
4.2 The Nvidia deal
On Oct 27 Nvidia and Meta said Nvidia will invest $3B in Meta's equity offering (company statement, via Quartz). Meta says it will scale up Nvidia hardware for next-generation agents: Vera Rubin, Vera CPUs, Spectrum-X Ethernet and BlueField-4. The pair will deepen work on the Muse models to improve inference and training performance and total cost of ownership, and will only "consider" OpenShell, the OpenShell Reference Architecture and Sentry (agent monitoring). Status: announced; no volume, schedule or Muse benchmark is given.
According to shattered.io, the companies did not disclose the price, share count, ownership share or closing date, and EconoTimes noted that Meta's Oct 26 paperwork did not name the figure. Axios (via Quartz) says it goes toward the offering Meta announced Monday. Arithmetic: 3 / 97.5 = 3.1% of the ceiling, 3 / 37.5 = 8.0% of the underwritten total; which tranche carries it is unknown. It is two separately stated moves, an investment and a procurement plan; no contract between them is described.
4.3 S&P: outlook negative, AA- affirmed
On Oct 30 (17:03 EDT) S&P Global Ratings revised its Meta outlook to negative from stable and affirmed AA-. All numbers below are S&P estimates from that one report.
| S&P forecast | 2026 | 2027 | 2028 |
|---|---|---|---|
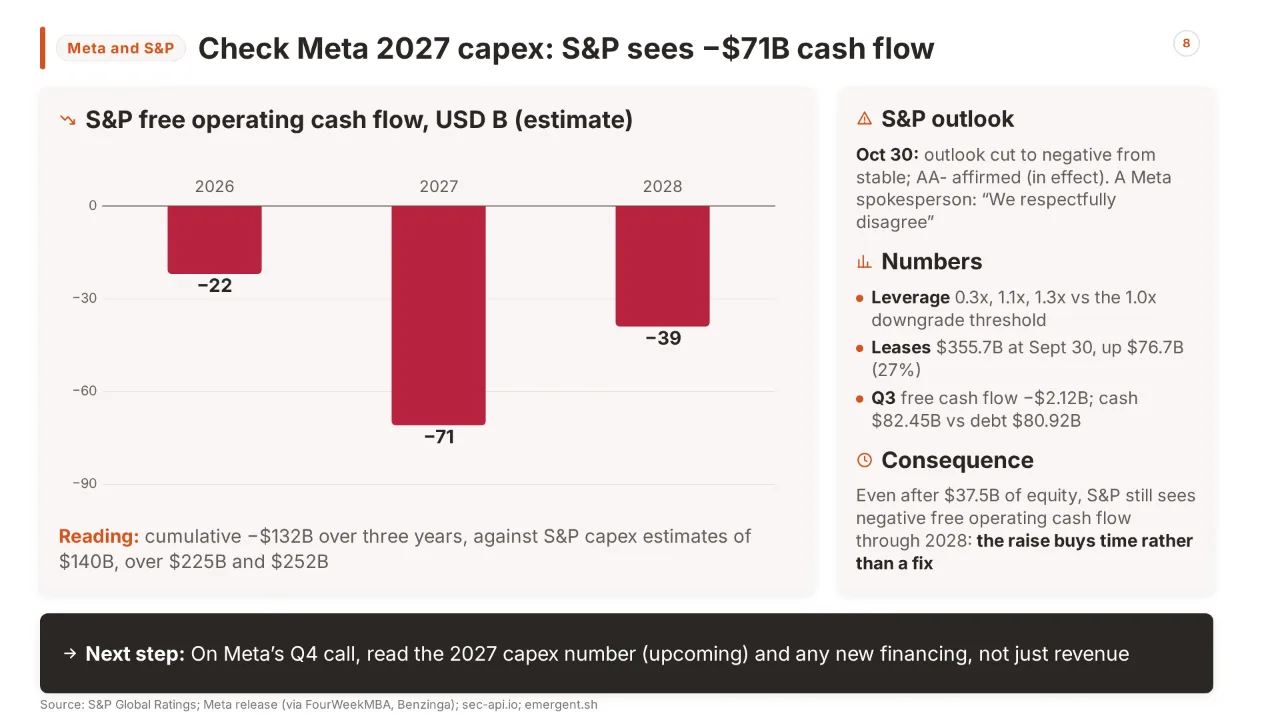
| Capex | $140B | over $225B (before: $163B) | $252B (before: $178B) |
| Free operating cash flow | -$22B | -$71B | -$39B (before: positive) |
| Adjusted leverage, ex-ATM | 0.3x (before: 0.4x) | 1.1x (before: 0.7x) | 1.3x (before: 0.8x) |
Capex rises by at least 225 - 163 = $62B (+38%) in 2027 and 252 - 178 = $74B (+42%) in 2028. Cumulative free operating cash flow is -22 - 71 - 39 = -$132B. Leverage was about 0.1x in 2025; 1.0x is S&P's downgrade threshold. With the $60B ATM in the 2027 forecast it would be 0.7x in 2027 and 1.1x in 2028.
S&P's reasoning has three parts. Leases drive it: future lease obligations were $355.7B at Sept 30 against about $279B in the June quarter, including the El Paso project, a rise of $76.7B or 27%. Monetization is "more limited than that of its peers", several of which lease compute to third parties. And 2027 capex is undisclosed, so S&P is "less certain" spending will be curtailed. It treats the equity as credit positive, because it can cover the 2027 deficit instead of debt, but assumes debt alone covers 2028 and excludes future issuance. Per Investing.com, a downgrade could follow if leverage stays above 1.0x and free operating cash flow is negative beyond 2028. A Meta spokesperson, quoted by emergent.sh, said "We respectfully disagree".
S&P's estimate is that Meta's equity raise buys time, not a fix: even after $37.5B of equity, it sees negative free operating cash flow through 2028 and leverage above its 1.0x line from 2027.
4.4 Q3 context and the cash-flow arithmetic
Meta's Oct 21 Q3 results are context, dated before the window. Free cash flow (Meta definition) was -$2.12B: operating cash flow $32.786B - equipment purchases $33.942B - finance-lease principal $0.964B (Meta release via FourWeekMBA). Capex including finance-lease principal was $34.91B. Nine-month capex was $85.824B and free cash flow +$11.049B; their sum, about $96.9B, matches the "$97B" operating cash flow in Meta's Oct 26 release.
Guidance for 2026 capex is $135-145B, raised from $130-145B. Subtracting the nine-month figure implies fourth-quarter capex of $49.2-59.2B, or 41-70% above Q3; S&P's $140B implies 140 - 85.8 = about $54.2B. Cash was $82.45B, and long-term debt $80.92B against $28.83B a year earlier.
Commitments conflict. According to sec-api.io, off-balance-sheet commitments were $454.5B at Sept 30 (leases not yet commenced $355.7B) against $131.1B at year-end 2025; emergent.sh says "more than $800 billion". We follow the 10-Q-based $454.5B. On Oct 21 CFO Susan Li said 2027 plans were still being developed; Meta's 2027 capex number is upcoming, expected on the Q4 call. The four-company capex tally is Chapter 8's.
5. Amazon and Apple — AWS acceleration and Apple's first Ternus quarter
Chapter 4 showed Meta paying for its build-out with new equity; Amazon, which reported on Oct 29, paid for the same race with cash flow, while Apple used the window to report a record quarter built on devices rather than data centers.
5.1 AWS numbers from the Q3 release
Amazon's Q3 release (quarter ended Sept 30, issued Oct 29, 2026, status: reported) is the backbone here; every row below comes from it.
| Amazon Q3 2026 (release) | Q3 2026 | Year-ago / change |
|---|---|---|
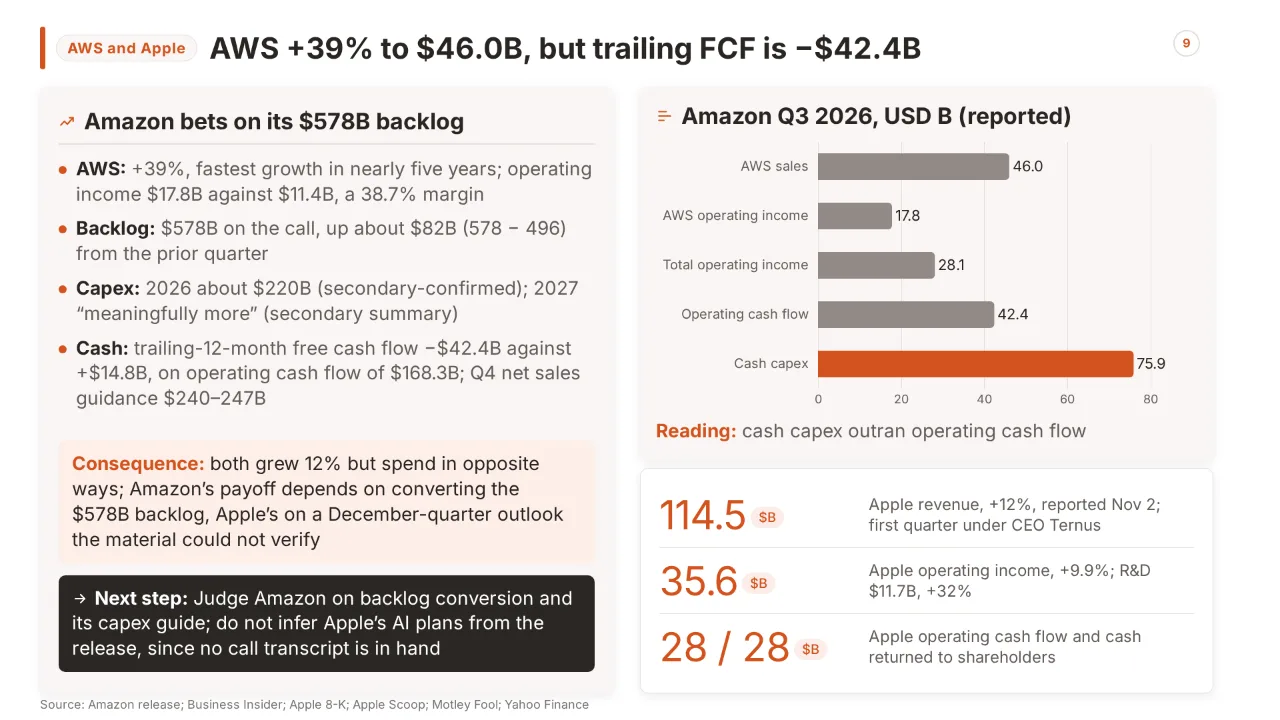
| AWS sales | $46.0B, +39% (39.3%) | fastest growth in nearly five years |
| AWS annualized run rate | $184B | n/a |
| AWS operating income | $17.8B | $11.4B (+56%) |
| Total net sales | $201.9B | $180.2B (+12%) |
| Total operating income | $28.1B (margin 13.9%) | $17.4B (+61%) |
| Net income | $20.7B ($1.89/share) | $21.2B ($1.95) |
| Trailing-12-month operating cash flow | $168.3B | $130.7B (+29%) |
| Trailing-12-month free cash flow | -$42.4B | +$14.8B |
Our arithmetic: 17.8 ÷ 11.4 − 1 = 56%; AWS margin 17.8 ÷ 46.0 = 38.7%; year-ago AWS sales ≈ 46.0 ÷ 1.393 = $33.0B, so year-ago margin ≈ 11.4 ÷ 33.0 = 34.5% (derived, not in the release). Net income fell only because Q3 2025 held $9.5B of pre-tax Anthropic investment gains.
On the call, Andy Jassy gave AWS backlog as $578B, "growing triple digits" year over year, and said AWS had accelerated for a sixth straight quarter. The previous quarter's backlog was $496B, according to tastylive (context, pre-window), so the quarter added about $82B (578 − 496). The release also gives projected AWS growth "over 40%" in both 2027 and 2028 (a company projection, not guidance with a number).
Usage figures from the release: Fortune 500 Bedrock spend up nearly 7x and Bedrock token volume nearly 17x year over year; tens of thousands of AgentCore customers, who deployed 2x more agents in Q3 than in the prior three quarters combined; Bedrock Managed Agents (powered by OpenAI) in public preview; Strands harness released, cutting agent task cost 32% versus other harnesses at equal or better accuracy (vendor claim).
AWS is growing 39% on a $46B quarter with a 38.7% margin, and Amazon says the backlog is $578B; the unresolved question is the cash bill, with trailing free cash flow at -$42.4B.
5.2 Capex, chips and the cash bill
Capex. Amazon's 2026 cash capex is about $220B, per Amazon via secondary outlets; tastylive says it was raised to $220B in July from $200B, so Q3 held the figure (context). TrendSpider says management signaled "meaningfully more" in 2027; this is a secondary summary of the call and carries no figure. The primary page we hold is truncated before the capex line, so treat $220B as secondary-confirmed.
Quarter actual. Amazon's CFO put Q3 cash capex at $75.9B (Business Insider); the SEC Exhibit 99.1 data block shows operating cash flow of $42.4B and gross property purchases of $77.3B. The $1.36B gap is probably proceeds and incentives, since Amazon's free cash flow is net of them; we follow $75.9B, as Chapter 8 does. Check: 42.4 − 75.9 = -$33.5B quarterly free cash flow on the net basis (our arithmetic), against 42.4 − 77.3 = -$34.8B on gross purchases, which is TrendSpider's -$34.8B; TrendSpider prints $75.9B for capex beside it, so its FCF is on the gross basis. Q3 cash capex alone is 75.9 ÷ 220 = 35% of the full-year figure. Four-filer totals are in Chapter 8.
Chips and AI revenue. Jassy said Amazon is "installing an AI accelerator about every 14 seconds" and that AI margins are improving "well ahead" of core at a similar stage. According to TrendSpider, inference is over half of AWS AI revenue and customers saved $2B+ in Q3 on Trainium and Graviton. Pre-window context from tastylive: AI and custom-chip businesses each passed a $25B annual run rate in Q2, with multi-gigawatt Trainium commitments from Anthropic and OpenAI.
Outlook and reaction. Q4 net sales guidance is $240-247B (midpoint $243.5B) against a $244.5B consensus (Bloomberg, via Yahoo Finance); operating income guidance is $28.5-32B (TrendSpider). Yahoo reports the stock fell more than 9%; Tech-insider, citing TechCrunch, says 7%; Shattered could not confirm a percentage. Treat the move as reported and unreconciled.
5.3 Apple's first Ternus quarter
John Ternus became CEO on Sept 1, 2026, with Tim Cook moving to executive chairman, per Apple Scoop. On Nov 2 Apple reported fiscal Q4 (ended Sept 26; status: reported).
| Apple FQ4 2026 (8-K Ex. 99.1) | Q4 2026 | Q4 2025 | Change |
|---|---|---|---|
| Net sales | $114.5B | $102.5B | +12% |
| Products | $82.9B | $73.7B | +12.5% |
| Services | $31.6B | $28.8B | +9.8% |
| Operating income | $35.6B | $32.4B | +9.9% |
| R&D expense | $11.7B | $8.9B | +32% |
| Diluted EPS | $2.10 | n/a in release | +14% (Apple) |
Percentages are our arithmetic from the statement of operations (for example 114,477 ÷ 102,466 − 1 = 11.7%; 11,730 ÷ 8,866 − 1 = 32.3%). Gross margin was 47.9%, including about 1 point of tariff refunds; EPS includes $0.05 from refunds. Fiscal 2026 revenue was a record $479B (478,834 ÷ 416,161 = +15.1%); operating cash flow was $28B and $28B went back to shareholders; the $0.27 dividend is payable Nov 16.
What Apple said on AI. Only the release is in hand: Ternus called the lineup "ambitious", citing iPhone Duo, iPhone 18 Pro, new home hardware and "the all-new Siri AI". No call transcript is in our material, so Apple's call remarks on Siri, Gemini, China, capex or December-quarter guidance are not verified here.
Analyst reading (not Apple). Apple guided 9-11% growth on July 30, about $111.7-113.7B (102.5 × 1.09 and × 1.11); consensus was near $113.3B and EPS $1.99, per Apple Scoop and MarketBeat. Actual $114.5B beat the top of the range by $0.8B and EPS beat by $0.11. The EPS growth flatters: the year-ago quarter carried a $10.2B Ireland tax charge, according to 9to5Mac via AOL, so operating income (+9.9%) is the cleaner trend. The iPhone Duo went on sale Oct 23 from $1,999 and sold out, with deliveries into January (Motley Fool via AOL, reported); it falls in the December quarter, where consensus is about $153.4B.
5.4 Infrastructure versus devices
| Measure | Amazon (Q3, Sept 30) | Apple (FQ4, Sept 26) |
|---|---|---|
| Revenue growth | +12% | +12% |
| Operating income growth | +61% | +9.9% |
| Operating cash flow, quarter | $42.4B | $28B |
| Investment line | cash capex $75.9B | R&D $11.7B |
Each column is from its own company filing; the last row compares different measures (Apple's capex is not in our material).
Both grew 12%, but they spend in opposite ways. Amazon turned a $75.9B quarter of cash capex into negative trailing free cash flow, betting that a $578B backlog pays it back. Apple spent $11.7B on R&D in the quarter, up 32%, while returning $28B in cash. The Motley Fool describes Apple's approach as selling devices rather than competing in cloud computing, an analyst reading, not an Apple statement. Amazon's payoff depends on backlog converting to revenue; Apple's on a December-quarter outlook we could not verify.
6. China's majors — ByteDance, Alibaba, Tencent, Baidu and Huawei
Chapter 5 set Amazon's infrastructure bet against Apple's devices; in China the window was about office agents that borrow other labs' models, and about who supplies the chips.
ByteDance's Doubao Work joined Tencent's WorkBuddy in selling third-party models to enterprises on Oct 29, while Alibaba and Baidu had no dated model or earnings news and Huawei's chip story rests on press reports, not company statements.
| Company | In-window item | Date (2026) | Status (Nov 3) | Source |
|---|---|---|---|---|
| ByteDance | Doubao Work opens three third-party models to Team and Enterprise | Oct 29 | Announced (media) | BigGo; AIbase |
| Tencent | WorkBuddy features; Hy4 previewed | Oct 29-30 | Hy4 "coming soon" | Tencent Cloud |
| Alibaba | Netherlands cloud region | Oct 29 | Announced | Alibaba Cloud |
| Baidu | No dated item found | n/a | n/a | Kalkine |
| Huawei | $2.25B loan; DeepSeek chip order | Week to Oct 26 | Reported | X.PIN |
| Moonshot | Kimi K3.1 Pro | Oct 23 | Live; weights due Nov 4 | GPTProto |
6.1 ByteDance and the multi-model office agent
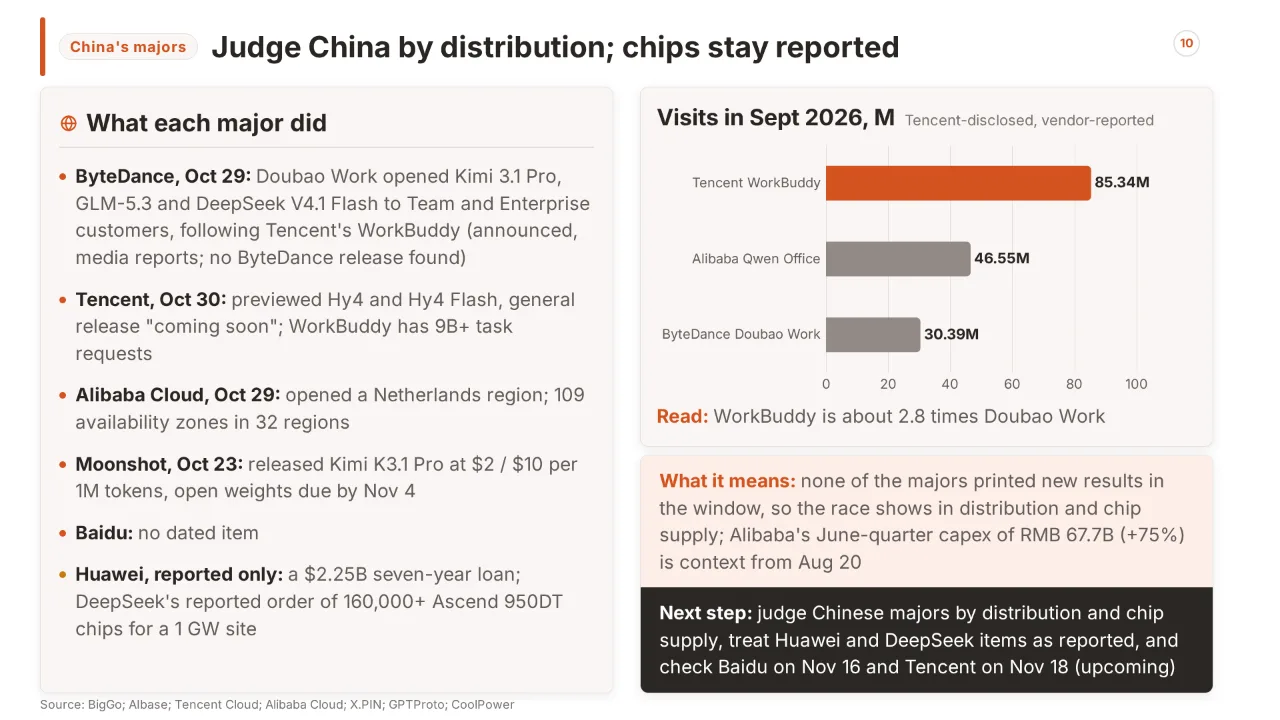
On Oct 29, ByteDance's Doubao Work said it would open third-party models to Team and Enterprise customers only, starting with Kimi 3.1 Pro, GLM-5.3 and DeepSeek V4.1 Flash; individual plans are excluded. Enterprises spend existing AI credits instead of buying API access, and administrators can grant models by member, department, vendor or endpoint. According to AIbase, it is on by default. Both accounts are secondary; we found no ByteDance release.
BigGo says this converges on Tencent's WorkBuddy, which already routes to Hunyuan, GLM, MiniMax, Kimi and DeepSeek, while Alibaba's Qwen Office still offers mainly its own tiers (its Qoder coding agent supports four outside models with Auto routing).
| September 2026 monthly visits | Visits | Third-party models | Source |
|---|---|---|---|
| Tencent WorkBuddy | 85.34M | Yes | BigGo, Tencent-disclosed |
| Alibaba Qwen Office | 46.55M | Mainly proprietary | BigGo, Tencent-disclosed |
| ByteDance Doubao Work | 30.39M | Newly opened (Enterprise) | BigGo, Tencent-disclosed |
Tencent, the leader, disclosed these (vendor-reported): 85.34 ÷ 30.39 ≈ 2.8 times Doubao Work and 85.34 ÷ 46.55 ≈ 1.8 times Qwen Office.
Kimi K3.1 Pro as the model-race reference. Moonshot released it on Oct 23, per the Kimi Code release log as read by GPTProto; hosted access is live and full weights are scheduled by Nov 4, still upcoming. List price is $2 input / $10 output per million tokens against $3 / $15 for Kimi K3, so output is 10 ÷ 15 ≈ 33% cheaper; Highspeed costs $4 / $20. Independent scores are in Chapter 7. X.PIN reports an apology over costs and rate limits, with a 25% monthly quota reset for paid users (reported, week to Oct 26).
6.2 Alibaba, Tencent and Baidu: status and dates
Alibaba. No results or capex update fell in the window. Latest filed capex is the June quarter: RMB 67.7B, up 75% (filed Aug 20; context, not new), against a RMB 380B commitment from February 2025. On Oct 29 Alibaba Cloud opened its first Dutch region (two data centres), reaching 109 availability zones in 32 regions, under a previously announced US$53B investment; at the 6.78 RMB per dollar implied by the June-quarter filing, RMB 380B is about US$56B (380 ÷ 6.78), above the "more than $53B" figure, and the material does not say they are one plan (Chapter 8). Qwen 4 is still "in training" per Alibaba's Sep 22 release; launch-next-week claims are third-party, and on Nov 1 no Qwen 4 model was listed on Hugging Face, Model Studio or OpenRouter (OmniaKey). Alibaba's next results date is not stated in our material.
Tencent. At its Global Digital Ecosystem Summit (Oct 29 per ad-hoc-news; the release is dated Oct 30, which we follow) Tencent said WorkBuddy has handled over nine billion task requests since March, across 50+ industries, 50% of China's top 500 enterprises, 50,000+ developers and partners and 200,000+ skills (company statement). Hy4 and Hy4 Flash were previewed; general release is "coming soon" with no date (announced), and TokenHub offers Hy models beside third-party ones through one API. Results are due Nov 18 (upcoming, per ad-hoc-news); June-quarter capex was RMB 52.8B (context). 36Kr (Nov 2) reports a Hunyuan reorganisation under Yao Shunyu, which Tencent has not called layoffs (reported).
Baidu. No dated company announcement appears in our sources. Latest results were Q2 (Aug 18, context): revenue RMB 31.3B (-4%), AI Cloud Infra RMB 7.3B (+50%), capex RMB 11.4B, free cash flow about -RMB 8.0B (3.4 operating cash flow − 11.4). Yahoo lists the next results for Nov 16 (upcoming; no Baidu confirmation in our material). ERNIE 5.1 is its listed current model; date not stated.
6.3 Huawei and the domestic chip stack
Our material holds no Huawei statement and no Ascend 950 / 960 roadmap; what exists is reported. X.PIN's Oct 26 digest cites Bloomberg for a seven-year, $2.25B offshore loan from six Chinese banks, and says Huawei spent $17B on H1 R&D, leaving cash flow of -$5.6B (reported). It also cites 36Kr: DeepSeek's roughly $15B round is earmarked for a 1 GW Ulanqab, Inner Mongolia, data centre with at least 160,000 Ascend 950DT chips (reported). A Caixin-based report of Oct 14, before the window, put the round at about RMB 100B and quoted DeepSeek's founder calling domestic pre-training "the biggest gamble" (reported); the sizes are unreconciled and neither is a DeepSeek statement.
Other signals: DeepBlue's Wowoker phone (Oct 30) runs on Huawei Kirin chips; MIIT put AI computing capacity at 2,592 EFLOPS at end-September, up 146% (published Oct 20, context); an X post, date not stated, says ByteDance, Alibaba and Tencent placed $35B of Nvidia orders (reported).
Judgement. The window shows convergence on distribution (multi-model agents) and dependence on chips visible only through reports; none of the majors printed new financial results.
7. Products and model comparison
Chapter 6 showed ByteDance and Tencent opening their office agents to rival models; this chapter checks how good those models are, what they cost, and which platform hosts whose.
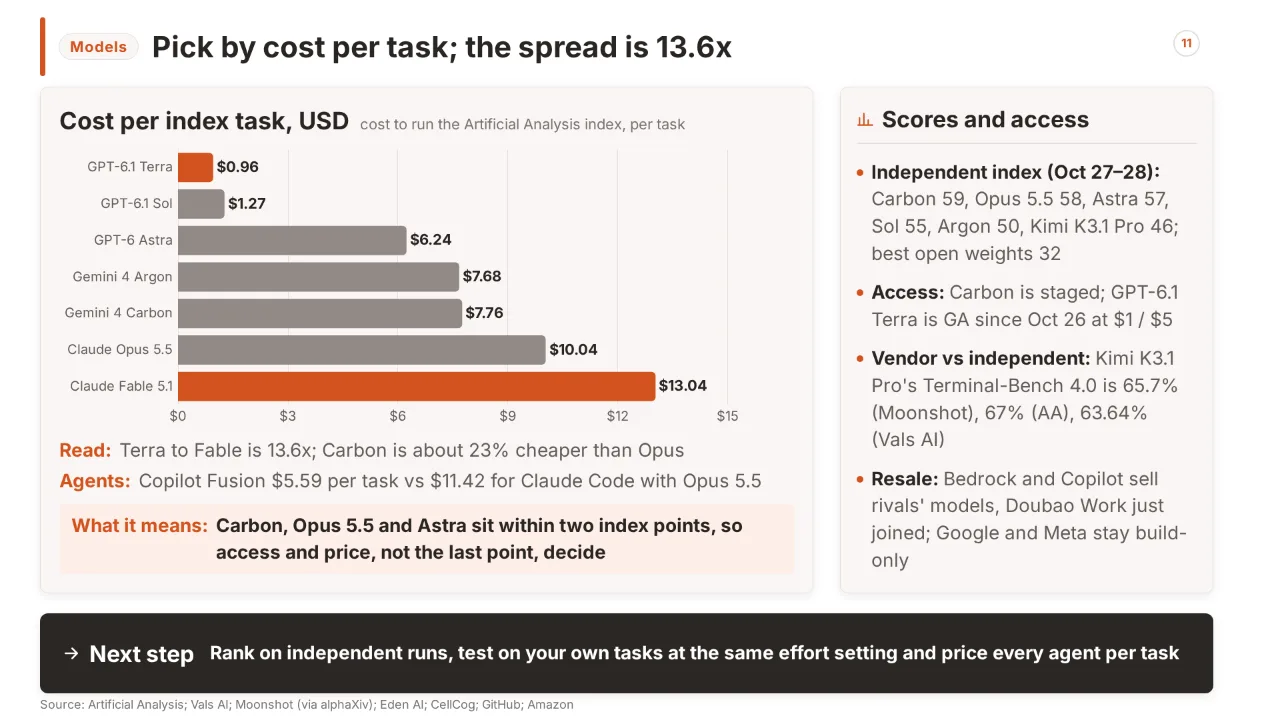
On the Artificial Analysis (AA) Intelligence Index v5, published Oct 27–28, 2026, Gemini 4 Carbon leads at 59, only 1 point ahead of Claude Opus 5.5 (58) and 2 ahead of GPT-6 Astra (57). Carbon is still in staged release, and cost per task spans 13.6× across the leading models, so access and price decide more than the last index point.
7.1 Independent ranking: Intelligence Index v5
AA (the benchmark maintainer) released v5 on Oct 27, 2026: nine evaluations, with 60% of the index on private or held-out test sets. Its Carbon write-up followed on Oct 28. All figures below are AA's, at the effort shown, with cost at standard (not launch-discount) prices.
| Company | Model (effort) | Index v5 | Cost per task | Source |
|---|---|---|---|---|
| Gemini 4 Carbon (high) | 59 | $7.76 | AA | |
| Anthropic | Claude Opus 5.5 (max) | 58 | $10.04 | AA |
| OpenAI | GPT-6 Astra (max) | 57 | $6.24 | AA |
| OpenAI | GPT-6.1 Sol (max) | 55 | $1.27 | AA |
| Gemini 4 Argon (high) | 50 | $7.68 | AA | |
| Moonshot AI | Kimi K3.1 Pro | 46 | not stated | AA |
| OpenAI | GPT-6.1 Terra (max) | not stated | $0.96 (cheapest of top 10) | AA |
| Anthropic | Claude Fable 5.1 (max) | not stated | $13.04 (dearest of top 10) | AA |
AA's two pages give Astra's cost as $6.24 and $6.25; we follow the v5 announcement. The index rescaled: Kimi K3.1 Pro was reported at 55 on its Oct 23 release, under the earlier index, and is 46 on v5.
Carbon is first on four of nine evaluations, but no model leads all of them. Opus 5.5 leads three, including HLE-Diamond (68%). On AA's Coding Agent Index, Claude Code with Opus 5.5 scores 62 against Carbon's 59.
Cost arithmetic: Carbon 7.76 ÷ 10.04 = 0.77, about 23% cheaper than Opus 5.5 per task. Sol at 1.27 ÷ 10.04 = 0.13 costs about an eighth of Opus for 3 fewer points. Terra to Fable is 13.04 ÷ 0.96 = 13.6×. Open weights fall behind: Kimi is 12 points under the Oct 27 leader (58), and the best released weights, DeepSeek V4.1 Flash 1017 and GLM-5.3, score 32.
7.2 Vendor-reported versus independent claims
Carbon's cyber results are vendor-reported. Google (Oct 28) reports 88.2% on SEC-bench Pro, 54.8% on ExploitGym and 71.0% on CWE-bench, evaluated without guardrails, plus #4 on WebDev Arena at 1768 (+89 Elo). The material holds no independent replication. AA's index number (59) is independent and matches Google's citation.
OpenAI's Terra claims are vendor-reported. On OpenAI's Agents' Last Exam, Terra at medium effort scores 57.6% at $0.29 per task, equal to Astra's 57.6% at $4.82, a 4.82 ÷ 0.29 = 16.6× gap; at max effort Terra scores 60.0% ($1.01) against Opus 5.5's 63.2% ($8.82) (per CellCog and Kingy.ai). Independent check: Vals AI puts Terra at 60.17% on Vals Index v2.2, #10 of 28.
One benchmark, three answers. Kimi K3.1 Pro's Terminal-Bench 4.0 result depends on who ran it:
| Runner | Kimi K3.1 Pro | Claude Opus 5.5 | Source |
|---|---|---|---|
| Moonshot (vendor) | 65.7% | 66.4% | Moonshot (via alphaXiv) |
| AA (independent) | 67% | 60% | AA (via a video review) |
| Vals AI (independent) | 63.64% | 65.15% | Vals AI |
On Vals Index v2.2, Kimi (62.52%) edges DeepSeek V4.1 Flash 1017 (61.26%), Terra (60.17%) and GLM 5.3 (59.73%). We rank on independent runs and read vendor charts as direction only.
7.3 Access and price, as of Nov 3
| Model | Status and access | List price per 1M (in / out) | Source |
|---|---|---|---|
| Gemini 4 Carbon | Announced Oct 28; staged: cyber defenders now, Fairwind partners next, others "as soon as possible", no date | $2 / $10 intro, then $4 / $20; no end date stated | Google; Apidog |
| Gemini 4 Argon | GA since Oct 13 (context): paid Gemini API, AI Studio, Pro and Ultra in the app | $2 / $10 to Nov 30, $4 / $20 from Dec 1 | Apex Logic |
| GPT-6.1 Terra | GA Oct 26: API, ChatGPT Work and Codex (Plus, Pro, Enterprise, Edu) | $1 / $5 | CellCog; llm-stats |
| Claude Opus 5.5 | GA (shipped September, per AA) | $4 / $20 | Eden AI; AA |
| GPT-6.1 Sol, Sonnet 5.5 | GA | $2 / $10 each | Aleinikov |
| GPT-6 Astra | GA | $10 / $50 | Eden AI |
| Kimi K3.1 Pro | Live Oct 23 on Kimi API; open weights upcoming (due by Nov 4, per Moonshot) | $2 / $10 | Vals AI; Moonshot |
| Qwen3.8-Max | No window event; list price conflict | $2 / $6 (registry, Oct 17) vs $1.4 / $4.2 (reseller) | Developers Digest; GPTProto |
We follow the registry's first-party Qwen list price. Argon's intro rate is in effect and ends Nov 30; Carbon's standard rate matches Opus 5.5's card. Terra's price is a quarter of Opus's per token, and AA's task costs give 10.04 ÷ 0.96 = 10.5×.
Our judgement: among models anyone can buy today, Sol (55 at $1.27) and Terra ($0.96) are the value picks, Opus 5.5 is the premium pick, and Argon (50 at $7.68, 6.0× Sol's cost) is the weakest value on AA's numbers. Carbon cannot be bought yet.
7.4 Build versus partner map
| Platform | Own models | Third-party models | Source |
|---|---|---|---|
| Microsoft Copilot, GitHub Copilot | MAI Code 1.1 Flash (local) | GPT-6.1 Sol and Claude Sonnet 5.5 as model choices; Qwen3.8 Flash Next locally; Fusion routes among Claude and GPT models | Dellenny; GitHub; AA |
| Google Gemini | Gemini 4 only | None listed in the material | |
| Amazon Bedrock | Not Amazon's own | OpenAI GPT-6 family, Claude, Kimi K3, Grok 4.7, GLM 5.3; Managed Agents (public preview) powered by OpenAI | Amazon (Oct 29) |
| Meta Muse | Muse Wonder, Wonder Full | None; reach via Meta API, OpenRouter, Muse Code | Overchat |
| ByteDance Doubao Work | Doubao | Kimi 3.1 Pro, GLM-5.3, DeepSeek V4.1 Flash (Oct 29) | BigGo |
Copilot Fusion (an opt-in experimental preview, Chapter 2) scores 2 points under Claude Code with Opus 5.5 on AA's Coding Agent Index at $5.59 per task against $11.42. Alibaba's Qwen Office still mainly offers its own models. Bedrock and Copilot sell rivals' models, Doubao Work just joined them, and Google and Meta stay build-only.
8. Capex, financing and partnerships
Chapter 7 compared what the companies ship; this chapter sets the capex, cash-flow and contract numbers behind it side by side.
8.1 Capex by company: actuals, guidance and estimates
Microsoft and Alphabet reported on Oct 28 and Amazon on Oct 29, inside the window. Meta's Oct 21 results and Alibaba's August filing are context. Quarter figures are actuals; full-year figures are guidance.
| Company | Jul–Sep capex (actual) | 2026 outlook (guidance) | Reported | Source |
|---|---|---|---|---|
| Microsoft (FY27 Q1) | $45.2B incl. finance leases; consensus $50.67B | about $170B calendar 2026, from about $175B | Oct 28 | CNBC |
| Alphabet | $51.36B vs $55.09B expected | $195–205B kept; 2027 "increase significantly" | Oct 28 | CNBC |
| Amazon | $75.9B cash capex | about $220B cash capex; 2027 "meaningfully more" | Oct 29 | Business Insider |
| Meta | $34.9B incl. finance-lease principal | $135–145B, floor raised from $130B | Oct 21 (context) | S&P Global Ratings |
| Alibaba | RMB 67.7B (US$9.98B), quarter to Jun 30 | RMB 380B over three years | Filed Aug 20 (context) | CoolPower |
Definitions differ. Microsoft and Meta include finance leases; Amazon's figure is cash capex, and its release shows gross property purchases of $77.26B, so the $1.36B gap (77.26 − 75.9) is probably proceeds and incentives, which the material does not break out. Microsoft's cut reflects delay, not retreat: CFO Amy Hood said third-party GPU providers pushed capacity into the first half of 2027, where she expects spending to accelerate.
Arithmetic. Q3 actuals: 45.2 + 51.36 + 75.9 + 34.9 = $207.4B. Guidance: 170 + 195 + 220 + 135 = $720B to 170 + 205 + 220 + 145 = $740B. Alphabet's nine-month capex of $132.0B implies Q4 of $63–73B (195 − 132; 205 − 132), 1.2 to 1.4 times Q3 (according to FinanceFeeds).
Third-party tallies are estimates. The Kobeissi Letter put Q3 combined capex at $201.9B and Q4 plans at $232B. That is $5.5B below our sum and implies Amazon at about $70.4B (201.9 − 51.36 − 45.2 − 34.9), not $75.9B; the material does not explain the gap, so we follow the company-sourced figures. Business Insider, citing Fortune, adds SpaceX for $803–828B in 2026; removing SpaceX's up to $88B from 828 gives 740, our top end.
Alibaba has nothing dated in the window on capex, and its next results date is not stated in the material. A Sept 22 report of "more than $53B over three years" is consistent with RMB 380B at the filing's implied 6.78 rate (380 ÷ 6.78 = $56.0B, above $53B), though the material does not say they are one plan. On Oct 29 Alibaba Cloud opened its first Netherlands region (shipping).
8.2 Financing paths and cash-flow arithmetic
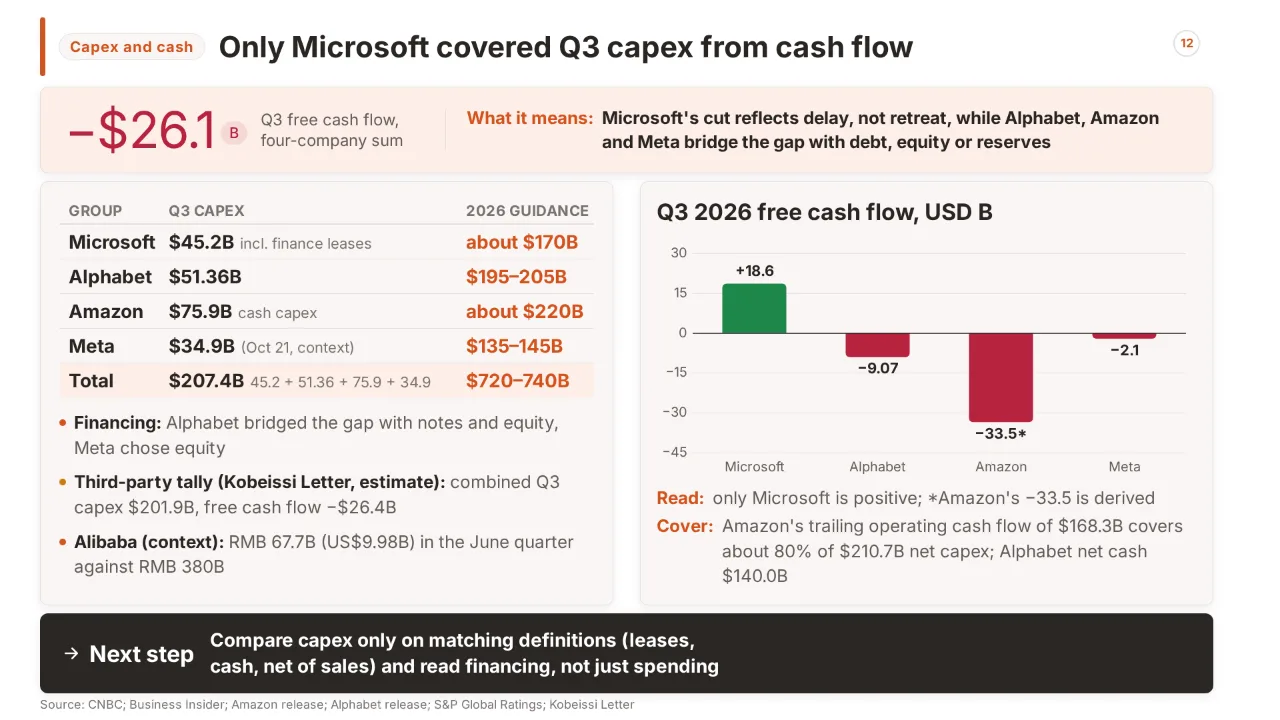
Only Microsoft covered its Q3 capex from cash flow; Alphabet, Amazon and Meta bridged the gap with debt, equity or reserves.
| Q3 2026, $B | Operating cash flow | Capex | Free cash flow | Source |
|---|---|---|---|---|
| Microsoft | not in material | 45.2 | +18.6 | video summary |
| Alphabet | 42.29 | 51.36 | −9.07 | CNBC; FinanceFeeds |
| Amazon | 42.4 | 75.9 | −33.5 (derived) | Amazon release; Business Insider |
| Meta | 32.79 | 34.9 | −2.1 | S&P; Meta release via FourWeekMBA |
Checks: 42.29 − 51.36 = −9.07; 42.4 − 75.9 = −33.5 (−34.8 on gross purchases of 77.26); 34.9 − 2.1 = 32.8. The sum, 18.6 − 9.07 − 33.5 − 2.1 = −$26.1B, is within $0.3B of Kobeissi's estimate of −$26.4B. Amazon's trailing twelve months: operating cash flow $168.3B, free cash flow −$42.4B, so net capex was 168.3 + 42.4 = $210.7B, about 80% covered by cash flow (168.3 ÷ 210.7).
Alphabet financed externally. Its release reports Q3 senior notes of $28.7B and at-the-market equity of $12.4B (4.3 + 8.1), together $41.1B, about 4.5 times the deficit (41.1 ÷ 9.07); the June quarter brought $49.6B of equity and $20.3B of notes (context). Cash of $265.1B against long-term debt of $125.1B leaves net cash of $140.0B. Meta chose equity. On Oct 26 it priced $12.5B of 6.50% mandatory convertible preferred and $25.0B of Class A stock at $625.00, and plans up to $60B more through a Class C at-the-market programme from Q1 2027: 12.5 + 25.0 + 60 = $97.5B, against $95B (35 + 60) at launch. Meta expects no initial proceeds from the Class A forward sale, which settles by Nov 19, 2027. It ended Q3 with $82.4B of cash against $83.7B of total debt (long-term debt $80.92B, Chapter 4), net debt of $1.3B. S&P (estimate, Oct 30) forecasts free operating cash flow of −$22B in 2026, −$71B in 2027 and −$39B in 2028; Chapter 4 covers the structure.
According to Altcoin Buzz, citing S&P Global Market Intelligence via Axios, Alphabet, Amazon, Meta, Microsoft and Oracle raised $326B of debt and equity in 2026, over three times 2025 (reported; date not stated).
8.3 Contract and partnership map
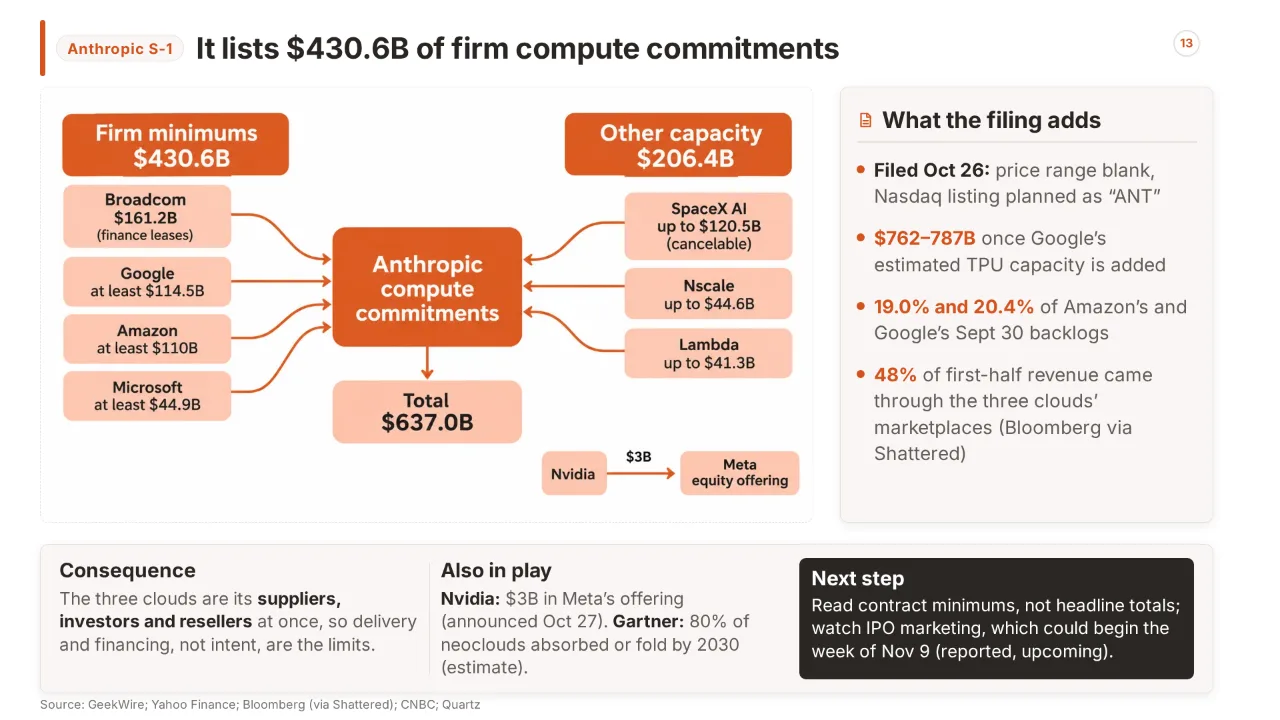
Anthropic's S-1, filed Oct 26 with the price range blank and a planned Nasdaq listing as "ANT", puts its compute contracts in one place. Our material holds only its cover pages, so the figures come from GeekWire and Yahoo Finance, which agree.
| Counterparty | Commitment | Term and cancellability | Source |
|---|---|---|---|
| Broadcom | $161.2B | five-year finance leases of TPU hardware; not cancelable short of default | GeekWire |
| at least $114.5B, plus estimated $125–150B TPU capacity | through July 2033; payable "regardless of actual usage" | GeekWire | |
| Amazon | at least $110B | through April 2036 | GeekWire |
| Microsoft | at least $44.9B | Nov 2026–May 2033; up from $30B | GeekWire |
| SpaceX AI (ex-xAI) | up to $120.5B | into 2029; 90-day cancel right after early 2027 | GeekWire |
| Nscale / Lambda | up to $44.6B / $41.3B | Nvidia-chip capacity | GeekWire |
Arithmetic: 161.2 + 114.5 + 110 + 44.9 = $430.6B of firm commitments, Yahoo's "about $430B". Adding SpaceX, Nscale and Lambda (120.5 + 44.6 + 41.3 = 206.4) gives $637.0B; Google's estimated TPU capacity lifts it to $762–787B, GeekWire's "more than $750B". The TPU line is an estimate and the SpaceX deal is cancelable.

Against backlog, Yahoo puts Anthropic at 22% of AWS's and Google Cloud's June 30 backlogs (110 ÷ 496; 114.5 ÷ 514). On Sept 30 backlogs our ratios are 19.0% (110 ÷ 578) and 20.4% (114.5 ÷ 561). SpaceX alone is about $3.1B a month at full delivery (expected in December), against under $2B a month of total compute spend in Q2. Per Bloomberg via Shattered, the three clouds' marketplaces were 48% of its first-half revenue, so supplier, investor and reseller are the same companies. Bloomberg reported IPO marketing could begin the week of Nov 9 (reported; upcoming).
Nvidia is the other financier. On Oct 27 (company statement) it said it will invest $3B in Meta's offering while Meta expands use of Vera Rubin GPUs, Vera CPUs and Spectrum-X. No price, share count or instrument was disclosed, so $3B ÷ $97.5B, about 3%, is a size ratio, not a stake. Its supplier financing predates the window: on Oct 21 (context) it announced six supplier agreements, including a $1.1B capacity advance to KYEC.
Capacity partners are the weak link. The delays Hood cited involve neoclouds such as CoreWeave, IREN and Nebius, on which CNBC says Microsoft relies; Firmus withdrew its IPO, and Gartner predicts 80% of neoclouds will be absorbed or fold by 2030 (estimate). Guidance is flat to lower while contracts rise: delivery and financing, not intent, are the limits.
9. Competitive outlook and what to watch next
Chapters 2–8 showed the large groups answering one question in different ways: how much of the AI stack to build, how much to rent, and how to pay for it. This chapter turns that into a strategy comparison, implications for three readers and a dated watch-list. It describes; it is not investment advice.
9.1 Strategy side by side
| Company | Build / partner / buy | Chips | Flagship model | Capex and financing stance | Source |
|---|---|---|---|---|---|
| Microsoft | Small in-house models (preview); sells OpenAI and Anthropic in Copilot | Not covered in the window | Sells GPT-6.1 Sol (AA 55) | $45.2B quarter; about $170B in 2026; cash flow | — |
| Alphabet | Builds Gemini; rents third-party compute | TPU systems, nearly 100 customers | Gemini 4 Carbon (AA 59, staged) | $51.36B quarter; $195–205B; notes and ATM equity | — |
| Meta | Builds Muse; no third-party models | Nvidia Vera Rubin; $3B Nvidia investment | Muse Wonder (no score in window) | $135–145B (context); equity up to $97.5B | — |
| Amazon | Hosts rival models on Bedrock; builds chips | Trainium, Graviton | None of its own on AA | About $220B cash capex; TTM FCF −$42.4B | — |
| Apple | Devices first; own Siri AI | Not covered in the window | "All-new Siri AI" (Apple) | No capex figure; R&D $11.7B (+32%) | — |
| China's majors | Multi-model office agents | Ascend 950DT in DeepSeek's reported order | Kimi K3.1 Pro (AA 46) | No new results; Alibaba RMB 380B plan (context) | — |
9.2 What the fortnight means, by reader
| Reader | What changed | Implication | Evidence |
|---|---|---|---|
| Enterprise buyers | AWS (+39%), Azure (+48%) and Google Cloud (+103%) all accelerated; Copilot, Bedrock and Doubao Work sell rival models; Carbon is staged | Choose the cloud where your data sits, write model choice into the contract, and do not plan on Carbon until a developer date exists | — |
| Builders | Carbon leads the index by 1 point; cost per task spans 13.6× (Terra $0.96 to Fable $13.04); best open weights score 32 against 58 | Keep the model layer swappable, test on your own tasks, budget per task and trust independent runs | — |
| Investors and strategists | Q3 capex $207.4B against $720–740B guided; free cash flow negative at Alphabet, Amazon and Meta; Meta's plan reaches $97.5B; S&P estimates −$71B free operating cash flow in 2027 | The question is funding and delivery, not demand; 2027 capex numbers are the next test | — |
Demand is no longer the open question for the big clouds; funding and delivery are, so buy on where your data sits, keep models swappable, and read capex as a financing story.
Three judgements follow. First, quality is near parity and access decides. Carbon, Opus 5.5 and Astra sit within two index points (59, 58, 57), yet Carbon is not yet generally available, while Terra costs about a tenth of Opus per task (10.04 ÷ 0.96 = 10.5×). Second, suppliers are also financiers. The three clouds are Anthropic's compute suppliers, investors and resellers, and Nvidia is putting $3B into a customer's equity offering. Third, China moves on distribution while chip facts stay in press reports. Doubao Work and WorkBuddy converge on multi-model agents, none of the majors printed new results in the window, and the Huawei and DeepSeek order is reported, not confirmed.
9.3 Key dates
Dates already past on Nov 3, 2026 are marked "In effect" (or the matching status word).
| Date | Event | State on Nov 3, 2026 | Source |
|---|---|---|---|
| Oct 26, 2026 | Meta prices $12.5B preferred and $25.0B Class A; ATM announced | In effect (priced); ATM planned | Meta |
| Oct 26, 2026 | Anthropic S-1 filed; Microsoft Voluntary Exit Offer | In effect (filed; offer open) | GeekWire; Reuters |
| Oct 28, 2026 | Microsoft and Alphabet Q3 results | In effect (reported) | Microsoft; Alphabet |
| Oct 28, 2026 | Gemini 4 Carbon announced; cyber defenders first | In effect (staged); wider access upcoming | |
| Oct 29, 2026 | Amazon Q3 results; Doubao Work opens third-party models | In effect (reported; announced) | Amazon; BigGo |
| Oct 30, 2026 | S&P moves Meta outlook to negative | In effect | S&P |
| Nov 2, 2026 | Apple fiscal Q4 results | In effect (reported) | Apple 8-K |
| Nov 4, 2026 | Kimi K3.1 Pro open weights due | Upcoming | Moonshot |
| Week of Nov 9, 2026 | Anthropic IPO marketing could begin (Bloomberg) | Upcoming (reported) | GeekWire |
| Nov 16, 2026 | Baidu results (per Yahoo; no Baidu confirmation) | Upcoming | Yahoo Finance |
| Nov 18, 2026 | Tencent Q3 results | Upcoming (scheduled) | ad-hoc-news |
| Nov 30, 2026 | Argon introductory API price ends | Upcoming | Apex Logic |
| Early Dec 2026 | Microsoft exit-offer decisions; leavers go Dec 31 | Upcoming (reported) | Fortune |
| Jan 19, 2027 | Meta Class C charter effective | Upcoming | Meta 424B5 |
| Q1 2027 | Meta Class C ATM up to $60B (not before) | Upcoming (planned) | Meta |
| Date not stated | 2027 capex: Alphabet "increase significantly", Amazon "meaningfully more", Meta on its Q4 call | Upcoming | CNBC; Business Insider |
10. References
This document draws on the following 105 sources, listed in the order they are first cited.
- Microsoft (MSFT) Q1 earnings report 2027 — cnbc.com
- Alphabet (GOOGL) earnings Q3 2026 — cnbc.com
- AI hyperscalers expected to spend up to a whopping $828B in 2026 — businessinsider.com
- Meta Platforms Inc. Outlook Revised To Negative O — spglobal.com
- Microsoft (#MSFT) FY27 Q1 Earnings — Azure +48%, EPS Beat, Q2 Azure Guide +49% | Earnings Report — youtube.com
- Alphabet Stock $292 After Q3 Miss: -$9B Free Cash Flow — financefeeds.com
- Document — sec.gov
- Meta - Meta Announces Pricing of Offering of Depositary Shares Representing Series A Mandatory Convertible Preferred Stock and Offering of Class A Common Stock in Connection with Forward Sale Agreements — investor.atmeta.com
- Document — sec.gov
- Alphabet Q3 Earnings Call Highlights | MarketBeat — marketbeat.com
- Amazon.com, Inc. - Amazon.com Announces Third Quarter Results — ir.aboutamazon.com
- Amazon (AMZN) Q3 2026 Earnings Call Transcript | The Motley Fool — fool.com
- Microsoft announces first quarter results - Source — news.microsoft.com
- AI buildout hits snag as Google and Microsoft hold capex forecasts — cnbc.com
- Gemini 4 Carbon is the new #1 on the Artificial Analysis Intelligence Index v5 | Artificial Analysis — artificialanalysis.ai
- Announcing Artificial Analysis Intelligence Index v5 | Artificial Analysis — artificialanalysis.ai
- Introducing Gemini 4 Carbon — blog.google
- Gemini 4 Carbon Release Date and API Access: Who Can Use It Now — apidog.com
- Genie 4: A new generation of world simulation — Google DeepMind — deepmind.google
- ByteDance's Doubao Work Opens Third-Party LLMs to Enterprise Clients, Heating Up Multi-Model Race in Office Agents — BigGo Finance — finance.biggo.com
- Microsoft Copilot Adds GPT-6.1 Sol and Claude Sonnet 5.5 Across Microsoft 365 — dellenny.com
- GitHub Copilot Fusion now supports selection of local models - GitHub Changelog — github.blog
- Who’s getting Anthropic’s compute spending? IPO filing shows where the tech giants really stand – GeekWire — geekwire.com
- Anthropic's IPO filing reveals $430 billion in locked-in AI computing: Chart of the Day — finance.yahoo.com
- Nvidia to invest $3 billion in Meta's equity offering — qz.com
- Nvidia Meta $3 Billion Investment Explained 2026 — shattered.io
- Meta Announces Launch of Offering of Depositary Shares Representing Series A Mandatory Convertible Preferred Stock and Offering of Class A Common Stock in Connection with Forward Sale Agreements — investor.atmeta.com
- Document — sec.gov
- Microsoft offers buyouts to around 60,000 employees to contain costs | Reuters — reuters.com
- Microsoft’s 60,000-person buyout offer hints at a future with fewer workers and more equipment | Fortune — fortune.com
- Microsoft AI — microsoft.ai
- MAI Cyber 1.1 Flash: Sharper findings and fewer tokens inside MDASH | Microsoft AI — microsoft.ai
- Claude for Excel vs Copilot vs ChatGPT: US$0-125 2026 — tech-insider.org
- Microsoft FY27 Q1 Results: Azure Up 48% | LicenseQ — licenseq.com
- AI Capex Boom: $828B Spend, Nasdaq Down 2.9% 2026 — tech-insider.org
- Microsoft offers voluntary buyouts to more than 25% of its workforce | king5.com — king5.com
- MAI-Cyber-1.1-Flash | Microsoft AI — microsoft.ai
- Alphabet Announces Third Quarter 2026 Results — abc.xyz
- Alphabet Q3 2026 Earnings Slides — abc.xyz
- Alphabet Q3 2026 Earnings: Cloud +103%, TPUs & AI Capex — nextgcomm.com
- Document — sec.gov
- Document — sec.gov
- Alphabet Inc. (GOOGL) Earnings & Analysis — stockrow — stockrow.com
- Google Cloud Hits 103% Growth as Alphabet Misses Revenue, Reports Highest-Ever Quarterly Capex — techtimes.com
- Google Stock (GOOGL) Falls 12.6% After Q3 Earnings Report (Oct 29) | Gotrade — heygotrade.com
- ALPHABET INC (GOOGL.MX) Q3 FY2026 earnings call transcript — finance.yahoo.com
- Gemini 4 Carbon Beats Opus 5.5 and GPT-6 Astra: The Catch — edenai.co
- Gemini 4 Carbon Benchmarks, Pricing (2026) | NeuralTrust — neuraltrust.ai
- 8-K — sec.gov
- Meta - Meta Announces Launch of Offering of Depositary Shares Representing Series A Mandatory Convertible Preferred Stock and Offering of Class A Common Stock in Connection with Forward Sale Agreements — investor.atmeta.com
- 424B5 — sec.gov
- NVIDIA and Meta Expand Partnership on Muse AI Models and Next-Gen AI Infrastructure | Quiver Quantitative — quiverquant.com
- Meta Platforms Inc. Outlook Revised To Negative O — spglobal.com
- S&P cuts Meta outlook to negative amid capex concerns — finance.yahoo.com
- Meta Credit Rating Outlook Cut to Negative on AI Spending — emergent.sh
- Meta's Capex Rose 80% and Free Cash Flow Swung to -$2.1B - FourWeekMBA — fourweekmba.com
- Meta Q3 2026 FCF Turns Negative Amid AI-Driven Spending — kucoin.com
- Financial analysis of Meta Platforms (META), Q3 2026 earnings — sec-api.io
- Amazon Earnings Preview: AWS Backlog Meets $220B Capex — tastylive.com
- AWS Grows 39.3%, Amazon Q3 2026 Earnings Hit Stock — shattered.io
- Amazon Q3 2026: AWS revenue rose 39% as EPS missed expectations | 24/7 Wall St. — 247wallst.com
- Amazon (AMZN) Q3 Earnings: AWS Surges 39% & EPS Miss — trendspider.com
- Amazon earnings live: Q3 earnings miss sends stock lower — finance.yahoo.com
- Apple earnings November 2: time, what to expect and how to listen — applescoop.org
- Apple (AAPL) Q4 2026 Earnings Date, Time & Estimates — marketbeat.com
- Retirees Holding Apple Stock Should Keep an Eye on This Earnings Report - AOL — aol.com
- Doubao Work Officially Integrates DeepSeek, Kimi, and GLM, Making Enterprise Procurement Completely Hassle-Free — news.aibase.com
- Tencent Cloud Accelerates International Growth, Advances Enterprise AI and Expands Global Partnerships — prnewswire.com
- Alibaba Cloud Launches First Public Cloud Region in the Netherlands — TradingView News — tradingview.com
- Why is Baidu betting on AI cloud as advertising shrinks? — kalkine.com.au
- Weekly Dose of China Tech 10.26.2026 - by X.PIN and Xu Yan — thexpin.com
- What Is Kimi K3.1 Pro? Pricing, Benchmarks & K3 Upgrade — gptproto.com
- China data centres and AI infrastructure: capacity, companies, chips and policy | CoolPower Index — coolpowerindex.com
- Qwen 4 Release Date: What Alibaba Has Confirmed So Far · OmniaKey — omniakey.com
- Tencent previews Hy4 and Hy4 Flash as Tencent Holdings stock nears yearly low — ad-hoc-news.de
- Tencent Holdings stock: Hy4 preview expands enterprise AI strategy — ad-hoc-news.de
- Tencent Hunyuan’s Painful Transition Period: New Leadership Takes Over as Former Core Team Steps Down — eu.36kr.com
- Baidu, Inc. (BAIDF) Stock Price, News, Quote & History - Yahoo Finance — ca.finance.yahoo.com
- Chinese AI Models in 2026: DeepSeek, Qwen, Kimi & More – Dymesty AI Glasses — dymesty.com
- DeepSeek Nears $14B Round; V4.1 Flash Leads - news - rxa ai nav — rxa.cc
- NVIDIA Invests $3 Billion in Meta, Locking In Next-Gen Hardware Demand | 24/7 Wall St. — 247wallst.com
- Kimi K3.1 Pro Tech Blog: Advancing Open Intelligence | alphaXiv — alphaxiv.org
- GPT-6.1 Terra: $1/$5 Price, Benchmarks vs Sol and Opus | CellCog — cellcog.ai
- GPT-6.1 Terra: Benchmarks, Pricing & Model Comparisons — kingy.ai
- GPT-6.1 Terra Benchmarks, Cost and Capabilities | Vals AI — vals.ai
- Kimi K3.1 Pro vs Opus 5.5: one benchmark, three answers — youtube.com
- Kimi K3.1 Pro Benchmarks, Cost and Capabilities | Vals AI — vals.ai
- Gemini 4 Carbon: Release Date, Pricing, Access and vs Argon | Apex Logic — apex-logic.net
- GPT-6.1 Terra Benchmarks, Pricing & Context Window — llm-stats.com
- Gemini 4 Carbon (High) vs Claude Opus 5.5 (Max, Default Fallback): Model Comparison | Artificial Analysis — artificialanalysis.ai
- GPT-6.1 Terra vs Sonnet 5.5 vs Sol: Pricing, Benchmarks — alekseialeinikov.com
- AI Model API Pricing and Specs (2026) - Developers Digest — developersdigest.tech
- Kimi K3.1 Pro API for Coding Agents | GPTProto — gptproto.com
- GPT-6.1 Terra: pricing, benchmarks, and when to pick it over Sol | eesel AI — eesel.ai
- GitHub Copilot Fusion orchestrates Anthropic and OpenAI models to balance performance and cost | Artificial Analysis — artificialanalysis.ai
- Muse Wonder vs Muse Spark: Meta's New Model Tested — overchat.ai
- AI is burning Big Tech's free cash flow: The combined CapEx of Amazon, Alphabet, Meta and Microsoft, rose +$36.9 billion in Q3 2026, to a record $201.9 billion. This figure has more than doubled… | The Kobeissi Letter — linkedin.com
- Alibaba Group Holding (NYSE:BABA) Stock Forecast & Analyst Predictions - Simply Wall St — simplywall.st
- AI capex surge pushes Big Tech free cash flow below zero — TradingView News — tradingview.com
- Alphabet Q3 Earnings Call Highlights — TradingView News — tradingview.com
- Big Tech's $202B AI Spending Pushes Cash Flow Under Pressure — altcoinbuzz.io
- Anthropic, PBC - S-1 (Q2) — sec.gov
- Anthropic Cloud Marketplace Revenue Hits 48% 2026 — shattered.io
- Nvidia is bankrolling AI accelerator supply chain buildout to reserve production capacity — announces billion-dollar deals with six major suppliers across substrates, advanced packaging, semiconductor testing, and optical engines | Tom's Hardware — tomshardware.com
- NVIDIA expands manufacturing capacity to meet AI demand — manufacturing-today.com