Energy Storage & Batteries — Biweekly Brief (Oct 9–22, 2026)
Contents
- Key takeaways from the two weeks
- Lithium and storage-cell prices
- System, EPC and tender prices
- Manufacturers — Q3 results and shipments
- Capacity, orders and supply chain
- Technology — sodium-ion, solid-state and beyond lithium
- China projects, tenders and policy
- Overseas markets
- Outlook and what to watch
1. Key takeaways from the two weeks
Between 9 and 22 October 2026, three things happened at once in energy storage. The raw-material cost floor dropped, the first Q3 results showed the industry earning less per GWh, and the order book moved further offshore. The five conclusions below summarise Chapters 2–8. Every figure is cited where it is first developed.
1.1 Five conclusions
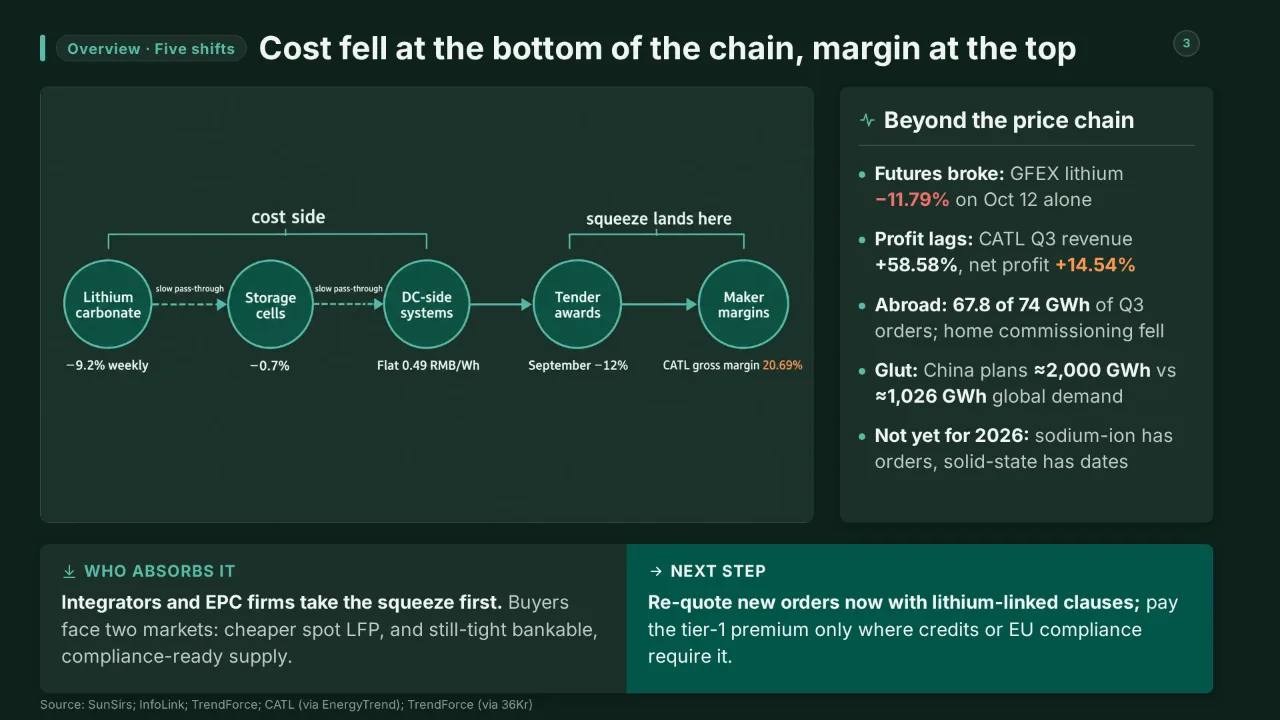
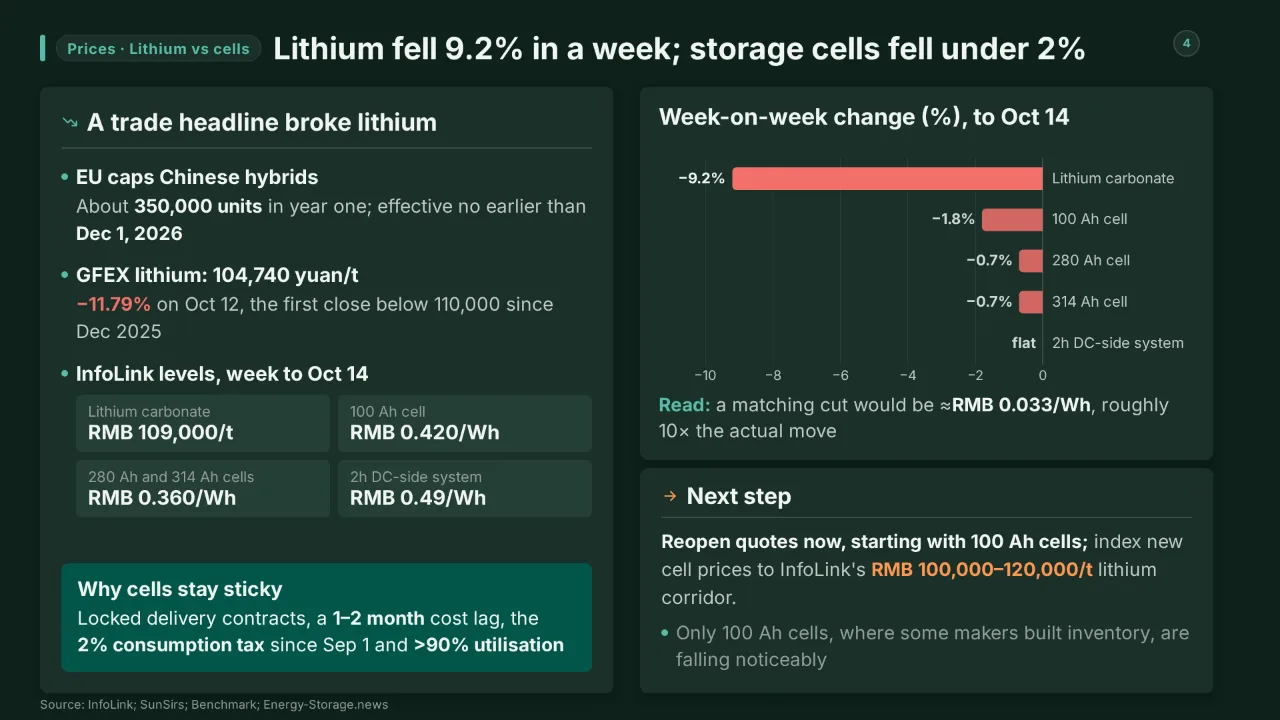
1. Lithium broke, but cells barely moved, so new orders give buyers leverage while delivered prices lag. On 12 October the most-traded GFEX lithium carbonate contract closed at 104,740 yuan/t, down 11.79% in one session, after the EU announced a cap on Chinese hybrid imports. InfoLink's weekly spot average fell 9.2% to RMB 109,000/t, while mainstream 280/314 Ah LFP storage cells slipped only 0.7% to RMB 0.360/Wh and 2-hour DC-side systems stayed flat at RMB 0.49/Wh. Locked delivery contracts, a one-to-two-month cost-transmission lag and the 2% consumption tax in effect since 1 September all slow the pass-through (Chapter 2).
2. Tender awards turned down before spot quotes did. TrendForce's September database shows weighted-average awarded prices of RMB 0.53/Wh for 4-hour systems (−12% month on month), RMB 0.60/Wh for 2-hour systems (−21%) and RMB 0.78/Wh for 4-hour EPC (−12%). That reverses the H1 rebound CNESA recorded, when 4-hour bids averaged RMB 541.3/kWh, up 21.1%. Most of the decline sits in EPC margins and 2-hour equipment. Four-hour hardware awards held in a narrow RMB 0.52–0.58/Wh band (Chapter 3).
3. Volume is still growing, but profit per GWh is not. CATL's Q3 revenue rose 58.58% to RMB 165.221 bn, while net profit rose only 14.54% and gross margin fell to 20.69%, its lowest since Q4 2022. Tesla deployed 13.7 GWh of storage (+9.6%), yet its energy revenue fell 16% to US$2.88 bn, partly because of tariff-related customer refunds. Price pressure has moved from cell quotes into reported margins (Chapter 4).
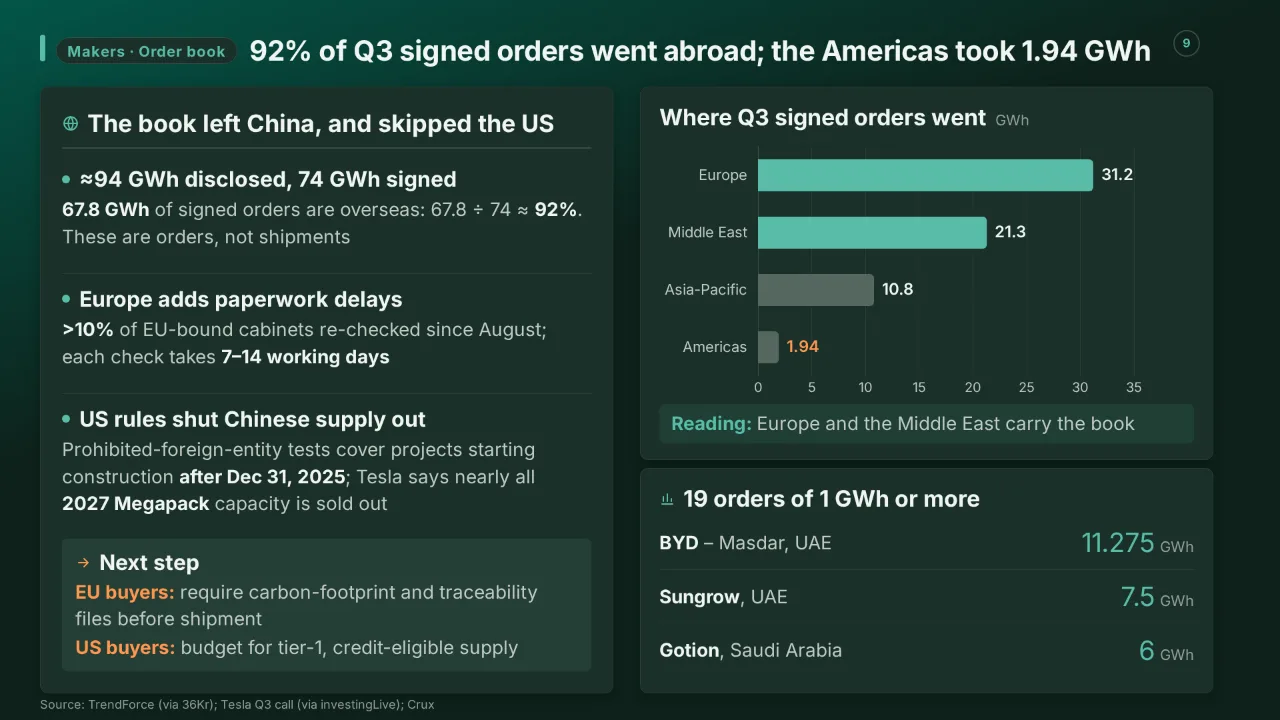
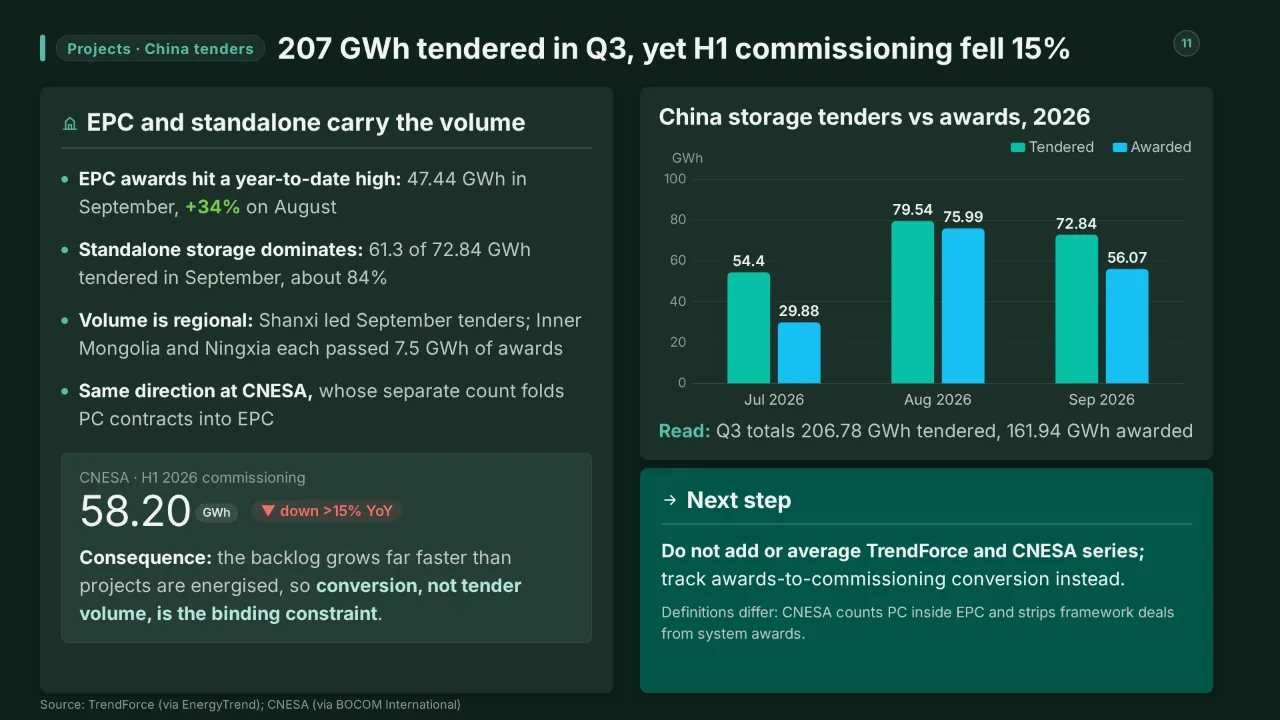
4. China builds the pipeline, but the money and the shipments go abroad. Chinese suppliers disclosed about 94 GWh of storage orders in Q3. Of the 74 GWh signed, 67.8 GWh were overseas, led by Europe (31.2 GWh) and the Middle East (21.3 GWh); the Americas took only 1.94 GWh. At home, TrendForce counted 206.78 GWh of tenders in July–September. But CNESA reports that commissioned new-type storage fell more than 15% in H1 2026, to 58.20 GWh, as returns weakened in all three segments (Chapters 5 and 7).
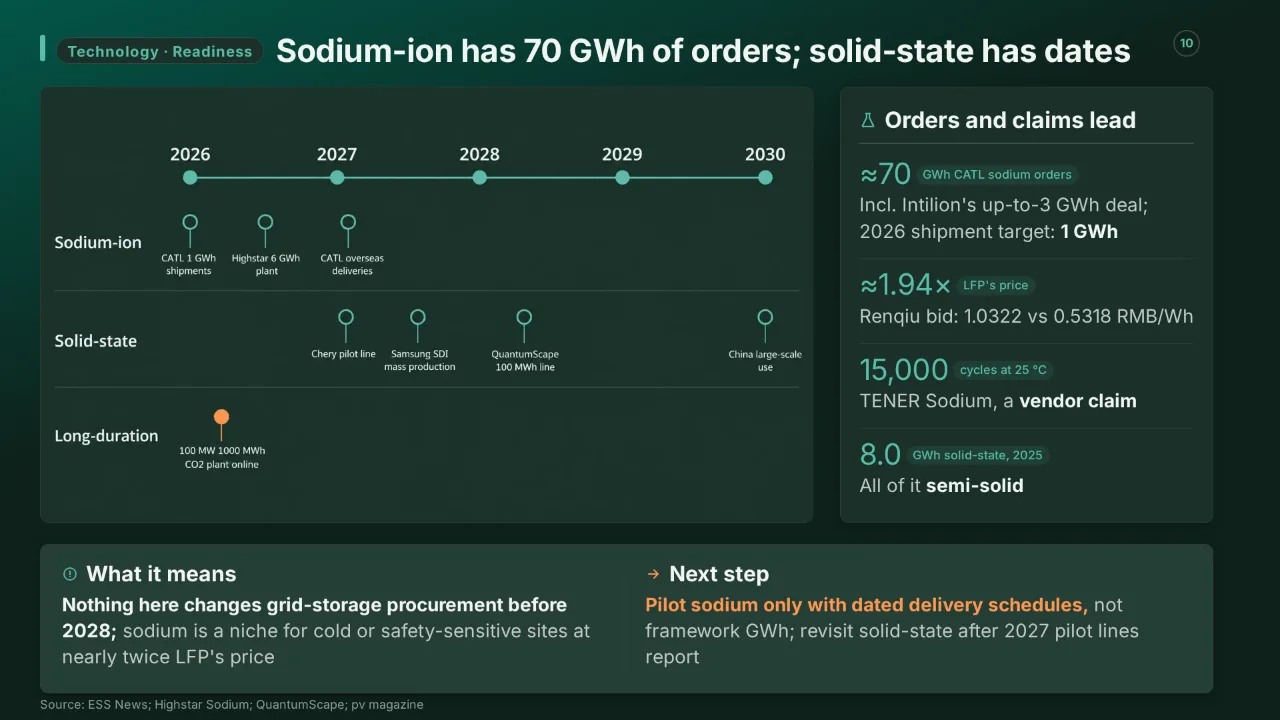
5. Sodium-ion has the orders, solid-state has the dates, and neither changes 2026 procurement. CATL has disclosed about 70 GWh of sodium-ion storage orders this year, including up to 3 GWh with Intilion announced on 9 October, against a 2026 shipment target of 1 GWh. In a September tender in Renqiu, sodium systems bid at about 1.94× the LFP price. QuantumScape's 100 MWh solid-state line, announced on 21 October, targets 2028. The fortnight's largest physical milestone was non-battery: a 100 MW/1,000 MWh compressed-CO₂ plant in Xinjiang, grid-connected since 30 September (Chapter 6).
The fortnight in one line: cost went down at the bottom of the chain, margin went down at the top, and the backlog kept growing faster than projects get energised.

1.2 Reading across the chapters
The five conclusions reinforce each other. Lithium's fall (conclusion 1) feeds award prices (conclusion 2) faster than spot cell quotes, so integrators and EPC firms absorb the squeeze first. That is exactly where CATL's margin story points: it is pushing into AC-side and integrated systems, where InfoLink's H1 ranking puts it only eighth, behind BYD, Sungrow, Huawei, Tesla and HyperStrong. Meanwhile the over-supply of commodity LFP capacity, planned at close to 2,000 GWh in China against roughly 1,026 GWh of global demand, coexists with sold-out tier-1 supply: Tesla says nearly all of its 2027 Megapack capacity is booked. Buyers therefore face two markets. Spot LFP keeps getting cheaper. Bankable, compliance-ready supply for the US and EU does not.
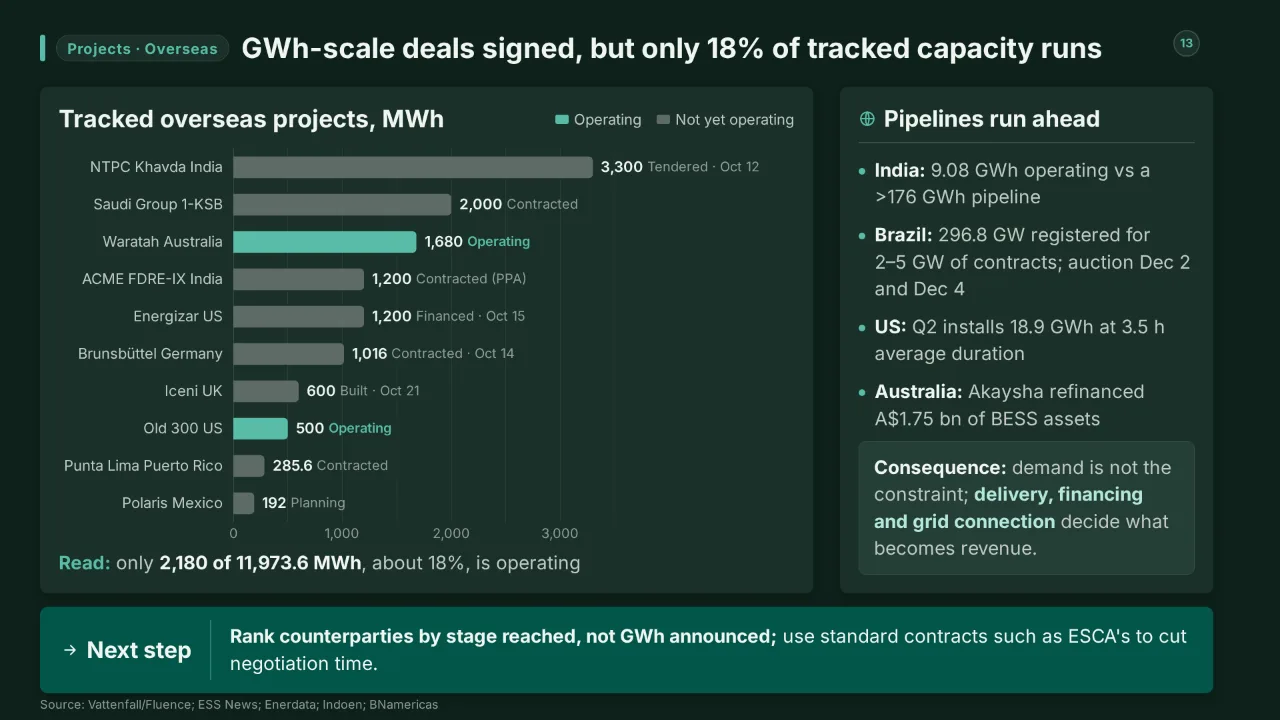
The overseas data show where risk now sits: in delivery, not in demand. Of the roughly 12 GWh of overseas projects tracked in Chapter 8, only about 18% is operating. India has 9.08 GWh in operation against a pipeline above 176 GWh. Brazil registered 296.8 GW of projects for an auction expected to contract 2–5 GW.
1.3 What moved at a glance
| Item | Value | Date | Source |
|---|---|---|---|
| GFEX lithium carbonate (LC2701) close | 104,740 yuan/t, −11.79% | 12 Oct 2026 | SunSirs |
| InfoLink lithium carbonate spot average | RMB 109,000/t, −9.2% WoW | 14 Oct 2026 | InfoLink |
| InfoLink 314 Ah LFP storage cell | RMB 0.360/Wh, −0.7% WoW | 14 Oct 2026 | InfoLink |
| InfoLink 2-hour DC-side ESS | RMB 0.49/Wh, flat | 14 Oct 2026 | InfoLink |
| TrendForce awarded 4-hour system / EPC | RMB 0.53 / 0.78 per Wh (−12% / −12%) | Sep 2026, published 16 Oct | TrendForce |
| China tenders / awards | 72.84 GWh / 56.07 GWh | Sep 2026 | TrendForce |
| CATL Q3 revenue / net profit | RMB 165.221 bn (+58.58%) / RMB 21.246 bn (+14.54%) | 20 Oct 2026 | EnergyTrend |
| Tesla Q3 storage deployed / energy revenue | 13.7 GWh (+9.6%) / US$2.88 bn (−16%) | 2 Oct / 21 Oct 2026 | Electrek |
| Chinese Q3 storage orders (signed overseas) | ~94 GWh disclosed (67.8 GWh) | Reported 10 Oct 2026 | TrendForce via 36Kr |
| CATL sodium-ion storage orders vs 2026 shipments | ~70 GWh vs 1 GWh target | As of 22 Oct 2026 | Hangjiashuo; ESS News |
| QuantumScape solid-state line | 100 MWh, production 2028 | Announced 21 Oct 2026 | QuantumScape |
| Vattenfall–Fluence Brunsbüttel | 254 MW / 1,016 MWh | Contracted 14 Oct 2026 | Vattenfall/Fluence; ESS News |
| NDRC draft spot-market rules | Comments to 18 Nov; proposed effective 1 Jan 2027 | Released 19 Oct 2026 | ESS News |
2. Lithium and storage-cell prices
The headline move of the fortnight started upstream: lithium carbonate broke to a new 2026 low, but storage-cell prices followed only slowly.
Core claim: On 12 October 2026 lithium futures fell 11.79% in one session, and InfoLink's spot average dropped 9.2% week on week to RMB 109,000/t. Mainstream 280/314 Ah storage cells slipped only 0.7% to RMB 0.360/Wh. Buyers now have leverage on new orders. Cell prices will be renegotiated over months, not repriced overnight.
All US-dollar conversions in this chapter use RMB 6.69 per US$, the rate implied by Reuters' conversion of 104,680 yuan to US$15,640.22 on 12 October. The arithmetic: RMB X/Wh × 1,000 ÷ 6.69 = US$/kWh.
2.1 Lithium carbonate: the 12 October break
Lithium was already falling before the window opened. It peaked at 209,880 yuan/t on the Guangzhou Futures Exchange (GFEX) on 13 May. Benchmark Mineral Intelligence put battery-grade carbonate (EXW China) at US$19,025/t at the end of Q3, down 20.8% quarter on quarter, according to INN's summary of Benchmark's review. The trigger in the window was trade policy. On 9 October, EU Trade Commissioner Maros Sefcovic said China had agreed to a deal that could more than halve its hybrid-car exports to the EU. The proposed cap is about 350,000 units in the first year, rising 6% a year over four years. Status: announced, effective no earlier than 1 December 2026, with implementation terms not yet disclosed.
| Date (2026) | Price / event | Source |
|---|---|---|
| 13 May | GFEX 33-month high, 209,880 yuan/t | Reuters via MINING.COM |
| End-Q3 | Benchmark carbonate EXW China US$19,025/t (−20.8% QoQ) | Benchmark via INN |
| 8 Oct | Jianxiawo mine EIA enters public notice; restart still needs approvals | InfoLink |
| 11 Oct | Qiankeng mine safety design approved in principle (~15,000 t LCE/yr) | SunSirs |
| 12 Oct | SMM spot average 115,400 yuan/t (−6,950, −5.7% d/d) | SMM |
| 12 Oct | GFEX LC2701 low 104,680, close 104,740 yuan/t (−11.79%), first close below 110,000 since Dec 2025 | SunSirs |
| 14 Oct | InfoLink spot RMB 106,000–112,000/t, average 109,000 (−9.2% WoW) | InfoLink |
| 21 Oct | InfoLink: "lithium salt prices continue to decline" (headline only in material) | InfoLink |
Futures fell more than twice as hard as spot. On 12 October SunSirs' spot assessment fell 5.8%, against futures' 11.79%. SunSirs calls this "a shift in the pricing anchor rather than a collapse" in fundamentals: new supply (Jianxiawo, Qiankeng, Zimbabwe, Brazil) mostly arrives in 2027 or later. SMM's intraday low of 105,320 differs from the 104,680 cited by Reuters and SunSirs because it was quoted earlier in the session. Forward views (all estimates): InfoLink sees a near-term range of RMB 100,000–120,000/t. SMM puts cost support near 100,000 yuan/t. Goldman Sachs forecasts an average of about 100,000 yuan/t in 2027 and 84,000 in 2028, according to Securities China via SunSirs. At 6.69, InfoLink's 14 October average equals about US$16,290/t (109,000 ÷ 6.69).
2.2 Weekly and monthly cell prices
InfoLink's weekly China transaction series is the cleanest domestic benchmark. The 14 October figures come from InfoLink directly. The two earlier columns are InfoLink figures as cited by LJY Energy, a supplier site.
Table 2-1. InfoLink LFP storage-cell average prices, China (RMB/Wh)
| Cell size | 9 Sep 2026 | ~9 Oct 2026 | 14 Oct 2026 | WoW at 14 Oct | 14 Oct in US$/kWh | Publisher |
|---|---|---|---|---|---|---|
| 100 Ah | 0.440 | 0.428 | 0.420 (range 0.390–0.450) | −1.8% | 62.8 | InfoLink |
| 280 Ah | 0.365 | 0.363 | 0.360 (range 0.330–0.390) | −0.7% | 53.8 | InfoLink |
| 314 Ah | 0.365 | 0.363 | 0.360 (range 0.330–0.390) | −0.7% | 53.8 | InfoLink |
Negup Energy dates the "~9 Oct" reading to 8 October. InfoLink's own article list shows issues on 30 September, 14 October and 21 October. The 21 October issue says only that cell prices "edge lower"; its numbers are not in the material.
Benchmark's Q3 Cell Price Review, released on 9 October, tracks a single 314 Ah grade across three trade bases:
Table 2-2. Benchmark LFP prismatic 314 Ah cell prices (US$/kWh)
| Basis | Jul 2026 | Aug 2026 | Sep 2026 | Publisher |
|---|---|---|---|---|
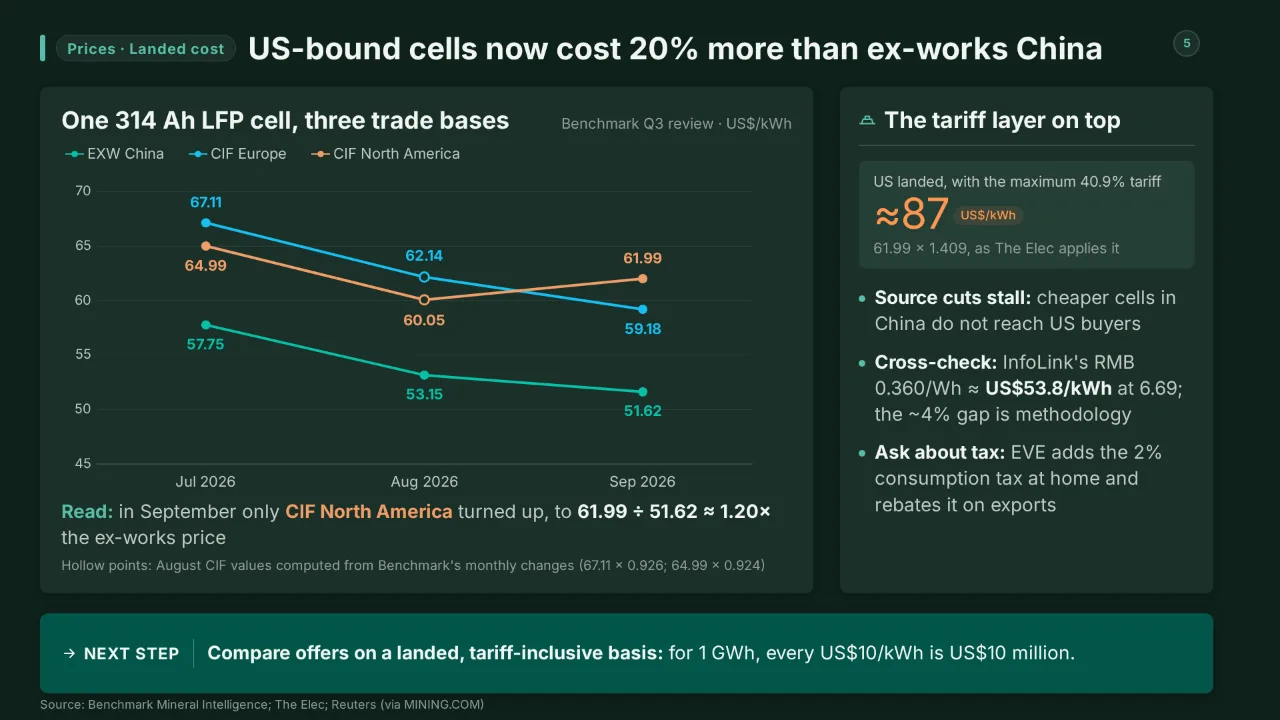
| EXW China | 57.75 | 53.15 | 51.62 | Benchmark |
| CIF Europe | 67.11 | 62.14* | 59.18 | Benchmark |
| CIF North America | 64.99 | 60.05* | 61.99 | Benchmark |
*Computed from Benchmark's stated monthly changes: 67.11 × (1 − 7.4%) and 64.99 × (1 − 7.6%). A cross-check backwards from September (61.99 ÷ 1.033 = 60.01) agrees.
The two series broadly agree. InfoLink's 0.360 RMB/Wh converts to US$53.8/kWh, close to Benchmark's September EXW US$51.62. Neither page states its VAT basis, so treat the ~4% gap as a difference in methodology, not a price signal. Other quotes are secondary only. According to Negup Energy, SMM put the average prismatic LFP cell at RMB 0.420/Wh in mid-October, with CATL's 280 Ah and 314 Ah quotes at RMB 0.470 and 0.403/Wh.
2.3 Why cells fall slower than lithium
From early October to 14 October, carbonate fell about 9.2% while 314 Ah cells fell under 1% (0.363 → 0.360). Had cells fallen by the same percentage, the cut would have been 0.363 × 9.2% ≈ RMB 0.033/Wh, roughly ten times the actual move. Four mechanisms explain the lag:
- Locked orders. Utility-scale deliveries continue at scale, and "prices and delivery schedules have already been locked in for some orders." Only 100 Ah cells, where some makers built up inventory, are falling noticeably.
- Transmission lag. Benchmark's July spike reflected June's lithium prices even as spot was already falling. Benchmark expects September's carbonate drop to pass through into October–November quotes.
- The tax floor. A 2% consumption tax on lithium-ion batteries has been in effect since 1 September 2026 and is announced to rise to 4% on 1 September 2027. SMM analyst Li Yisha estimates it adds about RMB 0.007/Wh at a RMB 0.36/Wh cell price (≈US$1.05/kWh), or about RMB 7 million per GWh. CATL raised its 314 Ah cell from RMB 0.414 to 0.423/Wh in September.
- Tight capacity. Utilisation was above 90% in September. China's pause on new cell-capacity approvals is in effect, with a review due by year-end.
Lithium is a larger share of cost in LFP than in NCM cells, so pass-through will come. It arrives contract by contract.
2.4 What it means for buyers
- Reopen quotes now, starting with small formats. InfoLink reports customers "proactively requesting updated quotes". Expect pressure to continue on 100 Ah and only "minor adjustments" on 280/314 Ah in the near term.
- Index the cell price to lithium. With InfoLink's estimated RMB 100,000–120,000/t corridor, a lithium-linked clause captures further declines without betting on timing.
- Ask whether quotes include tax. Check how the 2% consumption tax is treated. EVE added it to domestic prices from 1 September, with rebates for export products.
- Price landed, not EXW, in the US. In September the CIF North America price ran about 20% above EXW China. The Elec applies the maximum 40.9% US import tariff it cites to the US$61.99 CIF price, giving ≈US$87/kWh (61.99 × 1.409). For a 1 GWh project, every US$10/kWh adds US$10 million.
Cell costs feed into system and tender prices, which Chapter 3 covers.
3. System, EPC and tender prices
Chapter 2 showed lithium and cell prices sliding. This chapter follows that move up the value chain, through DC blocks, integrated systems and EPC contracts, and finds that each layer moves more slowly than the one below it.
3.1 System price snapshot: cells edge down, systems hold
InfoLink's weekly China spot assessment dated 2026-10-14 reports electrochemical ESS transaction prices as "stable overall", while LFP storage cells fell another 0.7% week on week. Its next update, dated 2026-10-21, kept the same message in its headline ("cell prices edge lower and ESS prices hold steady"). The table below is a price ladder taken entirely from the 2026-10-14 InfoLink release. US$ values are our conversion at RMB 6.69/US$, which Strategic Revenue Insights (SRI) gives as the mid-October 2026 rate. Formula: RMB/Wh × 1,000 ÷ 6.69 = US$/kWh.
| Layer (China, InfoLink, week to 2026-10-14) | Range, RMB/Wh | Average, RMB/Wh | WoW | ≈ US$/kWh (avg ÷ 6.69) | Source |
|---|---|---|---|---|---|
| 314 Ah LFP storage cell | 0.330–0.390 | 0.360 | −0.7% | 53.8 | InfoLink |
| 2-hour DC-side liquid-cooled container | 0.45–0.53 | 0.49 | flat | 73.2 | InfoLink |
| 2-hour AC-side liquid-cooled container | 0.52–0.63 | 0.58 | steady (headline) | 86.7 | InfoLink |
| 1-hour AC-side liquid-cooled container | 0.81–0.87 | 0.84 | flat | 125.6 | InfoLink |
On this ladder the 2-hour DC block costs about 1.36× the cell (0.49 ÷ 0.36), and moving to AC-side adds another 18% (0.58 ÷ 0.49). InfoLink explains why the system layer is sticky. Large utility-scale orders already have locked prices and delivery schedules, so 280 Ah and 314 Ah cells "have yet to see significant price declines". Lower lithium costs are only "gradually extending" into new quotations.
Lithium carbonate fell 9.2% in the week to 2026-10-14, but China's 2-hour DC-side system price did not move from RMB 0.49/Wh.
3.2 Tender prices: September reverses the H1 rebound
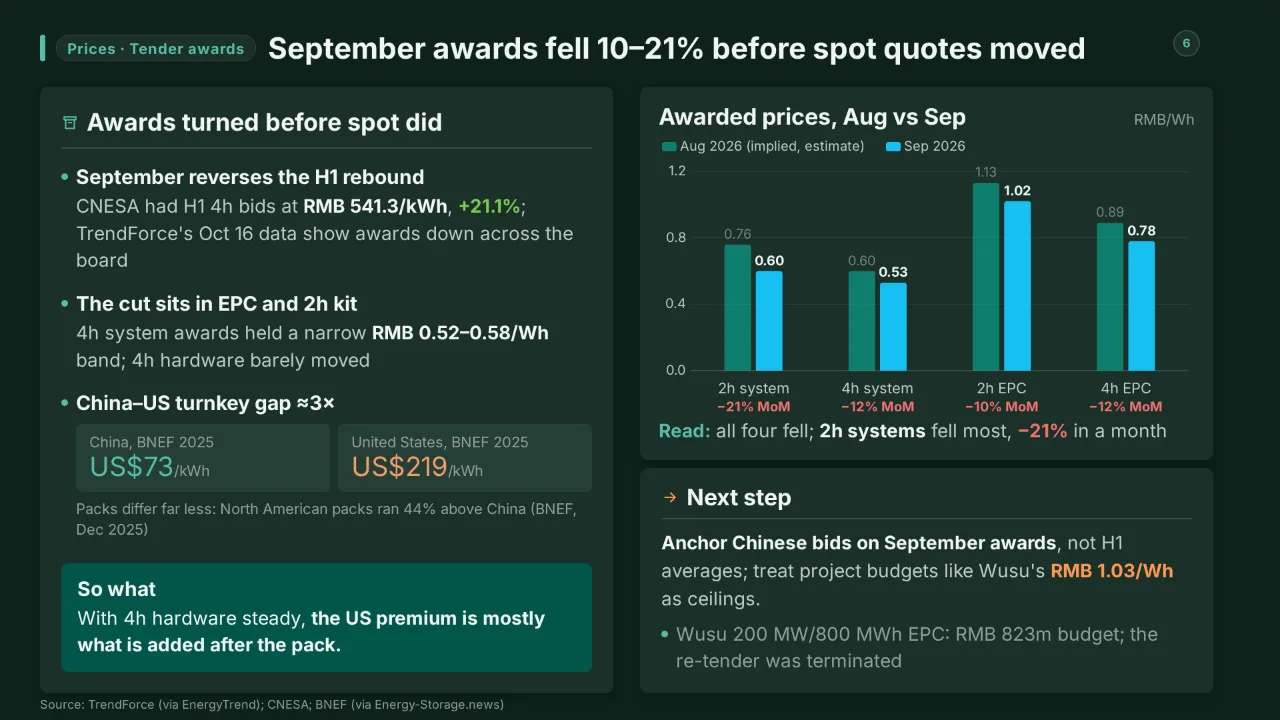
Tender awards show the turn earlier than the weekly spot quotes do. TrendForce's China tender database for September 2026 (EnergyTrend, published 2026-10-16) reports that "overall awarded energy storage prices trended down", with notable drops for both systems and EPC. The implied August values below are back-calculated from TrendForce's own month-on-month changes (formula: September ÷ (1 − MoM decline)). They are our estimates, not published figures.
| TrendForce awarded price (RMB/Wh) | Aug 2026 (implied, estimate) | Sep 2026 weighted avg | MoM | Sep range | ≈ US$/kWh Sep (÷ 6.69) | Source |
|---|---|---|---|---|---|---|
| 2-hour system | 0.76 | 0.60 | −21% | 0.53–0.86 | 89.7 | TrendForce |
| 4-hour system | 0.60 | 0.53 | −12% | 0.52–0.58 | 79.2 | TrendForce |
| 2-hour EPC | 1.13 | 1.02 | −10% | 0.68–1.50 | 152.5 | TrendForce |
| 4-hour EPC | 0.89 | 0.78 | −12% | 0.57–1.04 | 116.6 | TrendForce |
This reverses the first half of the year. CNESA's H1 2026 tender review (published 2026-07-15) found winning bids up across the board. 2-hour ESS averaged RMB 602.1/kWh (+8.8% YoY, range RMB 489.0–836.0) and 4-hour ESS averaged RMB 541.3/kWh (+21.1% YoY, range RMB 420.0–781.8). CNESA's forum presentation on 2026-08-27, as reported by ESS News and Energy-Storage.news, gave the 2-hour figure as RMB 599.3/kWh (+8.3%). We follow the CNESA article itself. EPC prices for H1 come only from a secondary source. According to SRI, CNESA put 4-hour EPC at RMB 958.5/kWh (+8.2%, range RMB 645–1,377.5) and 2-hour EPC at RMB 1,040.4/kWh (+3.2%).
Comparing TrendForce's September averages with CNESA's H1 averages is only indicative, because the two databases define their samples differently (see Chapter 7). On that basis, 4-hour system prices are about 2% lower (530 ÷ 541.3 − 1). 4-hour EPC prices are about 19% lower (780 ÷ 958.5 − 1). Most of the recent decline is therefore in EPC margins and in 2-hour equipment, not in 4-hour hardware, whose September awards sat in a narrow RMB 0.52–0.58/Wh band.
Individual projects fit the same picture. According to DBM (cementchina.net, 2026-10-21), the 200 MW/800 MWh Wusu independent storage EPC in Xinjiang carried a budget of RMB 823 million. That is RMB 1.03/Wh (823m ÷ 800,000 kWh). The January 2026 first-ranked bid was about RMB 750 million (≈RMB 0.94/Wh). The re-tender was terminated before its planned 2026-10-21 bid opening because of "major changes" to the project.
3.3 The China–US gap, with the arithmetic
| Benchmark | China | United States | Ratio | Gap | Source |
|---|---|---|---|---|---|
| Turnkey BESS, 2025 avg (BNEF survey) | US$73/kWh | US$219/kWh | 3.0× | US$146/kWh | BNEF (via Energy-Storage.news) |
| 4-hour, H1 2026 EPC vs EIA AEO 2026 | US$143/kWh | US$380/kWh | 2.7× | US$237/kWh | SRI, citing CNESA and EIA |
| 4-hour, Sep 2026 EPC vs EIA AEO 2026 (estimate) | US$116.6/kWh | US$380/kWh | 3.3× | US$263/kWh | Our calculation from |
SRI's US figure starts from EIA's overnight cost of US$1,521/kW for 4-hour lithium-ion. US$1,521 ÷ 4 h ≈ US$380/kWh, or US$152.1m for 100 MW/400 MWh. The Chinese side is RMB 958.5 × 400,000 kWh = RMB 383.4m, which at 6.69 is US$57.3m (US$143/kWh). SRI itself warns that the EIA number is a "modelling assumption … not a price anyone paid", so the ratio is an order of magnitude. Our September row applies the same formula to TrendForce's RMB 0.78/Wh. It is an estimate that mixes data sources. On SRI's own lithium sensitivity estimate (about RMB 4.6/kWh per RMB 10,000/t of lithium carbonate), the whole May-to-October lithium swing explains only about 3% of the gap.
Pack prices look different from system prices. BNEF's December 2025 survey put stationary-storage packs at US$70/kWh (−45%), the cheapest segment for the first time. North American packs were 44% above China's US$84/kWh. The pack gap is far narrower than the turnkey gap, so most of the US premium comes from what is added after the pack. Wood Mackenzie (via pv magazine, 2026-10-12) reports that four-hour storage LCOE is below open-cycle gas in all 43 modelled markets. It flags tariffs and FEOC rules as near-term US headwinds.
3.4 Implications
- Buyers in China: award prices fell before spot prices did. The September 4-hour EPC average of RMB 0.78/Wh is a better negotiating anchor than H1 averages. Expect weekly system quotes to stay sticky while locked orders deliver.
- Overseas buyers: Ember puts all-in 4-hour capex outside China and the US at US$125/kWh (US$75 equipment + US$50 installation and grid connection, as of October 2025). Tariffs or local-content rules can add US$100/kWh or more. Hardware cuts in China reach these buyers only partly.
- Forecasts (estimates): BNEF expects 4-hour turnkey systems to reach US$41/kWh in China, US$101/kWh in Europe and US$108/kWh in the US (with Chinese batteries) by 2035. For 2026 it expects the average pack price to fall about 3%, to just under US$105/kWh.
4. Manufacturers — Q3 results and shipments
Chapter 3 showed system and tender prices near their lows. This chapter looks at how that shows up in manufacturers' Q3 2026 accounts. The answer is that volumes still rise fast, but each GWh earns less than a year ago.
4.1 Results at a glance
| Company | Metric (period) | Value | YoY | Released | Basis | Source |
|---|---|---|---|---|---|---|
| CATL | Revenue (Q3 2026) | RMB 165.221 bn | +58.58% | 2026-10-20 | Company-reported, unaudited | EnergyTrend |
| CATL | Net profit attributable (Q3 2026) | RMB 21.246 bn | +14.54% | 2026-10-20 | Company-reported, unaudited | EnergyTrend |
| CATL | Revenue (9M 2026) | RMB 442.137 bn | +56.19% | 2026-10-20 | Company-reported, unaudited | EnergyTrend; Globe and Mail |
| CATL | Storage battery sales (Q3 2026) | >65 GWh | n/a | 2026-10-22 | Media-derived estimate | EnergyTrend |
| Tesla | Energy generation & storage revenue (Q3 2026) | $2.88 bn | −16% | 2026-10-21 | Company-reported | Electrek; Stock Titan |
| Tesla | Storage deployed (Q3 2026) | 13.7 GWh | +9.6% | 2026-10-02 | Company-reported | Electrek; Venture Atlas |
| Tianqi Lithium | Net profit attributable (9M 2026) | RMB 5.1–6.0 bn | +2,734.97% to +3,235.26% | 2026-10-20 | Company forecast, preliminary | EnergyTrend |
| Highpower Technology | Revenue / net profit (Q3 2026) | RMB 2.07 bn / RMB 114 m | +27.08% / +45.53% | 2026-10-21 | Company-reported | EnergyTrend |
CATL's Q3 revenue rose 58.58% while its net profit rose only 14.54%. Tesla deployed 9.6% more storage but booked 16% less energy revenue. Volume growth has stopped turning into profit growth.
4.2 CATL: storage volume up, margin at a multi-year low
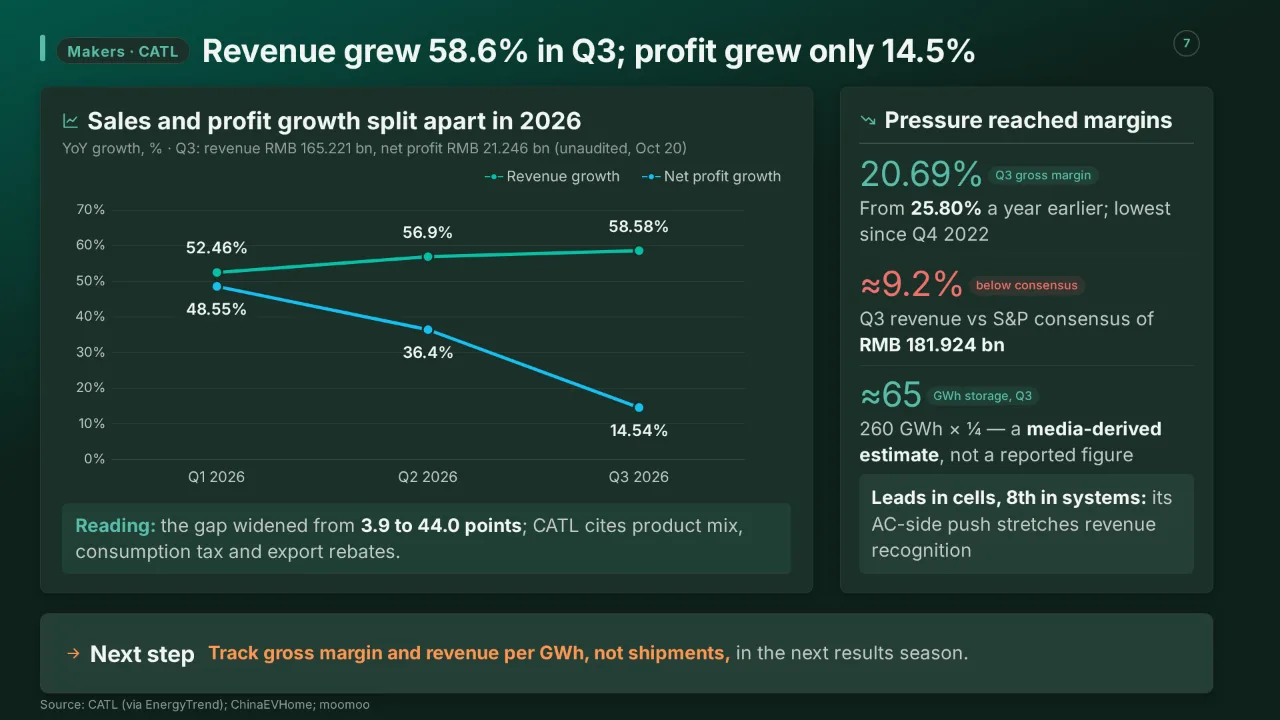
CATL published its Q3 2026 report on the evening of 2026-10-20. Net profit excluding non-recurring items was RMB 18.862 bn, up 14.86%. CATL said the gap between revenue and profit growth came from "product structure, consumption taxes, export tax rebates" and related factors. That gap has grown wider every quarter this year:
| CATL, 2026 | Q1 | Q2 | Q3 |
|---|---|---|---|
| Revenue growth, YoY | 52.46% | 56.9% | 58.58% |
| Net profit attributable growth, YoY | 48.55% | 36.4% | 14.54% |
Source: ChinaEVHome.
Q3 gross margin was 20.69%, down from 25.80% a year earlier and 23.15% in Q2, and the lowest since Q4 2022. Net margin fell to 12.86%, and net profit was 5.77% lower than in Q2. S&P consensus revenue (two analysts, via moomoo) was RMB 181.924 bn. Reported revenue came in (165.221 − 181.924) / 181.924 ≈ 9.2% below that figure. This is a comparison against an analyst estimate. Nine-month operating cash flow fell 23.6% to RMB 61.625 bn.
How big storage is. CATL does not report storage revenue separately. According to EnergyTrend, CATL disclosed combined power and storage battery sales of more than 260 GWh in Q3, with storage making up "roughly one-fourth". That gives a media-derived estimate of 260 GWh × ¼ ≈ 65 GWh of Q3 storage sales. ChinaEVHome reads the 260 GWh as a first-three-quarters total and puts storage growth at "nearly 60%". We use the quarterly reading. According to Meticulous Research, CATL sold 661 GWh in 2025, or about 165 GWh a quarter, so a nine-month total of 260 GWh would mean volumes fell while revenue rose 56%. If the 65 GWh estimate is right, Q3 storage alone equals about 54% of CATL's 121 GWh of storage-cell sales for all of 2025 (company filing, via BSLBATT): 65 / 121 ≈ 0.54.
CATL also said its storage business is extending from cells and DC blocks to AC-side equipment and fully integrated systems. It said this lengthens delivery and revenue-recognition cycles. As a result, storage revenue may trail shipments for several quarters.
4.3 Tesla Energy: more GWh, less revenue
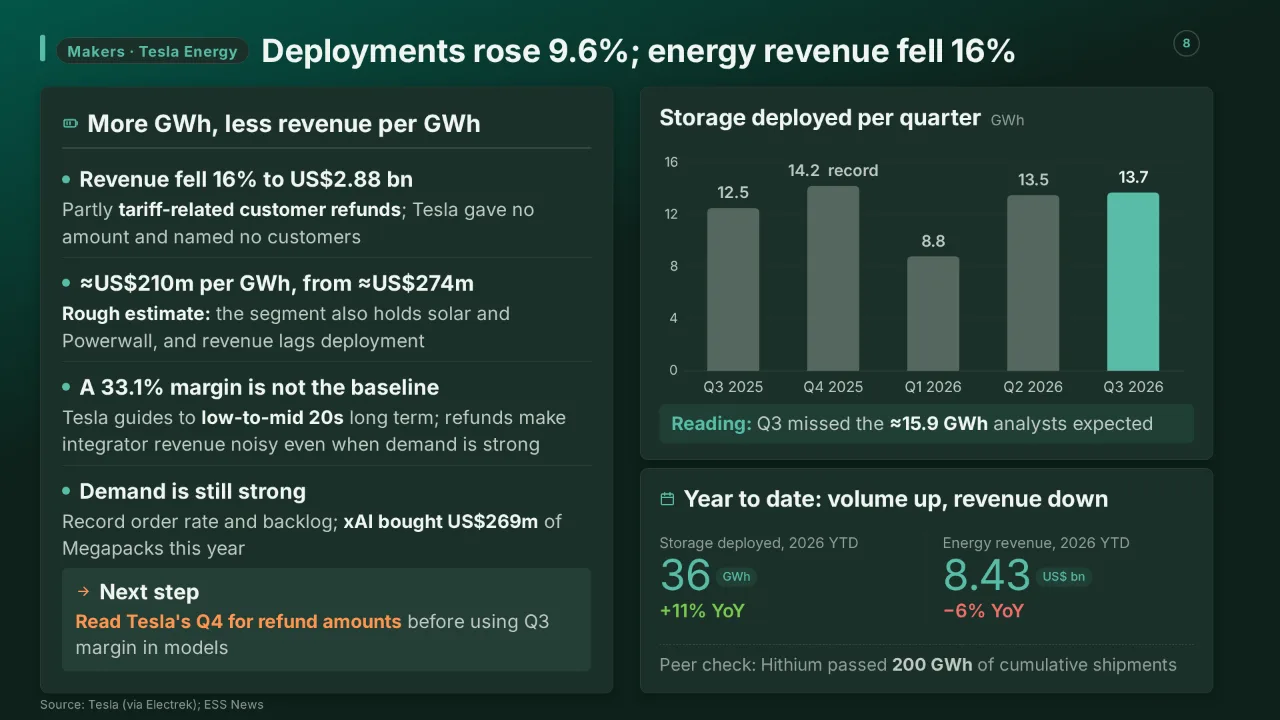
Tesla reported Q3 2026 results on 2026-10-21. Electrek's series below is built from Tesla's reported results and is the cleanest one to chart:
| Quarter | Storage deployed | Energy revenue | Energy gross margin |
|---|---|---|---|
| Q3 2025 | 12.5 GWh | $3.42 bn | 31.4% |
| Q4 2025 | 14.2 GWh | $3.84 bn | 28.6% |
| Q1 2026 | 8.8 GWh | $2.41 bn | 39.5% |
| Q2 2026 | 13.5 GWh | $3.14 bn | 20.4% |
| Q3 2026 | 13.7 GWh | $2.88 bn | 33.1% |
Source: Electrek.
The series adds up. Year-to-date deployments are 8.8 + 13.5 + 13.7 = 36.0 GWh (+11%), and year-to-date energy revenue is $2.41 + $3.14 + $2.88 = $8.43 bn (−6%). Q3 deployments missed the roughly 15.9 GWh analysts expected and stayed below the Q4 2025 record. Revenue was about (2.88 − 3.76) / 3.76 ≈ 23% below Zacks' $3.76 bn estimate. Revenue per GWh fell by a similar amount. Q3 2026 works out to $2.88 bn / 13.7 GWh ≈ $210 m per GWh, against $3.42 bn / 12.5 GWh ≈ $274 m per GWh a year earlier. Treat this as a rough estimate: the segment also includes solar and Powerwall, and revenue recognition lags deployment.
Tesla's letter says the revenue decline was "partially" due to tariff-related customer refunds. It gives no amount and names no customers. Electrek suggests the refunds follow the Supreme Court's February 2026 ruling that struck down the IEEPA tariffs, but calls this a guess. According to shattered.io, Tesla's Q2 filing had warned that the ruling could reduce revenue on storage contracts that pass tariffs through to customers. Status: the refunds were booked in Q3 2026, and the amount is still undisclosed. Energy gross margin recovered to 33.1%, but energy gross profit fell to $954 m from $1.07 bn. Tesla guides to low-to-mid 20% energy margins over the long term, so Q3 should not be read as a new baseline.
On demand, Tesla reports its "highest-ever order rate and backlog", driven by data centres. xAI bought $269 m of Megapacks this year, after $430 m in 2025. The material contains no quantified 2027 deployment guidance. Megafactory Texas and the Nevada cell line are covered as capacity in Chapter 5.
4.4 Rankings and other makers
InfoLink's H1 2026 storage-cell ranking was published on 2026-08-11. It gives ranks, not company volumes:
| Rank | Global | Utility-scale | Outside China |
|---|---|---|---|
| 1 | CATL | CATL | CATL |
| 2 | Hithium | Hithium | EVE Energy |
| 3 | EVE Energy | BYD | BYD |
| 4 | BYD | CALB | Hithium |
| 5 | CALB | EVE Energy | Great Power |
Source: InfoLink.
Global cell shipments were 467.84 GWh (+94.76%). Of that, 402.36 GWh was utility-scale and 65.48 GWh small-scale, and 248.73 GWh (≈53.2%) went to markets outside China. The market is becoming less concentrated. The top-10 share (CR10) went from 91.2% in H1 2025 to 88.8% for full-year 2025, 85.2% in Q1 2026 and 82.3% in H1 2026 (InfoLink via pv magazine).
The system-integrator ranking looks different. InfoLink's H1 2026 system ranking, relayed by SANSE on 2026-10-15, puts BYD, Sungrow, Huawei, Tesla and HyperStrong in the top five on 303.40 GWh, with CATL eighth. This gap explains CATL's push into AC-side equipment (§4.2).
Other items in the window:
- Hithium passed 200 GWh of cumulative shipments, and the second 100 GWh took about 14 months (ESS News, 2026-10-16). According to distributor Xiho, its first ∞Power 6.25 MWh containers shipped from Heze in September 2026.
- Tianqi Lithium: BigGo derived Q3 profit as RMB 5.1–6.0 bn minus H1's RMB 4.242 bn, giving RMB 0.858–1.758 bn. That is 25%–64% below Q2's RMB 2.366 bn, so upstream profits have peaked (lithium prices are covered in Chapter 2).
- Highpower calls storage its "new growth curve", with both shipments and profitability rising.
- Sungrow, EVE, BYD: the reviewed material contained no Q3 figures for these companies as of 2026-10-23. Sungrow, Sunwoda and others launched a RMB 1 bn storage fund on 2026-10-21. EVE's 206 GWh framework with Fluence belongs to the order book (Chapter 5).
Conclusion: the leaders are still winning volume, but price pressure has moved from cell quotes into reported margins. The makers in the best position sell full systems and can explain their revenue adjustments.
5. Capacity, orders and supply chain
Chapter 4 covered what the manufacturers earned; this chapter looks at where their volume is going, which factories are being built to serve it, and why a market with nearly twice the capacity it needs can still be short of the cells buyers actually want.
5.1 The Q3 order book: 94 GWh, almost all of it overseas
According to TrendForce data reported by 36Kr on 2026-10-10, Chinese storage companies disclosed about 94 GWh of ESS orders in Q3 2026. About 74 GWh of that was signed, and 67.8 GWh of the signed orders were overseas. The source puts the overseas share at 93%. Our own check gives 67.8 / 74 ≈ 92%, so read the figure as "just over 90%". These are disclosed orders (framework plus signed contracts), not shipments or installations, and they come from a secondary outlet that cites TrendForce.
The book is concentrated in a few very large contracts. 19 orders of 1 GWh or more added up to 62.2 GWh, or 84% of signed volume (62.2 / 74 ≈ 84%). The largest were BYD's 11.275 GWh with Masdar in the UAE, Sungrow's 7.5 GWh in the UAE and Gotion's 6 GWh in Saudi Arabia. Destinations are just as concentrated (chart-ready, one source):
| Destination (Q3 2026 signed orders) | Volume (GWh) | Share of signed orders | Source |
|---|---|---|---|
| Europe | 31.2 | 42% | TrendForce via 36Kr |
| Middle East | 21.3 | 28.7% | TrendForce via 36Kr |
| Asia-Pacific | ≈10.8 (calc.: 14.6% × 74) | 14.6% | TrendForce via 36Kr |
| Americas | 1.94 | ≈2.6% (calc.: 1.94 / 74) | TrendForce via 36Kr |
Two regions, Europe and the Middle East, account for more than 70% of the signed overseas book. The Americas account for under 2 GWh.
Being concentrated in Europe also brings compliance friction. In early September 2026, a container of Chinese-made storage systems was held at Rotterdam for more than ten days because its carbon-footprint and traceability documents did not meet EU requirements. Industry estimates say that more than 10% of storage cabinets arriving since August 2026 have triggered document re-checks, which take 7–14 working days or longer. An EU Battery Regulation digital battery passport requirement, dated 18 February, is still upcoming. CATL's sodium-ion deal with Intilion for up to 3 GWh is another overseas order, and Chapter 6 covers it.
5.2 Capacity moves: sold out at the top
The capacity news in the window points the same way. Tier-1 suppliers are fully booked and are adding factories close to their customers.
| Company | Site | Capacity | Stage (vs 2026-10-23) | Source |
|---|---|---|---|---|
| Tesla | Megafactory Texas (Brookshire) | 50 GWh Megapack 3 | Production started Q3 2026 | Basenor; Manufacturing Digital |
| Tesla | Lathrop, CA / Shanghai | 40 GWh / 20 GWh | Operating (since 2022 / Feb 2025) | Basenor; Manufacturing Digital |
| Hithium | Heze, Shandong | 30 GWh cells + 20 GWh systems (planned) | Mass production since Aug 2026; first overseas shipments Sep 2026 | ESS News |
| Hithium | Chongqing | 56 GWh cells (planned) | Ramping long-duration lines | ESS News |
| Hithium | Navarre, Spain | ~€400m cell and system plant | Agreed; production targeted for 2027 | ESS News |
| NeoVolta | Pendergrass, Georgia | 2 GWh, expandable to 8 GWh by 2028 | Commissioning; ramp planned for Q4 2026 | Environment+Energy Leader |
On Tesla's Q3 call (2026-10-21, US time), management said that nearly all 2027 Megapack capacity is sold out and that production is ramping as fast as possible. Basenor adds up the three Megafactories to about 110 GWh of nameplate capacity (40 + 20 + 50). It cites Tesla's Q3 deployments of 13.7 GWh, and Electrek's report of more than $9 billion (about 43 GWh) of Megapack orders in six weeks. It also reports that LG Energy Solution will supply LFP cells from Michigan under a $4.3 billion agreement that takes effect in 2027. A rough utilisation check: 13.7 × 4 ≈ 55 GWh a year against 110 GWh nameplate, or about 50%. This is an estimate, and it is low because Brookshire has only just started production. Musk's post that Tesla has "a shot at exceeding 10GW next year" does not state its unit, so it is not treated as guidance here.
Hithium said on 2026-10-15 that cumulative shipments had passed 200 GWh. CEO Jason Wang said its long-duration orders "now extend through the end of 2027", although the volume was not disclosed. Its US site in Mesquite, Texas, assembles 10 GWh of modules and systems a year but does not make cells. The same split between cells and assembly appears at NeoVolta, which has agreed to buy 9 GWh of US-made LFP cells from SK On for delivery in 2027–2031.
5.3 US supply chain and restrictions
US capacity is growing, but most of it is not cell capacity for storage. The Clean Investment Monitor (CIM) report of 2026-10-15 finds that domestic battery cell and module capacity in Q3 2026 has roughly doubled from Q1 2025, and that batteries are the US supply chain closest to meeting projected demand. In Q1 2025, CIM counted about 202 GWh of operating cell capacity, so doubling implies something on the order of 400 GWh (estimate, mostly EV-focused). SEIA's October 2026 dashboard excludes EV-only plants and counts only 62.4 GWh of operational battery cell capacity. SEIA expects that capacity to cover the whole US market by the end of 2027. On the demand side, the EIA (via Legal 500) projects 24 GW of utility-scale battery additions in 2026, up from 15 GW in 2025.
| Restriction | Effective date | Status on 2026-10-23 | Source |
|---|---|---|---|
| OBBB signed; tax credits tied to supply-chain compliance | 2025-07-04 | In effect | Crux; Legal 500 |
| Prohibited-foreign-entity (PFE) tests (ownership, effective control, material assistance) for §48E/§45Y | Construction beginning after 2025-12-31 | In effect | Crux |
| FEOC limits on the §45X manufacturing credit; material-assistance cost ratios | Phasing in "over the next few years" | Partly in effect | CIM |
| DOE FEOC guidance (25% control threshold, §40207 grants) | May 2024 | In effect | DOE |
| Import tariffs (equipment costs up >50% since Jan 2025) | From Jan 2025 | In effect | Legal 500 |
Storage is not subject to the July 4, 2026 start-of-construction cutoff that applies to wind and solar. Under the PFE tests, however, Chinese content now decides whether a project qualifies for credits, and is no longer only a question of price. DigiTimes reported on 2026-10-19 that major Chinese storage suppliers have "reportedly" withdrawn almost entirely from US operations in 2026. The Americas' 1.94 GWh share of Chinese Q3 orders fits that picture. The material for this chapter has no NDAA-specific battery provisions, so they are not assessed here.
5.4 What over-capacity means for prices
Planned Chinese storage-cell capacity for 2026 is close to 2,000 GWh, against global demand of 1,026 GWh, or about 1.95×. Small and mid-sized cell makers run at below 20% utilisation. Zenergy's marketing chief still says leading cells are "in extremely short supply". Rhodium's Clean Investment Monitor shows the same pattern from the investment side. Battery manufacturing investment fell 13% in Q1 2026 and 6% in Q2, because existing capacity is well above demand and is squeezing prices and margins. Meanwhile, critical-mineral investment has risen 50% from its mid-2025 low, with the largest lithium announcements in Argentina, France, China and the US.
The market is effectively split in two. Commodity LFP capacity has a large surplus, which keeps cell quotes falling (see Chapter 2). Bankable tier-1 supply has its own pricing power. Tesla's 2027 book and Hithium's long-duration orders are both full, and Tesla expects ASP and margins to rise. Buyers who need US tax-credit eligibility or EU compliance documents should expect to pay the tier-1 price rather than the spot price.
6. Technology — sodium-ion, solid-state and beyond lithium
Chapter 5 tracked lithium-ion capacity; this chapter asks which alternative technologies moved toward the grid between 9 and 22 October 2026, and how far each still has to go.
Core thesis: sodium-ion is the only post-LFP chemistry with GWh-scale storage orders in 2026, but CATL's sodium orders (about 70 GWh) run far ahead of its own 1 GWh shipment target for the year. Solid-state stays a 2027–2030 story of pilot lines and dated targets, while the fortnight's biggest physical milestone was a non-battery plant: a 100 MW/1,000 MWh compressed-CO₂ store.
6.1 Sodium-ion: orders far ahead of deliveries
The window's headline deal came on 9 October 2026, when Intilion CEO Hubertus Jakobi announced on LinkedIn an agreement with CATL to develop up to 3 GWh of sodium-ion BESS projects in Germany, Austria and Switzerland over five years. ESS News stresses that this is a development target, not confirmed deliveries: no projects, contract values or delivery dates have been disclosed. It follows CATL's 5 GWh plan with Alfen (July) and a three-year, 60 GWh sodium-ion agreement with HyperStrong. By an incomplete count from Hangjiashuo Energy Storage, CATL has disclosed 18 storage orders totalling 96.96 GWh since the start of 2026, of which 70 GWh (about 72%) are sodium-ion. The three named deals alone sum to 60 + 5 + 3 = 68 GWh.
Deliveries are a different scale. CATL expects sodium-ion storage shipments of 1 GWh in 2026, with international deliveries scheduled to begin in June 2027. According to Battery-Tech Network, CATL has added 40 GWh a year of sodium capacity at Fuding, but no completed storage delivery had been independently reported by early October. The sodium order book is thus roughly 70 GWh ÷ 1 GWh ≈ 70 times the 2026 shipment target, though spread over three- to five-year frameworks.
The performance case rests on vendor claims. CATL's published TENER Sodium specifications list 15,000 cycles at 25 °C, more than 10,000 cycles at 45 °C and over 92% capacity retention at −20 °C; the system, unveiled in Munich in June 2026, offers more than 30 MWh per block and 1–8 hour durations. Jakobi also claimed round-trip efficiency above 96.5%. Price is the obstacle. According to Battery-Tech Network, citing CNESA, sodium-ion systems in a September 100 MW/400 MWh tender in Renqiu, Hebei averaged 1.0322 yuan/Wh (about US$153/kWh) against 0.5318 yuan/Wh (about US$79/kWh) for LFP. The ratio is 1.0322 ÷ 0.5318 ≈ 1.94×; the dollar figures imply roughly 6.7 yuan per dollar (1,032 ÷ 153). General system prices are in Chapter 3.
Smaller makers are scaling too. Highstar Sodium's own release says its 6 GWh Neijiang plant is in final commissioning, with mass production scheduled for late October 2026 — not yet confirmed as started on 23 October. It already series-produces 50 Ah, 160 Ah and 15 Ah NFPP cells. Chery offers sodium-ion storage cells rated for up to 15,000 cycles, a vendor claim. The cautionary case is US maker Natron Energy, which closed on 3 September 2025.
Judgement: sodium-ion is now a real procurement option, but at nearly twice LFP's bid price buyers should treat it as a niche choice for cold climates or safety-sensitive sites, and insist on dated delivery schedules rather than framework GWh.
6.2 Solid-state: pilot lines and dated targets
QuantumScape announced on 21 October 2026 a planned 100 MWh cell production line for AI data centres, aerospace and defence, built with Germany's Muehlbauer Group, with cell production targeted for 2028. Its Eagle Line pilot in San Jose is the current production base. Battery Technology notes the new line is a demonstration facility, since QuantumScape licenses its technology rather than selling cells. At 0.1 GWh, it is one-sixtieth of Highstar's sodium plant.
Chery presented its Rhinoceros roadmap on 20 October: a Rhinoceros S solid-state pilot line due to start in 2027, following a 0.5 GWh pilot line for 60 Ah-class cells completed in February 2026. The 400 Wh/kg rating of its sulfide cell is a vendor claim, and no customer delivery date has been set. According to Battery-Tech Network, ProLogium and Rimac target a full-scale functional pack in H2 2027 and public-road tests in 2028.
According to 36Kr, China's MIIT released the "15th Five-Year Plan for the Development of the New Battery Industry" on 28 September 2026, setting initial large-scale use of all-solid-state batteries in 2030; South Korea's 22 September roadmap targets prototypes in 2027 and commercialisation in 2030. Samsung SDI plans mass production in H2 2027, and BYD targets small-batch output from its sulfide line in 2027. CATL chairman Zeng Yuqun rated solid-state maturity at Level 4 of 9 on 23 June 2026. Reality check: EVTank counted 8.0 GWh of solid-state shipments in 2025 (+51.9%), all semi-solid, according to Battery-Tech Network.
Judgement: nothing here affects grid-storage procurement before 2028. Solid-state is aimed at premium, safety-critical segments, not cost-optimised utility storage.
6.3 Long-duration storage and cell formats
China Huadian's 100 MW/1,000 MWh compressed-CO₂ plant in Mulei, Xinjiang achieved initial grid connection on 30 September 2026, giving a nominal 10-hour duration. Exa Energy commercialised the technology. Huadian's ">92%" figure is turbine design efficiency, not round-trip efficiency, and no verified system efficiency has been published. Annual figures differ by source: pv magazine reports about 200 GWh of expected generation, while Energy-Storage.news cites 290 GWh stored and 180 GWh discharged. That 62% output-to-input ratio is an estimate, not a measured efficiency. The plant is 12.5 times the energy of the 10 MW/80 MWh Anhui unit connected in December 2023. Energy Dome, which runs a 20 MW/200 MWh plant in Sardinia, says it is defending its patents, while Exa Energy says CO₂ thermodynamics "cannot be exclusively owned".
On cell formats, our sources show no dated 500 Ah+ LFP launch in the window; the format news was CATL's 30 MWh-plus sodium blocks.
6.4 Readiness table

| Technology | Company | Milestone | Stage (as of 2026-10-23) | Date | Source |
|---|---|---|---|---|---|
| Sodium-ion | CATL–Intilion | Up to 3 GWh DACH projects, 5 years | Announced (development target) | 2026-10-09 | ESS News |
| Sodium-ion | CATL | 1 GWh storage shipments; overseas deliveries | Plan | 2026; June 2027 | ESS News |
| Sodium-ion | Highstar Sodium | 6 GWh Neijiang plant | Final commissioning; mass production scheduled | Late Oct 2026 | Highstar |
| Sodium-ion | Highstar Sodium | 50/160/15 Ah NFPP cells | Mass production | In effect | Highstar |
| Solid-state Li-metal | QuantumScape | Eagle Line | Pilot (operating) | In effect | QuantumScape |
| Solid-state Li-metal | QuantumScape | 100 MWh line | Plan (announced 2026-10-21) | 2028 | QuantumScape |
| Solid-state | Chery | 0.5 GWh 60 Ah pilot line | Pilot (completed) | Feb 2026 | The Electric Viking |
| Solid-state | Chery | Rhinoceros S pilot line | Plan | 2027 | The Electric Viking |
| Solid-state | Samsung SDI | All-solid-state mass production | Plan | H2 2027 | 36Kr |
| Solid-state | ProLogium–Rimac | Functional pack; road tests | Plan | H2 2027; 2028 | Battery-Tech Network |
| Compressed CO₂ | China Huadian / Exa Energy | 100 MW/1,000 MWh Mulei plant | Grid-connected (initial) | 2026-09-30 | pv magazine |
7. China projects, tenders and policy
Chapter 6 covered which chemistries are moving toward production. This chapter turns to China's domestic project pipeline, where most of those cells end up, and asks whether the projects behind it can earn a return.
Core thesis: TrendForce counted 206.78 GWh of tenders and 161.94 GWh of awards in China in July–September 2026 (sum of the three monthly reports). In H1 2026, however, commissioned capacity fell for the first time. Most of the pipeline is now standalone grid-side storage rather than mandated renewable pairing, so capacity-tariff and spot-market rules will decide how much of it gets built.
7.1 Monthly tenders and awards
TrendForce's China Energy Storage Industry Tender Database (via EnergyTrend) is the only consistent monthly series in the material. First-print values, one source only:
| Month (2026) | Tendered GWh | Awarded GWh | EPC tendered / awarded GWh | Source |
|---|---|---|---|---|
| July | 54.4 (15.97 GW) | 29.88 (12.23 GW) | 39.98 / 26.47 | TrendForce (via EnergyTrend) |
| August | 79.54 (23.28 GW) | 75.99 (13.32 GW) | 60.19 / 35.35 | TrendForce (via EnergyTrend) |
| September | 72.84 (24.36 GW) | 56.07 (15.87 GW) | 59.99 / 47.44 | TrendForce (via EnergyTrend) |
The table supports three readings. First, EPC contracts now carry the volume. In September, EPC made up 59.99 of the 72.84 GWh tendered. Awarded EPC volume reached 47.44 GWh, a year-to-date high and 34% above August. Second, system-only awards move with group procurement. In August, system awards jumped 1,232% month-on-month to 40.64 GWh, mostly because of China Energy Engineering Group's 2026 centralized LFP procurement. Without a framework deal of that size, they fell 79% to 8.62 GWh in September. Third, standalone storage dominates. It accounted for 61.3 of the 72.84 GWh tendered in September, or about 84% (61.3 ÷ 72.84). TrendForce's headline gives 80%. C&I took 2% and renewables-paired storage 4%.
TrendForce calls its data "incomplete statistics", and prior months appear to be revised: its stated −4% month-on-month change for September tenders implies an August base of about 72.84 ÷ 0.96 ≈ 75.9 GWh, against the 79.54 GWh first published. Awarded prices fell in September, with the 4-hour system weighted average at RMB 0.53/Wh; Chapter 3 covers prices.
CNESA's September count is a separate series. CNESA data quoted by BOCOM International (via Zhitong Finance) put energy storage EPC tenders (including PC) at 53.4 GWh, the sixth month in a row above 40 GWh, and awards at 50.7 GWh, up 18.9% month-on-month and a year high. System awards excluding centralized and framework procurement were about 15.1 GWh (+43.7%). The gap to TrendForce's 59.99 GWh tendered and 47.44 GWh awarded for EPC is definitional: CNESA folds PC contracts into EPC and strips framework deals out of its system figure, while TrendForce keeps them in. CNESA's figure also reaches us second-hand, through a broker note. Do not add or average the two series. They agree on direction: EPC awards set a year high in September.
7.2 Installations and returns
According to CNESA's own 15 October analysis, 21.64 GW / 58.20 GWh of new-type storage came online in H1 2026. Both figures fell more than 15% year-on-year, the first contraction after years of rapid growth. Secondary sources cite slightly different CNESA figures: ~21.81 GW / 58.60 GWh, −18%, in Citi's report, and 58.6 GWh, −16%, in The Elec. This chapter follows CNESA's own publication.
At end-2025, China's commissioned electric storage reached 213.3 GW (+54% YoY), 43.0% of the global total. New-type storage accounted for 144.7 GW, of which standalone projects made up 58%. New projects in 2025 averaged 2.85 hours of discharge.
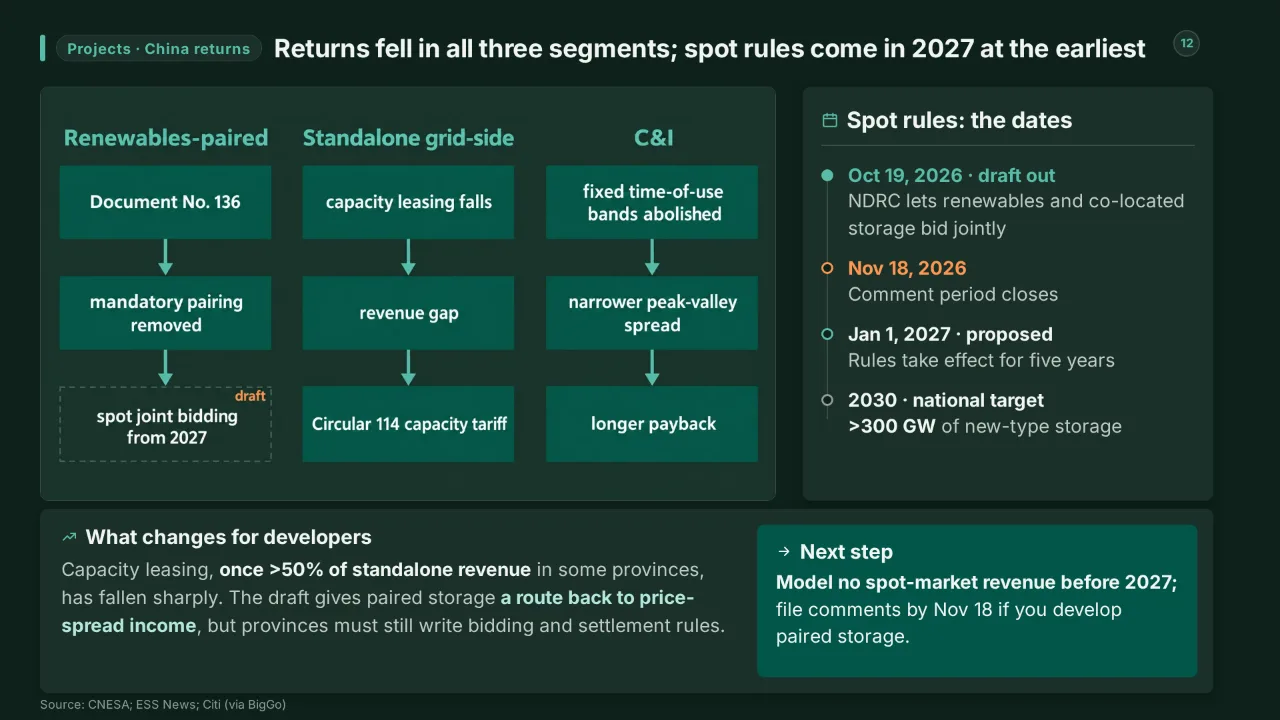
CNESA explains the slowdown in commissioning by falling returns in all three segments:
- Renewables-paired storage: with mandatory pairing abolished, developers have less reason to build, and existing income does not cover capital and operating costs.
- Standalone storage: capacity-leasing income, once more than 50% of revenue in some provinces, has fallen sharply, and capacity tariffs do not fill the gap.
- C&I storage: administratively set time-of-use bands have been abolished, which narrows peak-valley spreads and lengthens payback periods.

Demand data from manufacturers point the other way. Energy storage battery sales reached 73.5 GWh in September (+104.4% YoY) and 595.4 GWh in January–September (+111.8%), according to the China Automotive Power Battery Industry Innovation Alliance (via BOCOM). About 21% of September sales (15.6 ÷ 73.5 GWh) were exports. The Elec notes that orders have turned into actual installations more slowly than expected. A rough comparison: TrendForce's Q3 awards of 161.94 GWh are nearly three times CNESA's H1 commissioning of 58.20 GWh. The two figures come from different sources and definitions, and awards come before commissioning, so treat this only as a sign that the backlog is growing faster than projects are built.
7.3 Policy changes and effective dates
| Policy | What it does | Status at 2026-10-23 | Source |
|---|---|---|---|
| Document No. 136 | Removes mandatory storage pairing as a grid-connection precondition | In effect since Feb 2025 | CNESA; Citi via BigGo |
| Circular 114 | National capacity-tariff pathway for standalone grid-side storage | In effect (issue date not in material) | CNESA |
| NDRC draft Basic Rules for Electricity Spot Markets | Joint bidding by renewables plus co-located storage (Article 8); names new-type storage and VPPs as participants; locational marginal pricing; daily clearing, monthly billing | Draft, released 2026-10-19; comments until 2026-11-18 (upcoming); proposed effective 2027-01-01 for five years, replacing the 2023 interim rules | ESS News |
| 2% consumption tax on lithium-ion batteries | Adds cost pressure on cell makers | In effect since September 2026 | BOCOM via Zhitong |
| National new-type storage target | >300 GW by 2030 (set 2026), up from >180 GW by 2027 (set 2025) | In effect (target) | CNESA |
The spot-market draft is the most important item in the window. It gives paired storage, which lost much of its business case under Document No. 136, a way to earn from price spreads alongside its plant. The national text leaves bidding formats, metering, charging restrictions and settlement to provincial rules, and Shandong already runs a similar mechanism. Developers should therefore not expect the extra revenue before 2027, and even then only where provinces have written the detailed rules.
7.4 Large projects and forecasts
The material names no single headline project in the window, but volume is concentrated geographically. In September, Shanxi led tenders with 9.8 GWh, and Inner Mongolia, Ningxia and Xinjiang each tendered more than 5 GWh. Inner Mongolia and Ningxia each passed 7.5 GWh of awards, driven by several GWh-scale standalone projects. August tenders included 17 projects of 1 GWh or more, and Xinjiang led awards with 10.7 GWh.
On the outlook, CNESA forecasts cumulative new-type storage of 365–435 GW by 2030 and 527–615 GW by 2035 (estimate). In its 7 October report, Citi rejects the view that China's storage demand peaks in 2026 and forecasts about 15% growth in 2027 (estimate). Our judgement: the forecasts are consistent with the tender backlog. The binding constraint is converting awards into revenue-earning assets, not tender volume.
8. Overseas markets
Where China's pipeline (Chapter 7) is defined by tenders, overseas news between 9 and 22 October 2026 was mostly about projects climbing the stage ladder: contracts signed, debt closed, construction finished. Overseas demand is no longer the constraint; converting announced gigawatt-hours into energised ones is. The aggregate Q3 overseas order book of Chinese integrators (about 67.8 GWh signed) belongs to Chapter 5; this chapter tracks individual markets and projects.
8.1 United States: fewer megawatts, more hours, and capital still flowing
According to Wingzman's summary of the Wood Mackenzie / American Clean Power Association US Energy Storage Monitor (released 22 September 2026), the US installed 5.4 GW / 18.9 GWh in Q2 2026, a record in energy terms, while power fell 7% year on year. The average system lengthened from 2.8 to 3.5 hours (check: 18.9 GWh ÷ 5.4 GW = 3.5 h), driven by resource-adequacy needs. Utility-scale system prices were US$916/kW, down 2%. Sources differ on energy growth: Wood Mackenzie says 17%, while pv magazine USA and ESS News say 16%. We follow Wood Mackenzie. Wood Mackenzie estimates 207 GW / 715 GWh of cumulative installations by 2031, but warns that utility-scale volumes may stagnate in 2026–2027 under supply-chain and trade restrictions (estimate).
Capital has not paused. Flatiron Energy reached financial close on about US$850 million for the 1.2 GWh Energizar BESS in Chelsea, Massachusetts (Flatiron release of 15 October 2026, via Enerdata). Commercial operation is targeted for Q4 2027, and the package includes a tax-credit transfer commitment. Ørsted's 250 MW / 500 MWh Old 300 Storage project in Texas reached commercial operation earlier in 2026. For buyers, US procurement is now specified in hours, not megawatts.
8.2 Europe: GWh-scale contracts and buyers organising
Germany produced the window's flagship contract. On 14 October 2026, Vattenfall and Fluence announced an agreement for the Brunsbüttel BESS on a decommissioning nuclear site. It is rated 254 MW with "over 1,000 MWh" of storage, uses Fluence's Gridstack Pro 5000 and is delivered turnkey with long-term service. ESS News puts the energy at 1,016 MWh (a four-hour system: 1,016 ÷ 254 = 4.0 h). Status: contracted. Construction starts in 2027, and operation and connection to the 50Hertz 380 kV grid are planned for end-2028. Vattenfall says the project nearly doubles its existing battery capacity.
In the UK, Ørsted completed construction of the 300 MW / 600 MWh Iceni BESS beside the Hornsea 3 converter station on 21 October 2026. It uses 170 Tesla Megapacks, and its first commissioning stage is underway, so it is not yet operational.
The most structural European news concerns contracts. On 13 October 2026, 22 developers and asset owners representing 40 GWh of storage launched the Energy Storage Contract Alliance (ESCA) in Switzerland, with an open-source model BESS contract. According to purchaser.ai (citing Renewables Now), standard terms could cut negotiation from 6–12 months to 4–8 weeks. Treat this secondary-source claim as a target; if it holds, integrators will compete more on price than on bespoke warranty terms.
8.3 Asia-Pacific and India: money in Australia, a delivery gap in India
Australia's news was about refinancing, not new builds. Akaysha Energy (sponsored by BlackRock) closed an A$1.75 billion portfolio refinancing of more than 1 GW of BESS assets: Orana, Elaine, Brendale and Ulinda Park. The facility is backed by 11 banks and will support a development pipeline of about 6 GW / 25 GWh, according to TaiyangNews. Akaysha already operates the 850 MW / 1.68 GWh Waratah Super Battery. Banks now underwrite BESS-only portfolios on tolling and revenue-swap contracts, a sign of a maturing asset class.
India has the widest gap between pipeline and operation. Indoen (citing a Rubix report) says India added 8.2 GWh in H1 2026, against under 100 MWh a year earlier. Operating capacity was 9.08 GWh on 31 August 2026, about 26% of the 34.72 GWh needed in FY2026–27 (9.08 ÷ 34.72 = 26.2%). The pipeline exceeds 176 GWh, but tendered capacity in H1 rose to 28 GW while auctioned capacity fell to 9 GW. About 75% of allocated two-hour capacity is classed "at risk" after tariffs fell more than 71% between 2022 and 2025. China supplied 84% of India's lithium-ion battery imports in FY2026.
New procurement continued. On 12 October 2026, NTPC Green Energy invited EPC bids for a 3,300 MWh BESS at Khavda, Gujarat, in four blocks: 3 × 300 MW/900 MWh plus 1 × 200 MW/600 MWh = 1,100 MW / 3,300 MWh (3-hour), with 15 years of O&M: tendered. ACME Solar signed a 300 MW / 1,200 MWh FDRE-IX PPA with SECI at INR 6/kWh: contracted. For suppliers the risk is delivery, not demand: aggressive tariffs and 9–18 month delays make awards less bankable than their size suggests.
8.4 Emerging markets: Gulf EPC, Brazil's first auction, Caribbean islands
Brazil registered 296.8 GW of battery projects for an auction expected to contract only 2–5 GW, so at most about 1.7% of the registered capacity (5 ÷ 296.8) can win.
Brazil's first BESS auction is split into a local-content round on 2 December 2026 and an open round two days later (4 December). Both are upcoming, and both contract capacity from 2028. BNamericas reports investment of up to R$20 billion (US$4 billion) and says China Southern Power Grid International has met regulator Aneel about the rules.
In the Gulf, POWERCHINA's Shandong Electric Power Construction won the EPC contract for the 500 MW / 2,000 MWh Saudi Group 1-KSB standalone BESS, with SPPC as offtaker. Status: contracted (reported 20 October 2026).
In Puerto Rico, Polaris Renewable Energy awarded Trina Storage the BESS supply contract for Punta Lima on 20 October 2026. The system is a single 35.7 MW, 8-hour unit (35.7 × 8 = 285.6 MWh). Deliveries are due March/April 2027 and COD is expected in Q3 2027 under a 20-year term. Polaris estimates capex at US$55–60 million including transformer, tariffs and balance of plant. That implies about US$193–210/kWh all-in (55m–60m ÷ 285,600 kWh; derived, not company-stated). It expects about US$12.5 million of first-year EBITDA. The same release lists 61.6 MW / 192 MWh of Mexican storage in planning. The pattern: Chinese suppliers and investors (Trina, POWERCHINA, CSGI) are winning or pursuing emerging-market work where price and EPC capacity decide, while Fluence and Tesla took this fortnight's largest European projects.
8.5 Project tracker
Sorted by energy capacity. MWh values are as reported or computed from the source's own block sizes; "—" means not disclosed.
| Project | Country | MW | MWh | Supplier / EPC | Stage (as of 2026-10-23) | Date | Source |
|---|---|---|---|---|---|---|---|
| NTPC Green Khavda BESS | India | 1100 | 3300 | EPC bidder not yet selected | Tendered | 2026-10-12 | ESS News |
| Saudi Group 1-KSB | Saudi Arabia | 500 | 2000 | Shandong Electric Power Construction (POWERCHINA) | Contracted | 2026-10-20 (reported) | TaiyangNews |
| Waratah Super Battery (Akaysha) | Australia | 850 | 1680 | — | Operational | 2026-10-20 (reported) | TaiyangNews |
| ACME Solar FDRE-IX | India | 300 | 1200 | — | Contracted (PPA with SECI) | 2026-10-20 (reported) | TaiyangNews |
| Energizar (Flatiron) | United States | — | 1200 | — | Financed; COD Q4 2027 | 2026-10-15 | Flatiron via Enerdata |
| Brunsbüttel (Vattenfall) | Germany | 254 | 1016 | Fluence (Gridstack Pro 5000) | Contracted; build 2027, operate end-2028 | 2026-10-14 | Vattenfall/Fluence release; ESS News |
| Iceni BESS (Ørsted) | United Kingdom | 300 | 600 | Tesla (170 Megapacks) | Construction complete; commissioning | 2026-10-21 | ESS News |
| Old 300 Storage (Ørsted) | United States | 250 | 500 | — | Operational | 2026 (earlier in year) | ESS News |
| Punta Lima (Polaris) | Puerto Rico (US) | 35.7 | 285.6 | Trina Storage | Contracted (supply); COD Q3 2027 | 2026-10-20 | Polaris release |
| Polaris Mexico storage | Mexico | 61.6 | 192 | — | Planning | 2026-10-20 | Polaris release |
Of the 11,973.6 MWh in this tracker, only 2,180 MWh (Waratah 1,680 + Old 300 500), or about 18%, is operating. This is the delivery gap that runs through the chapter.
9. Outlook and what to watch
Chapter 8 ended on the delivery gap overseas. This chapter turns the fortnight into decisions. It adds no new facts: every figure is cited where Chapters 2–8 first developed it.
9.1 What the fortnight means, by stakeholder
The common thread is a two-speed market. Commodity LFP is getting cheaper and more contestable, while bankable, compliance-ready supply stays tight. Each stakeholder sits on a different side of that split.
| Stakeholder | What changed | Implication | Evidence |
|---|---|---|---|
| Storage buyers in China | Award prices fell in September; spot system quotes did not | Anchor negotiations on September awards (4h EPC RMB 0.78/Wh), not weekly spot or H1 averages | TrendForce; InfoLink |
| Overseas utility buyers | Cells cheaper at source, but landed and compliant supply is not | The US premium sits after the pack (packs +44%, turnkey ≈3×); budget for tariffs, FEOC and EU document checks | BNEF; 36Kr |
| Developers in China | Pipeline large, returns thin; commissioning fell in H1 | Revenue stacking depends on capacity tariffs and the draft spot rules, which take effect no earlier than 1 Jan 2027 | CNESA; ESS News |
| Cell makers | Volume up, margin down; tier-1 sold out, tail idle | Expect further consolidation; system integration is where margin is contested | ChinaEVHome; TrendForce via 36Kr |
| Investors | Upstream profit peak has passed; integrators face tariff and FX noise | Read revenue per GWh and gross margin, not deployments alone | BigGo; Electrek |
| Technology scouts | Sodium orders far ahead of deliveries; solid-state on 2027–2030 timelines | Pilot sodium in cold or safety-sensitive sites; treat solid-state as a post-2028 option for grid storage | ESS News; QuantumScape |
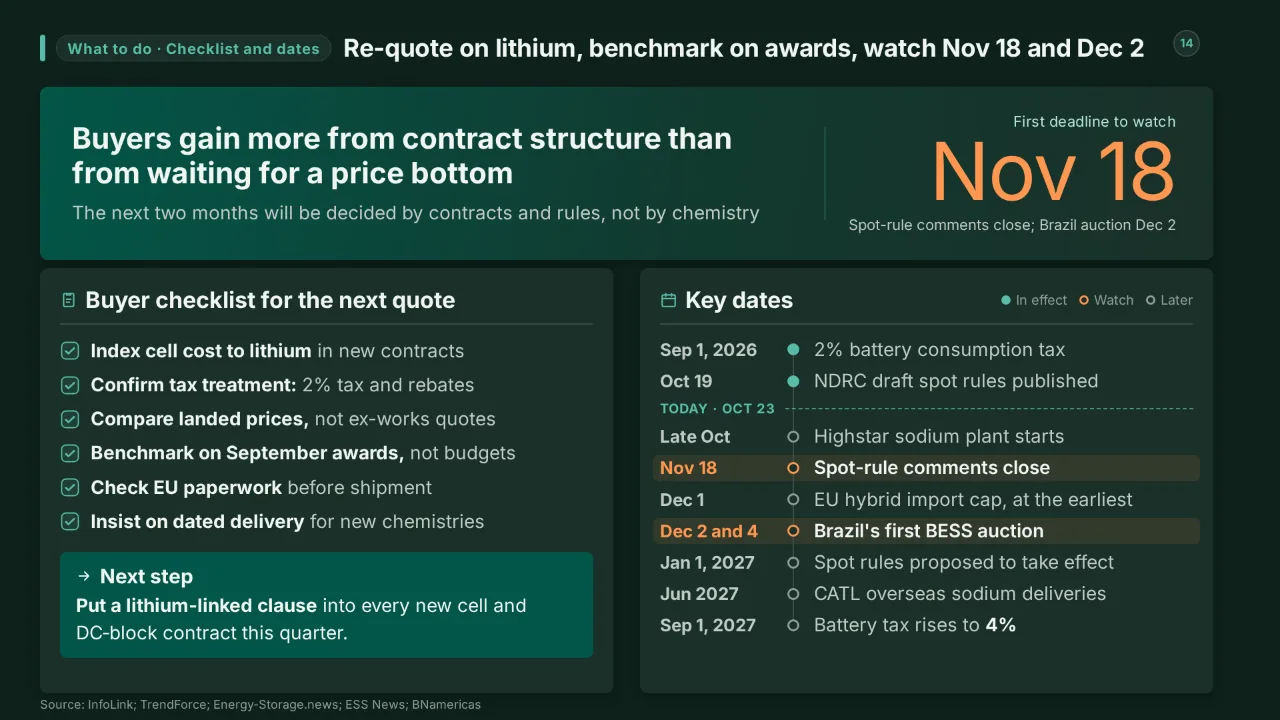
Judgement on prices. The lithium move has not finished passing through. Benchmark expects September's carbonate fall to show up in October–November cell quotes, and InfoLink's estimated corridor of RMB 100,000–120,000/t leaves limited further downside. The 2% consumption tax adds a floor of about RMB 0.007/Wh. The likely path is therefore a slow drift lower in cell and system quotes over the next two months, not a step change. Buyers gain more from contract structure than from waiting.
Judgement on volumes. Nothing in the fortnight suggests demand is the constraint. Chinese tenders ran above 54 GWh in each month of Q3, overseas signed orders reached 67.8 GWh in one quarter, and Tesla's 2027 book is nearly full. The constraint is conversion: returns in China, interconnection and bankability in India, and qualification for credits in the US.
9.2 Buyer checklist for the next quote
- Index cell cost to lithium. Write a lithium-linked adjustment clause into new cell and DC-block contracts instead of trying to time the bottom.
- Ask what the price includes. Confirm treatment of China's 2% consumption tax and export rebates; EVE passes the tax through on domestic sales from 1 September.
- Compare on a landed basis. In September, CIF North America ran about 20% above EXW China for the same 314 Ah cell, before tariffs.
- Benchmark against awards, not budgets. Use TrendForce's September averages (4h system RMB 0.53/Wh, 4h EPC RMB 0.78/Wh) as the reference, and treat project budgets such as Wusu's RMB 1.03/Wh as ceilings.
- Check compliance paperwork before shipment. EU carbon-footprint and traceability documents triggered re-checks on more than 10% of arriving cabinets since August, adding 7–14 working days.
- Insist on dated delivery for new chemistries. Sodium-ion framework GWh are not delivery schedules; CATL's own 2026 shipment target is 1 GWh, with overseas deliveries from June 2027.
- Use standard contract terms where possible. The ESCA open-source BESS contract targets negotiation in 4–8 weeks instead of 6–12 months; treat the saving as a target.
9.3 Key dates
Status is judged against the run date, 23 October 2026.
| Date | Event | Status on 2026-10-23 | Source |
|---|---|---|---|
| 1 Sep 2026 | 2% consumption tax on lithium-ion batteries | In effect | Energy-Storage.news |
| 30 Sep 2026 | Mulei 100 MW/1,000 MWh compressed-CO₂ plant, initial grid connection | In effect | pv magazine |
| 19 Oct 2026 | NDRC draft spot-market rules released | In effect (draft published) | ESS News |
| Late Oct 2026 | Highstar 6 GWh Neijiang sodium plant, mass production scheduled | Upcoming; not confirmed started | Highstar |
| 18 Nov 2026 | Comment deadline for the spot-market draft | Upcoming | ESS News |
| 1 Dec 2026 (earliest) | EU cap of ~350,000 Chinese hybrid imports in year 1 | Announced | Crux Investor; SunSirs |
| 2 and 4 Dec 2026 | Brazil's first BESS auction (local-content round, then open round) | Upcoming | BNamericas |
| 1 Jan 2027 | Spot-market rules proposed to take effect | Proposed | ESS News |
| 2027 | Tesla 2027 Megapack capacity nearly sold out; LG ES Michigan LFP supply begins | Upcoming | investingLive; Basenor |
| Jun 2027 | CATL sodium-ion overseas storage deliveries begin | Planned | ESS News |
| 1 Sep 2027 | Battery consumption tax rises to 4% | Announced | Energy-Storage.news |
| Q3 2027 | Punta Lima (Puerto Rico) COD | Planned | Polaris |
| Q4 2027 | Energizar 1.2 GWh (Massachusetts) COD | Planned | Enerdata |
| End-2028 | Brunsbüttel 254 MW/1,016 MWh operation | Planned | Vattenfall/Fluence |
| 2028 | QuantumScape 100 MWh line cell production | Planned | QuantumScape |
| 2030 | China's target for initial large-scale use of all-solid-state batteries | Plan | 36Kr |
The next two months will be decided by contracts and rules, not by chemistry: lithium-indexed quotes, the spot-market comment period, the EU hybrid cap and Brazil's first auction.
10. References
This document draws on the following 90 sources, listed in the order they are first cited.
- SunSirs: Lithium Carbonate Fell to a New Low for the Year, Driven by the Convergence of Unmet Peak-Season Demand Expectations and Forecasts of Long-Term Oversupply — sunsirs.com
- Chinese lithium prices tumble to nearly 10-month low on demand concerns - MINING.COM — mining.com
- Lithium salt price declines persist; cell prices move lower and system prices hold steady-Industry-InfoLink Consulting — infolink-group.com
- Battery Cell Price Review Q3 2026 — source.benchmarkminerals.com
- CATL, EVE Energy lead Chinese manufacturers’ battery storage cell price hikes — energy-storage.news
- Storage Tenders Hit 72.84 GWh in September; EPC Awarded Volume Hits New High for the Year - EnergyTrend — energytrend.com
- China Energy Storage Tenders H1 2026: Prices Rebound as 4-Hour ESS Gains Momentum — en.cnesa.org
- Three Companies Including Tianqi Lithium Disclose Q3 2026 Financial Results - EnergyTrend — energytrend.com
- CATL Q3 Revenue Climbs 59% as Net Profit Growth Cools to 15% | ChinaEVHome — chinaevhome.com
- Tesla (TSLA) Q3 2026 earnings preview: flat revenue, falling profits — electrek.co
- Tesla energy revenue drops 16% as it refunds customers over tariffs | Electrek — electrek.co
- 94GWh Breakthrough: Chinese Enterprises Capture Over 90% of Global Overseas Energy Storage Orders | Amid Record Contract Signing Spree, Key Industry Challenges Remain — eu.36kr.com
- July 2026 Energy Storage Bidding Exceeds 50 GWh, EPC Prices Rise - EnergyTrend — energytrend.com
- Nearly 76 GWh of Energy Storage Winning Bids in August, Annual Record Broken — energytrend.com
- Three Major Application Segments See Shrinking Returns — Can China’s New Energy Storage Resolve Its Profitability Bottleneck? — en.cnesa.org · 2026-10-14
- CATL’s Energy Storage Orders Hit 96.96GWh in 2026, Sodium-Ion Accounts for 72%-eefocus — global.eefocus.com
- CATL, Intilion target up to 3 GWh of sodium-ion storage in Europe - Energy Storage — ess-news.com
- Why Sodium-Ion Won 2026 and All-Solid-State Is Still a 2027 Bet - Battery-Tech Network — battery-tech.net
- QuantumScape Announces Plans for 100 MWh Solid-State Battery Production Line for AI Data Centers, Aerospace and Defense | Wed, 10/21/2026 - 16:15 — ir.quantumscape.com
- China’s first 100 MW/1,000 MWh compressed CO2 storage plant connects to grid - pv magazine Global — pv-magazine.com
- 2026 H1 Global Energy Storage System Shipment Ranking - SANSE — cn-frp.net
- Tesla earnings call: Targets 5 million cars a year by 2030, says 2027 Megapack supply nearly sold out — investinglive.com
- EARNINGS CALL Tesla (TSLA) CEO Elon Musk says the company will increase production to meet demand; company is aiming to produce approximately 5mln vehicles annually by 2030 | Newsquawk — newsquawk.com
- Battery storage pipeline of 176.66 GWh meets a hard test: Turning tenders into working capacity | INDOEN — indoen.com
- China's CSG eyes Brazil battery auction worth up to US$4bn - BNamericas — bnamericas.com · Wed Oct 14
- Fluence signs Vattenfall deal for 1,000 MWh+ battery | FLNC Stock News — stocktitan.net · 2026-10-14
- Fluence to supply 1 GWh battery for Vattenfall in Germany - Energy Storage — ess-news.com · 2026-10-15
- China outlines new spot market rules supporting renewable energy and storage integration - Energy Storage — ess-news.com · 2026-10-21
- Lithium Market Trends: Q3 2026 Review and Forecast | INN — investingnews.com
- Lithium Falls on EU Hybrid Quota While Chinese Battery Output Rises - Article | Crux Investor — cruxinvestor.com
- SMM Cobalt-Lithium Morning Meeting Summary Raw material price trends diverge; supply-demand support for battery materials varies in strength - Shanghai Metals Market (SMM) — news.metal.com
- Market & Supply Chain — infolink-group.com
- SunSirs: China Lithium Carbonate Slumps to Annual Low Amid Supply-Demand Imbalance — sunsirs.com
- China LFP Battery Cell Prices 2026: Trends, Data & Buyer Guide — ljyenergy.com
- India BESS Customs Duty 2026: 10% Rate for Grid Storage — negupenergy.com
- US Tariffs, Freight Costs Undercut Chinese Battery Price Advantage < Battery < 기사본문 - The Elec Inc. — thelec.net
- Lithium salt prices continue to decline; cell prices edge lower and ESS prices hold steady-Industry-InfoLink Consulting — infolink-group.com
- US vs China Battery Storage Costs: Where the Gap Comes From — strategicrevenueinsights.com
- China H1 2026: New-type energy storage additions fall 18%, overseas orders jump 83% - Energy Storage — ess-news.com
- China’s half-year energy storage deployments post first-ever decline to 22GW/59GWh, while overseas orders surge 83% — energy-storage.news
- DBM Video: Terminate Before Bid Opening! Xinjiang 200MW/800MWh Independent Energy Storage Project EPC Bidding Regeneration Variables! — cementchina.net
- Battery storage system prices continue to fall sharply, BNEF and Ember reports find - Energy-Storage.News — energy-storage.news
- Lithium-Ion Battery Pack Prices Fall to $108 Per Kilowatt-Hour, Despite Rising Metal Prices: BloombergNEF | BloombergNEF — about.bnef.com
- Batteries beat gas peakers on cost globally, but U.S. faces trade headwinds - pv magazine Global — pv-magazine.com
- Li-ion battery pack prices fell 8% since last year despite metals prices rising, BloombergNEF says — energy-storage.news
- CATL Posts Strong Profit and Revenue Growth in 2026 Third Quarter - The Globe and Mail — theglobeandmail.com
- Tesla Q3 2026 Earnings: Spending Slows, Free Cash Flow Turns Positive — stocktitan.net
- Batteries & Energy Storage - Venture Atlas — ventureatlas.org
- CATL Earnings Date, Reports & Earnings Call - moomoo — moomoo.com
- CATL's First Three Quarters Profit Rises 31.6%, but Third-Quarter Net Profit Falls Short of Market Expectations — BigGo Finance — finance.biggo.com
- Battery Pack Market Size, Share & Forecast to 2036 — meticulousresearch.com
- Top 10 Energy Storage Battery Cell Manufacturers 2026 — bsl-battery.com
- Tesla Gears Up to Report Q3 Earnings: Here's What to Expect — finance.yahoo.com
- Tesla Energy Revenue Drops 16% on Tariff Refunds — shattered.io
- 1H26 energy storage cell shipment rankings: Global and non-China markets-Industry-InfoLink Consulting — infolink-group.com
- Energy storage cell shipment data for H1 2026 reveal three structural shifts - pv magazine Global — pv-magazine.com
- Latest news about ESS Industry - Page 5 of 126 | ESS News — ess-news.com
- HiTHIUM 6.25MWh LDES and AC Coupled Storage at IGEM 2026 — xihopower.com
- China's Tianqi Lithium forecasts over 27-fold jump in first three quarters' net profit, but Q3 profit slumps more than 25% quarter-on-quarter — BigGo Finance — finance.biggo.com
- Unpacking China | Key Chinese Firms to Watch This Week (11/10/2026-17/10/2026) | EqualOcean — equalocean.com
- Tesla Energy Eyes 10GW Year as 2027 Megapack Capacity Sells Out — basenor.com
- Timeline: Every Tesla Gigafactory from Nevada to Shanghai | Manufacturing Digital — manufacturingdigital.com
- Hithium doubles cumulative battery shipments to 200 GWh in 14 months - Energy Storage — ess-news.com
- NeoVolta Opens Georgia Battery Plant Ahead of Production - Environment+Energy Leader — environmentenergyleader.com
- Clean Investment Monitor: The State of US Clean Energy — cleaninvestmentmonitor.org
- How domestic cleantech manufacturing is faring under Trump | Latitude Media — latitudemedia.com
- Solar & Storage Supply Chain Dashboard – SEIA — seia.org
- Battery Storage For Data Centers In 2026: FEOC Compliance, FERC Co-Location, And The Deals Getting Done Now | Legal 500 — legal500.com
- §48E and §45Y tax credits: 2026 guide — crux.com
- Foreign Entity of Concern Interpretive Guidance | Department of Energy — energy.gov
- Exclusive: Chinese energy storage giants reportedly exit US as two-way tech restrictions open door for non-Chinese suppliers — digitimes.com
- Clean Investment Monitor: Global H1 2026 Update – Rhodium Group — rhg.com
- TSLA: Fundamentals Set a Floor, AI Milestones Pushed Back? | Longbridge — longbridge.com
- Highstar Sodium Completes New Equity Financing; 6GWh Neijiang Sodium-ion Battery Plant to Start Production in Late October 2026 - Highstar Sodium battery — highstar-sodium.com
- Chery Details 400 Wh/kg Solid-State Battery and 12C Liquid Cell Roadmap - The Electric Viking — theelectricviking.com
- QuantumScape's 100-MWh Line Targets AI Data Centers, Defense — batterytechonline.com
- BatteryTech News & Updates — 2026 #42 - Battery-Tech Network — battery-tech.net
- China, Japan, South Korea Jointly Target 2030: The Decisive Battle for Solid-State Batteries Is Coming — eu.36kr.com
- Energy Dome & Exa Energy’s CO2 storage technology compared as 1GWh China project goes online — energy-storage.news
- BOCOM International: Battery demand remains supported; concerns over profitability and 2027 demand are already partially priced in. — moomoo.com · 2026-10-21
- Citigroup: Battery Supply Chain's Second Expansion Cycle Poses Manageable Risks, Energy Storage Takes Over as Core Growth Engine — BigGo Finance — finance.biggo.com · 2026-10-09
- Lithium Prices Slump on Oversupply Fears, Raising Battery Market Uncertainty < Battery < 기사본문 - The Elec Inc. — thelec.net · 2026-10-18
- US Storage Hits Record 18.9 GWh in Q2 2026 | Wingzman — wingzman.com · 2026-10-11
- Flatiron closes USD850m financing for 1.2 GWh Massachusetts BESS | Enerdata — enerdata.net
- Ørsted completes construction of 600 MWh UK battery storage project at offshore windfarm - Energy Storage — ess-news.com · 2026-10-21
- The Procurement Brief — 40 GWh BESS Alliance, Defense Critical Minerals Floors, Record Port of LA Volumes, and Truckload Capacity Squeeze - The Procurement Brief — purchaser.ai · 2026-10-19
- Allens advises lenders on A$1.75bn Akaysha Energy BESS portfolio refinanc — allens.com.au · 2026-10-16
- Global Battery Storage News Snippets — taiyangnews.info · 2026-10-20
- NTPC tenders 3.3 GWh of battery storage in India - Energy Storage — ess-news.com · 2026-10-12
- Polaris Renewable Energy Awards Key Supply Contract and Issues Notice to Proceed on Punta Lima Battery Storage Investment | Newswire — newswire.com · 2026-10-20