1. Key takeaways from the window
Between 23 October and 2 November 2026, lithium fell again, the first Q3 results showed where margins are being squeezed, and most of the new orders and plans were still intent rather than operating capacity. The five conclusions below summarise Chapters 2–8. Events dated before 23 October are labelled as context where they appear.

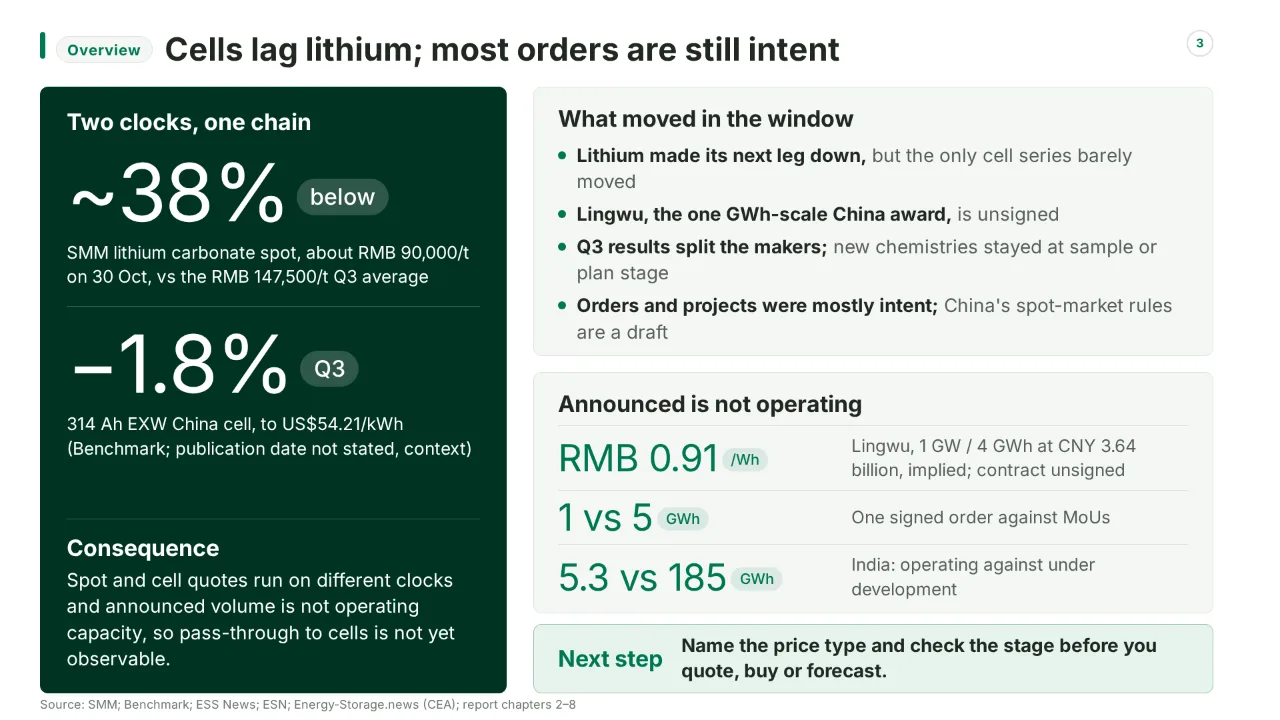
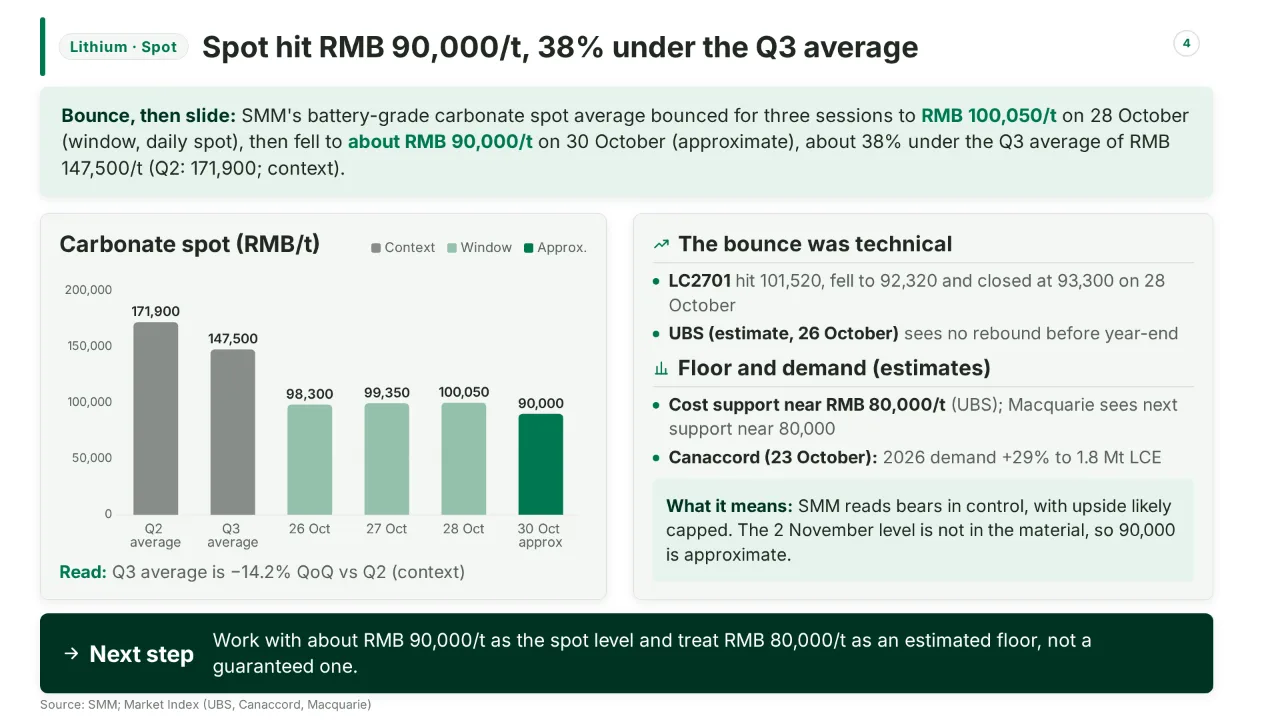
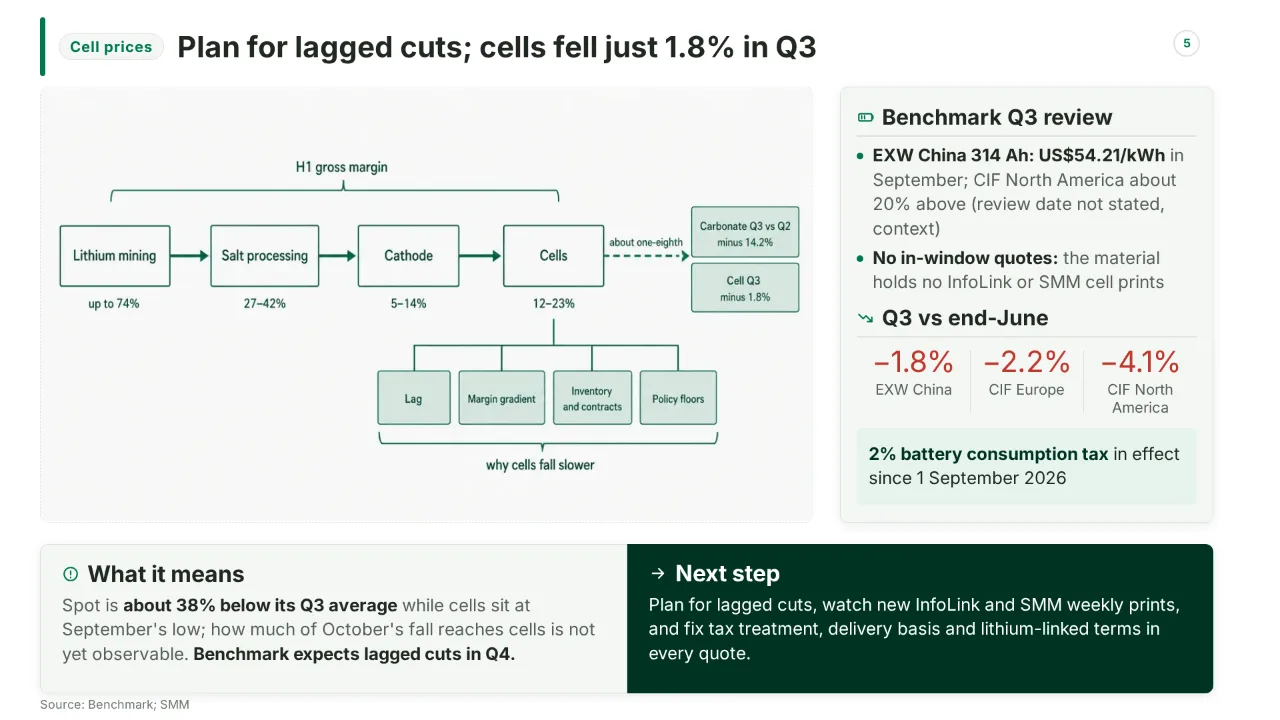
1. Lithium carbonate made its next leg down, but the cell price data in the material has barely moved. SMM's spot average bounced to RMB 100,050/t on 28 October (range 97,700–102,400), then fell to about RMB 90,000/t on 30 October, roughly 38% below its Q3 average of RMB 147,500/t. UBS (estimate) sees no rebound before year-end, with cost support near RMB 80,000/t. Benchmark's 314 Ah EXW China cell fell only 1.8% in Q3, to US$54.21/kWh in September, and the material holds no in-window InfoLink or SMM cell quote, so pass-through is not yet observable [Chapter 2].
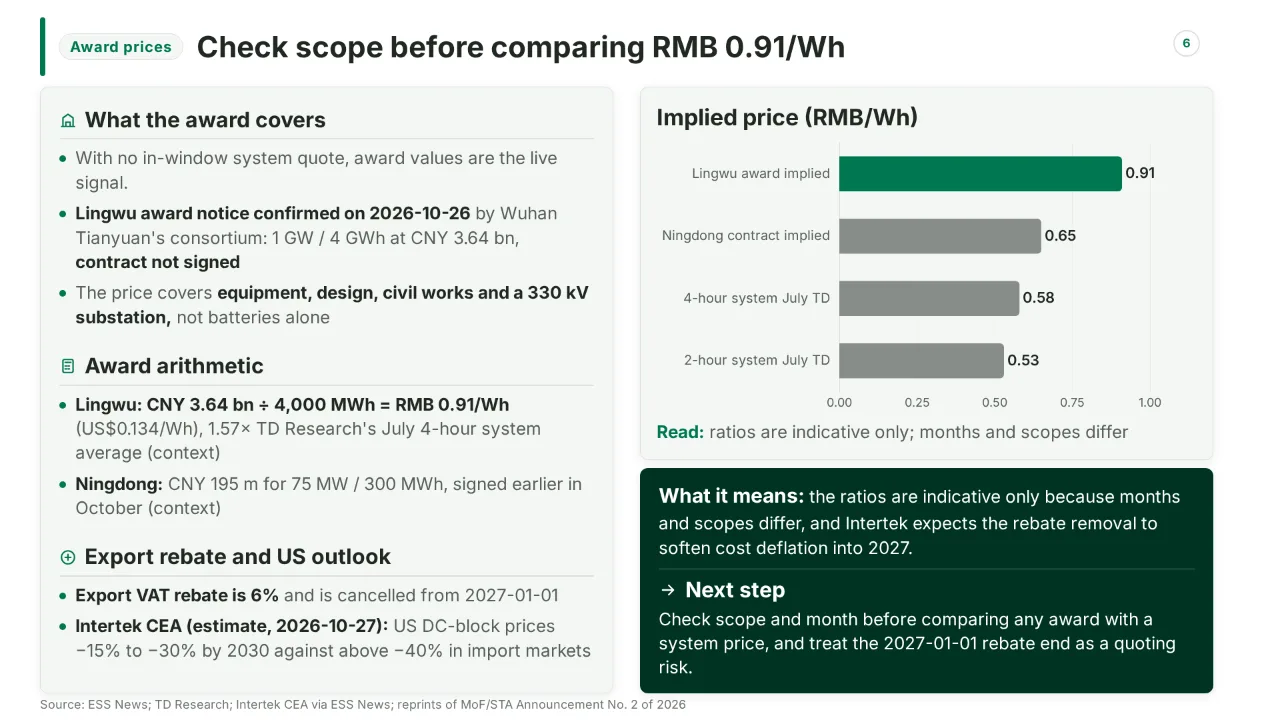
2. System prices show up as award values, not quotes, and the one GWh-scale China award is unsigned. Wuhan Tianyuan's consortium confirmed its award notice on 26 October for the 1 GW / 4 GWh Lingwu project at CNY 3.64 billion, an implied RMB 0.91/Wh that covers equipment and construction, with no contract signed. TD Research's July 4-hour system average was RMB 0.58/Wh (context). The battery export VAT rebate is 6% and is cancelled from 2027-01-01, and Intertek CEA says Q2 shipments of about 230 GWh (+18%) were lifted by pre-stocking [Chapters 3, 5].
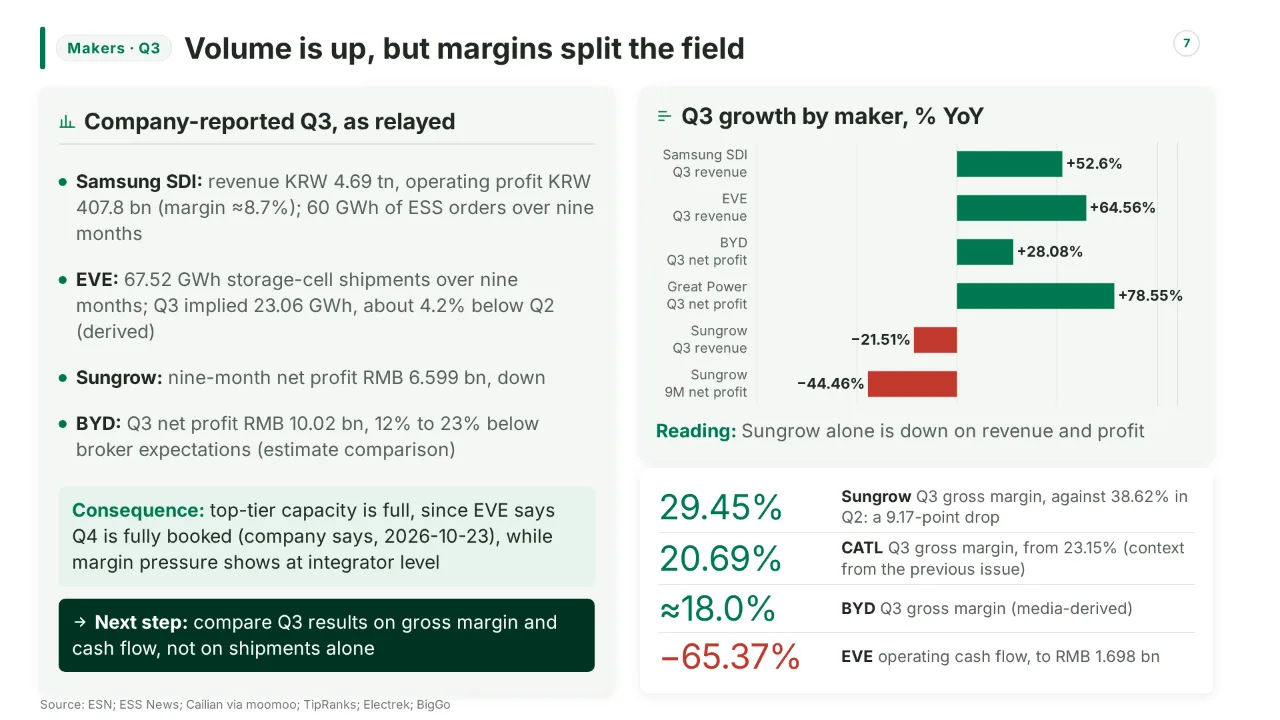
3. Q3 results split the field: storage volume is up, margins and cash flow are mixed. Samsung SDI reported revenue of KRW 4.69 tn (+52.6%) and 60 GWh of ESS orders. EVE's nine-month storage shipments were 67.52 GWh (+39.46%), with Q3 implied at 23.06 GWh, about 4.2% below Q2. Sungrow's nine-month net profit fell 44.46% and its Q3 gross margin dropped to 29.45% from 38.62%. BYD's Q3 profit of RMB 10.02 bn was 12% to 23% below broker expectations [Chapter 4].
4. New chemistries stayed at sample or plan stage; the scale gains were in format. CATL says pilot production of all-solid-state cells starts in 2027, from 20 Ah samples. Samsung SDI supplied samples to humanoid customers in September and targets H2 2027. Peak Energy's 4 GWh sodium-ion plant is planned for production in Q1 2027 and is not yet producing. The concrete gains, CATL's roughly 9 MWh TENER+ container and Envision's 790 Ah cell, are vendor claims [Chapter 6].
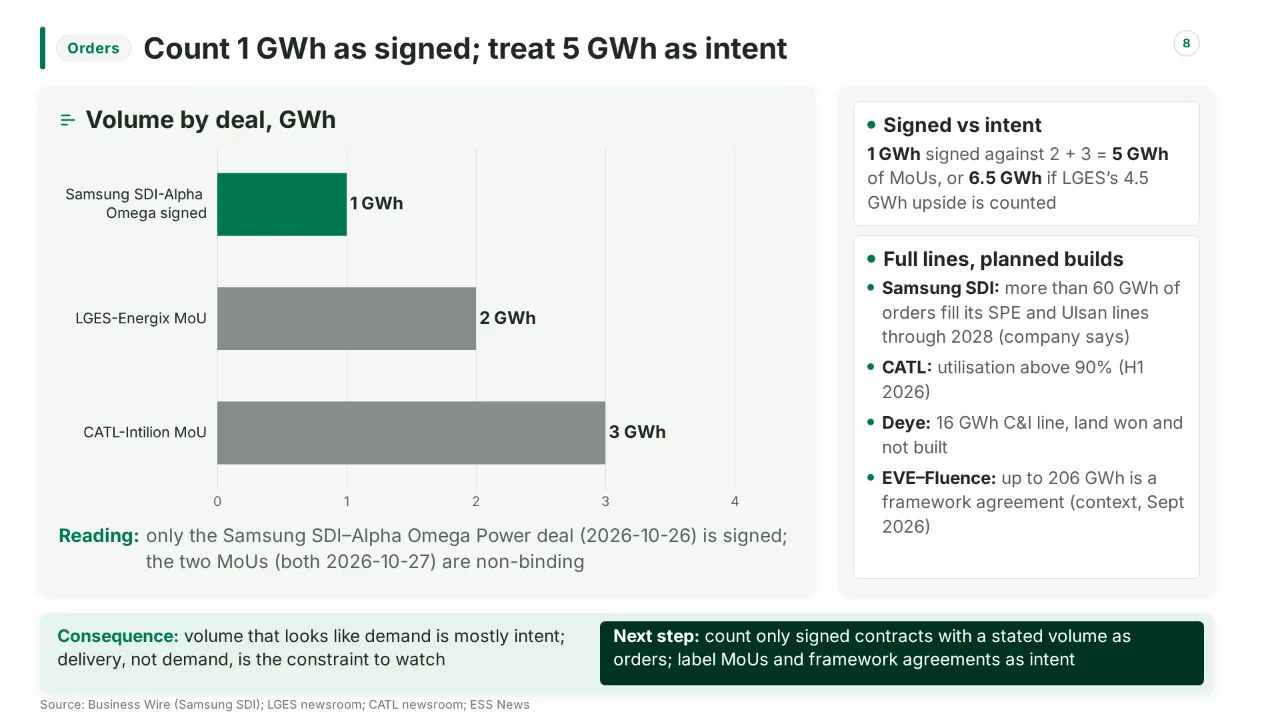
5. Orders and projects were mostly intent: pipeline outran operating capacity, and China's policy news is a draft. The only signed order with a stated volume was Samsung SDI's 1 GWh with Alpha Omega Power, while two MoUs added 5 GWh. India's CEA puts operating storage at 5.3 GWh against 185 GWh under development, and SECI issued a 4 GW / 16 GWh RfS on 28 October. NDRC's spot-market rules are a draft, open for comment to 2026-11-18, with a proposed start of 2027-01-01 [Chapters 5, 7, 8].
1.1 What moved at a glance
| Item | Value | Date | Source |
|---|---|---|---|
| SMM battery-grade lithium carbonate, spot average | RMB 100,050/t (97,700–102,400) | 28 Oct 2026 | SMM |
| SMM lithium carbonate spot, approximate | Around RMB 90,000/t; about 38% below Q3 average of RMB 147,500/t | 30 Oct 2026 | SMM |
| Benchmark LFP 314 Ah cell, EXW China | US$54.21/kWh; Q3 vs end-June −1.8% | Sep 2026 (publication date not stated) | Benchmark |
| Lingwu, Ningxia shared-storage award, 1 GW / 4 GWh | CNY 3.64 bn (US$535 m); implied RMB 0.91/Wh; contract unsigned | Award notice 26 Oct 2026 | ESS News |
| Samsung SDI Q3 revenue / ESS orders | KRW 4.69 tn (+52.6%) / 60 GWh (nine months) | 29 Oct 2026 | ESN |
| EVE Energy storage-cell shipments | 67.52 GWh, nine months (+39.46%) | 23 Oct 2026 | ESS News |
| Sungrow nine-month net profit | RMB 6.599 bn (−44.46%) | 30 Oct 2026 | Cailian via moomoo |
| SECI standalone BESS RfS (Rajasthan, Gujarat) | 4 GW / 16 GWh; RfS issued | 28 Oct 2026 | SolarQuarter |
| NDRC draft Basic Rules for Electricity Spot Markets | Comments to 18 Nov 2026; proposed start 1 Jan 2027 | Released 19 Oct 2026 (context) | CNESS; Sohu |
2. Lithium and storage-cell prices
Chapter 1 summarised the window; this chapter follows the first thread, lithium carbonate's next leg down, and asks how much of it reached storage-cell prices.
2.1 Lithium carbonate: timeline and drivers
Table 2-1. Battery-grade lithium carbonate, 2026 (RMB/t; "window" = 23 Oct–2 Nov)
| Date | Value | Type and publisher | Window? |
|---|---|---|---|
| 13 May | Spot high 200,500 (SMM); GFEX benchmark-contract high 210,580 (Market Index) | Spot; futures | Context |
| Q3 | Average 147,500 (Q2: 171,900; −14.2% QoQ) | SMM spot quarterly average | Context |
| 22 Oct | GFEX benchmark close 94,180 | Futures, Market Index | Context |
| 23 Oct | GFEX benchmark close 97,280 | Futures, Market Index | Window |
| 26 Oct | Avg 98,300 (96,400–100,200); LC2701 settlement 95,280 (+1.58%) | SMM spot; futures | Window |
| 27 Oct | Avg 99,350 (97,000–101,700); LC2701 close 98,500 | SMM spot; futures | Window |
| 28 Oct | Avg 100,050 (97,700–102,400); LC2701 close 93,300, settlement 96,460 | SMM spot; futures | Window |
| 30 Oct | "Around 90,000" | SMM spot, approximate | Window |
| 2 Nov | Spot "edged down by 100"; level not in the material | SMM headline | Window |
Core claim: Spot carbonate bounced for three sessions to RMB 100,050/t on 28 October, then fell to about RMB 90,000/t by 30 October, roughly 38% below SMM's Q3 average. Brokers see no early recovery, while the only cell series in the material fell just 1.8% in Q3.
The three-day rebound was technical. On 28 October LC2701 (SMM's most-traded contract) hit 101,520, fell to 92,320 and closed at 93,300, a 9,200 range, on volume up 17.6% to 398,200 lots and open interest up 9,791 to 448,900. SMM read this as bears in control, with upside "likely capped". Futures and spot answer different questions: SMM's spot figure is a quote-range average, and futures settlement differs from the close (96,460 vs 93,300 on 28 October). Market Index's 23 October close (97,280) does not reconcile with SMM's series, which implies a 23 October settlement of 93,800 (95,280 − 1,480). The contract month in Market Index's series is not stated, so this chapter follows SMM for 26–28 October.
Drivers, per the material: ore arrivals are rising and cathode schedules are weakening. Bald Hill and Finniss are returning, and a Mt Marion expansion is approved. Argentina's September carbonate exports were 10,600 t (+25.99% month on month, SMM flash, 2 November). Broker views are estimates, via Market Index:
| Broker (date) | Demand growth 2026 / 2027 | Other view | Source |
|---|---|---|---|
| UBS, Sky Han (26 Oct) | 26% / 19% | BESS destocking is the key driver; supply growth ~18% to 25%; no rebound before year-end; cost support ~RMB 80,000/t | Market Index |
| Canaccord (23 Oct) | 29% / 16% | 2026 demand raised 14% to 1.8 Mt LCE on BESS; mine supply +1.35 Mt LCE to 2030 | Market Index |
Macquarie, also cited by Market Index, sees GFEX near the cost curve's upper end (~105,000) and the next support near 80,000. The material has no Canaccord spodumene forecast. It gives only SC6 spot at US$1,540/t on 22 October (context).
2.2 Storage-cell prices: what the material supports
The material contains no InfoLink or SMM weekly quotes for 100, 280 or 314 Ah cells dated in the window. The InfoLink pages retrieved are 2020 and 2021 archive items, and SMM's daily reviews cover carbonate only. The weekly table is therefore not built. The one dated cell series is Benchmark's Q3 2026 review. Its publication date is not stated, and it covers July–September, so it is context.
Table 2-2. Benchmark LFP prismatic 314 Ah cell prices (US$/kWh)
| Month, 2026 | EXW China | CIF Europe | CIF North America |
|---|---|---|---|
| Jul | 57.75 (+4.6%) | 67.11 (+4.3%) | 64.99 (+4.4%) |
| Aug | 53.15 (−8.0%) | −7.4% | −7.6% |
| Sep | 54.21 (+2.0%) | 62.97 (+1.3%) | 64.78 (+7.4%) |
| Q3 vs end-June | −1.8% | −2.2% | −4.1% |
All figures are from Benchmark. Its Sep change leaves CIF North America about 20% above EXW China and Europe about 16%, which Benchmark attributes to China-to-US freight. Standard LFP prismatic cells in China fell 5.1% to 57.37, and the global Li-ion price fell 4.0% to 71.85. At RMB 6.80/US$, implied by ess-news converting CNY 3.64 bn to US$535 m, EXW China is RMB 0.393/Wh in July (57.75 × 6.8 ÷ 1,000) and RMB 0.369/Wh in September. TD Research's July tender-award cell price was about RMB 0.39/Wh (range 0.37–0.43). That is a consistency check only, since tender awards and assessed ex-works prices are defined differently (see Chapter 3).
2.3 Why cells move more slowly than lithium
Between SMM's Q2 and Q3 averages carbonate fell 14.2%, while EXW 314 Ah fell 1.8%, about one-eighth as much. The bases differ (quarterly average vs quarter-end), so read this as an order of magnitude. Four mechanisms appear in the material.

- Lag. Benchmark says July's cell spike reflected June's lithium. The 16 September carbonate drop came too late for the 30 September assessment, so it expects lagged cuts in Q4.
- Margin gradient. SMM's H1 gross margins: lithium mining up to 74%, salt processing 27–42%, cathode 5–14%, cells 12–23%. Q3 single-quarter profit fell 43% (Tianqi), 68% (Ganfeng) and 83% (Tianhua) quarter on quarter, while Salt Lake, with its own low-cost resources, fell about 12%.
- Inventory and contracts. Dynanonic's inventory was RMB 2.26 bn, up 82% since the start of the year. Its operating cash flow was −RMB 2.14 bn for nine months despite a 213% profit rise. SMM notes that goods shipped at locked prices may later reverse impairments. Buyers also waited for long-term contract arrivals. SMM adds that to hold revenue after a one-third price fall, volume must rise nearly 50% (1 ÷ (1 − 1/3) = 1.5).
- Policy floors. A 2% battery consumption tax has been in effect since 1 September 2026, and Benchmark lists whether producers absorb it as a Q4 watch item. China's pause on new cell-capacity approvals, reportedly in place since mid-May and public only in September, is under review to conclude by year-end. Intertek CEA, via ess-news (27 October), says Q2 shipments rose 18% on pre-stocking before the export VAT rebate ends on 1 January 2027 (upcoming), and expects that removal to soften cost deflation. See Chapters 3 and 5.
2.4 What it means for buyers
This is description, not procurement advice.
- Spot and cell quotes are on different clocks. Spot is about 38% below its Q3 average, but the only cell evidence is a September low of US$54.21/kWh (EXW China). How much of the October fall reaches cells is not yet observable in the material.
- Floors are estimated, not guaranteed. UBS and Macquarie both cite about RMB 80,000/t. At 90,000, that is a further 11% (90,000 → 80,000). SMM sees buyers' interest at 90,000–95,000 on 27 October.
- Terms matter as much as levels. Tax treatment, delivery basis (the North America premium) and lithium-linked pricing determine what a quote means.
- Data to watch. New InfoLink and SMM weekly cell prints, the Q4 pass-through Benchmark expects, and SMM's later daily reviews.
3. System, EPC and tender prices
Chapter 2 followed lithium carbonate and cell prices; this chapter asks how much of that move had reached systems and contracts by 2026-11-02, and finds that the window offers award values, not weekly system quotes.
3.1 System price snapshot: a thin window
The two quotes this chapter was meant to anchor on are not in the source material. These are SMM's 2026-10-23 DC-side 5 MWh price and InfoLink's 2-hour liquid-cooled system price. The InfoLink page that was retrieved is a September 2020 PV update (not storage). We therefore give no in-window weekly system price and do not backfill one. The latest China system series in the material is TD Research's July 2026 review, which is context, not a window event, and its publication date is not stated.
| Item (China) | Price | US$/kWh at RMB 6.80 | Date | Source |
|---|---|---|---|---|
| 4-hour system, weighted average | RMB 0.58/Wh (−13.4% MoM; range 0.50–0.63) | 85.3 | July 2026 data (context) | TD Research |
| 2-hour system, average | RMB 0.53/Wh | 77.9 | July 2026 data (context) | TD Research |
| Lingwu 1 GW / 4 GWh award, implied | RMB 0.91/Wh | 133.8 | Notice confirmed 2026-10-26 (window) | ESS News |
TD's headline cites a 4-hour EPC/PC price of RMB 0.54/Wh that the retrieved text does not reconcile with the RMB 0.58/Wh system average, so we use the body figures. TD projects (estimate) that the 4-hour average could fall below RMB 0.50/Wh if large projects such as the 1.2 GWh Hebei Jiaotou tender (bids RMB 0.510–0.544/Wh) clear at about RMB 0.53/Wh.
3.2 Award and tender datapoints, with the arithmetic
A consortium led by Wuhan Tianyuan won a CNY 3.64 billion tender for 4 GWh in Lingwu, Ningxia, which implies about RMB 0.91/Wh (US$0.134/Wh), but that figure covers equipment and construction, not batteries alone.
Event facts (ESS News, 2026-10-29, citing Wuhan Tianyuan's disclosure): the winning bid was published 2026-10-21 to 2026-10-23, and the company confirmed receipt of the formal award notice on 2026-10-26. No formal contract had been signed, and the split among the three consortium members was not disclosed. Award details belong to Chapter 7. The price workings are:
| Datapoint | Value | Capacity | Implied price (formula) | Status and date | Source |
|---|---|---|---|---|---|
| Lingwu, Ningxia shared storage (4 h) | CNY 3.64 bn ($535 m) | 1,000 MW / 4,000 MWh | 3.64 bn ÷ 4,000,000 kWh = RMB 910/kWh = 0.91/Wh; ÷ 1,000,000 kW = RMB 3,640/kW | Award notice, 2026-10-26; contract unsigned | ESS News |
| Ningdong, Ningxia expansion (4 h) | CNY 195 m | 75 MW / 300 MWh | 195 m ÷ 300,000 kWh = RMB 650/kWh = 0.65/Wh | Signed contract, "earlier in October" (exact date not stated; context) | ESS News |
The RMB 6.80 rate used in these tables is implied by the article's own conversion: 3,640 ÷ 535 = RMB 6.80 per US$. The Lingwu contract covers design, civil works, a new 330 kV substation, about 4 km of transmission, commissioning and grid connection, plus a two-year warranty. That is a wider scope than the Ningdong "equipment supply and installation" contract. Against TD's July 4-hour system average of RMB 0.58/Wh, Lingwu is 0.91 ÷ 0.58 = 1.57×, or +57%. Ningdong is 0.65 ÷ 0.58 = 1.12×, or +12%. The months and scopes differ, so these ratios are indicative only.
Two further window items carry no usable price. BHEL's EPC pre-bid tie-up tender for a 200 MW / 400 MWh BESS at NTPC Mouda, India, is dated 2026-10-23 with bids due 2026-11-02, and the price bids are submitted separately and not published. ADS-TEC Energy (2026-10-28) puts total investment for its 1 GW / 4 GWh Pulverdingen project, still awaiting a building permit, at "several hundred million to one billion euros". That is an investment range, not a price: €1 bn ÷ 4,000,000 kWh = at most €250/kWh, including items beyond the system (Chapter 8).
3.3 US price outlook and the export-rebate effect
According to ESS News (via pv magazine USA, 2026-10-27), Intertek CEA's ESS Price Forecasting Report (Q3 2026) projects US DC-block prices to fall about 15% to 30% by 2030, against reductions above 40% in import markets as Chinese makers move to larger cell formats. This is a forecast (estimate), reported second-hand; the report itself is not in the material. The article points to trade barriers, tightening "covered foreign entity" definitions and Section 45X compliance as the reasons for the gap.
China's battery export VAT rebate is in force at 6% and scheduled to end. Announcement No. 2 of 2026 of the Ministry of Finance and State Taxation Administration, published 2026-01-08 (context, not a window event), cut the battery rebate from 9% to 6% from 2026-04-01 to 2026-12-31 and cancels it from 2027-01-01 (upcoming). The applicable rate is set by the export date on the customs declaration. The material has only secondary reprints of the announcement, not the Ministry text. Intertek says Q2 2026 shipments of about 230 GWh (+18% QoQ) were boosted by pre-stocking ahead of the 2027-01-01 date, and expects the removal to "soften the pace of cost deflation heading into 2027".
Company statements in the window point the same way. Pylontech and Zhuhai CosMX Battery, reporting Q3 on 2026-10-23, each named export-tax-rebate changes as a profit drag (via EnergyTrend). For scale, our upper-bound estimate is: 6% × US$54.21/kWh (Benchmark's September EXW China 314 Ah cell price, Chapter 2) = about US$3.3/kWh, if the whole rebate were absorbed on the cell value. The real pass-through is not in the material.
3.4 Implications
- Award prices are the live signal: with system quotes absent, Lingwu's RMB 0.91/Wh turnkey figure and TD's RMB 0.50–0.63/Wh July system range bracket what China projects were being priced at.
- Gap to the US: Intertek's forecast implies a persistent price gap between the US and import markets through 2030.
Gaps: no SMM 2026-10-23 DC-side quote, no in-window InfoLink system quote, and no in-window CNESA or TD EPC series. This review does not give investment, procurement or legal advice.
4. Manufacturers — Q3 results and shipments
Chapter 3 covered system, EPC and tender prices; this chapter checks how that pressure appears in what manufacturers reported between 2026-10-23 and 2026-11-02. The cninfo, HKEX and KRX originals are not in the material, so every figure is company-reported but relayed by the outlet named in each row, unless marked estimate.
4.1 Results at a glance
| Company | Metric (period) | Value | YoY | Date | Source (company-reported) |
|---|---|---|---|---|---|
| Samsung SDI | Revenue (Q3) | KRW 4.69 tn (≈US$3.5 bn) | +52.6% | 2026-10-29 | ESN |
| Samsung SDI | Operating profit (Q3) | KRW 407.8 bn | n/a | 2026-10-29 | ESN |
| Samsung SDI | ESS orders (9M) | 60 GWh | n/a | 2026-10-29 | ESN |
| EVE Energy | Group revenue (Q3) | RMB 27.70 bn | +64.56% | 2026-10-23 | BigGo |
| EVE Energy | Storage-cell shipments (9M) | 67.52 GWh | +39.46% | 2026-10-23 | ESS News |
| Sungrow | Net profit attributable (9M) | RMB 6.599 bn | −44.46% | 2026-10-30 | Cailian via moomoo |
| BYD | Revenue (Q3) | RMB 221.49 bn | +13.59% | 2026-10-29/30 | TipRanks |
| BYD | Net profit attributable (Q3) | RMB 10.02 bn | +28.08% | 2026-10-29/30 | TipRanks |
Q3 split the field. EVE and BYD grew profit on higher volume, while Sungrow's nine-month profit fell 44.46% and its Q3 gross margin dropped 9.17 points in one quarter.
4.2 Samsung SDI and Korean makers
Samsung SDI announced Q3 on 2026-10-29 (the ESN article of 10-30 says "yesterday"). Revenue was KRW 4.69 tn, against KRW 3.05 tn a year earlier and KRW 3.77 tn in Q2; operating profit of KRW 407.8 bn is a margin of 407.8 / 4,690 ≈ 8.7%. The Battery Business earned KRW 361.9 bn on KRW 4.41 tn (+55.3%), which the company ties to ESS and battery-backup sales linked partly to AI data centres. The quoted growth rates do not match the rounded figures (4.69 / 3.05 = +53.8%, not +52.6%); we use the stated rates. ESN gives US$3.5 bn without a rate, implying about KRW 1,340/US$ (4.69 tn / 3.5 bn), so operating profit is roughly US$0.30 bn at that rate.
The 60 GWh is orders in nine months per ESN, not shipments or revenue, and customers are not itemised; the earnings-call highlights word it as "more than 60 GWh through October" (mostly US utility), which we treat as the same figure at a slightly later cut-off. The company said US LFP capacity reached 30 GWh a year at Q2 (context), that it will make LFP cells at its Indiana SynergyCells plant (100% owned since August), and that prismatic LFP mass production recently began at StarPlus Energy (ESN gives no date; the call highlights say early October 2026, see Chapter 5). It expects the ESS market to "maintain momentum" in Q4. The Alpha Omega agreement is in Chapter 8 and capacity lines in Chapter 5. The material has no Q3 figures dated in the window from LG Energy Solution or SK On.
4.3 Chinese makers: EVE, Sungrow, BYD and others
EVE Energy reported on the evening of 2026-10-23; ssg.events dates the CNINFO posting 10-24, and we follow 10-23. The +64.56% is group revenue (power, storage, consumer), not storage. Nine-month net profit was RMB 5.24 bn (+86.11%), but operating cash flow fell 65.37% to RMB 1.698 bn. Storage shipments of 67.52 GWh now exceed EV-battery shipments of 66.17 GWh (+91.30%). With H1 at 44.46 GWh and Q2 at 24.08 GWh, Q3 was 67.52 − 44.46 = 23.06 GWh, down (23.06 / 24.08 − 1) ≈ 4.2% on Q2. Management said Q4 capacity is fully booked and Q1 2027 schedules are not finalised (company says, 10-23). No Q3 storage margin is disclosed; the latest is H1 (context): RMB 15.09 bn revenue at 12.51% gross margin.
Sungrow reported on 2026-10-30: nine-month revenue RMB 48.863 bn (−26.41%); Q3 revenue RMB 17.95 bn (−21.51%, a narrower fall); Q3 gross margin 29.45% against 38.62% in Q2. Implied H1 revenue is 48.863 − 17.95 = RMB 30.91 bn. The material lacks Sungrow's Q3 net profit, storage GWh and the Q4 storage-shipment guidance (above 20 GWh) the blueprint expected. EnergyTrend lists Sungrow, BYD, Deye, HyperStrong and Gotion as reported, but only Sungrow's profit is visible; for Deye the material holds only its 2026-10-14 forecast (context): nine-month net profit RMB 4.22–4.32 bn, +79.81% to +84.07%.
BYD filed with HKEX on 2026-10-29 (Electrek); BitAuto says 10-30. Reuters-polled brokers expected Q3 profit of RMB 11.4–12.95 bn, so the RMB 10.02 bn result was about 12% to 23% below that estimate: (10.02 − 11.4) / 11.4 and (10.02 − 12.95) / 12.95. Nine-month revenue was flat at RMB 566.30 bn and net profit fell 4.2% to RMB 22.34 bn; Q3 exports were 550,704 vehicles (+137%) and inventory is up 60% since January. Electrek's calculated Q3 gross margin is about 18.0% (media-derived). The material has no BYD storage-segment figure.
Others. Great Power (10-26): Q3 revenue RMB 6.888 bn (+109.98%), net profit RMB 362 m (+78.55%), a net margin of 5.3%, against (1,178 − 362) / (17,866 − 6,888) ≈ 7.4% in H1; it links higher inventory write-downs to the lithium-carbonate fall and consumption tax. Kstar (10-26): Q3 net profit RMB 211 m (+10.97%). Context from the previous issue: CATL's Q3 gross margin fell from 23.15% to 20.69% (10-20); Tesla's energy revenue fell 16% on 13.7 GWh (10-21).
4.4 Rankings
CATL says SNE Research ranks it first globally in storage-battery shipments for H1 2026, a fifth straight year at the top; this is relayed on CATL's newsroom on 2026-10-26, the SNE date is not stated, and no volumes or lower ranks are given. ESS News places EVE among the three largest storage-cell suppliers with CATL and Hithium, without naming the ranking. The material contains no TD Research September ranking, so none is shown.
5. Capacity, orders and supply chain
Chapter 4 showed what the manufacturers earned in Q3; this chapter asks where their volume is going, which factories are being built for it, and which US rules decide whose cells qualify.
5.1 Order book: one signed contract, two MoUs
| Company | Customer | GWh | Type | Date | Source |
|---|---|---|---|---|---|
| Samsung SDI | Alpha Omega Power (US IPP) | 1.0 new; 1.5 cumulative | Signed contract, value not disclosed | 2026-10-26 | Business Wire |
| LG Energy Solution | Energix (Israel-HQ developer) | ~2 (1.5 Europe + 0.5 US) over 24 months; talks on 4.5 | Non-binding MoU | 2026-10-27 | LGES newsroom |
| CATL | Intilion (Germany, Switzerland, Austria) | 3 over 5 years | MoU | 2026-10-27 | CATL newsroom |
| EVE Energy | Fluence | up to 206 (16 firm 2027 + 190 reserved 2028–31) | Framework agreement; context | Sept 2026 | ESS News |
In the window, the only order with a stated volume that was a signed contract was 1 GWh. The two MoUs add 5 GWh (2 + 3) of non-binding intent, or 6.5 GWh if LGES's 4.5 GWh upside is counted.
The AOP cells come from the StarPlus Energy (SPE) plant in Kokomo, Indiana, for delivery by end-2026. SMM and SolarBytes describe the LGES deal as "up to 4.5 GWh by 2028"; the company release says about 2 GWh over 24 months with 4.5 GWh only under discussion, and we follow it. The Intilion headline mentions sodium-ion, but the body names only CATL's Tener systems, so the chemistry of the 3 GWh is not stated. CATL's Tener+ launch on 2026-10-28 disclosed no order (see Chapter 6). EnergyTrend roundup headlines ("nearly 2.2 GWh", 2026-10-26; "over 3.3 GWh" overseas, 2026-10-28) lack contract status and are not added. The material has no window item on Hithium's long-duration cell orders.
5.2 Capacity moves: top-tier lines are full, many expansions are plans
| Company | Site | Capacity | Stage (vs 2026-11-03) | Date | Source |
|---|---|---|---|---|---|
| Deye Energy Storage | Cixi Binhai | 16 GWh C&I line (7 + 9 GWh phases) | Phase II land won for RMB 103.587m; agreement signed 2026-06-23; not built | Announced 2026-10-22 (context); EnergyTrend 2026-10-26 | Deye via EnergyTrend |
| Samsung SDI | SPE, Kokomo, Indiana | ESS LFP line; two more from H1 2027 | Mass production since early Oct 2026 | 2026-10-29 | Call highlights |
| Samsung SDI | SynergyCells, New Carlisle (27 GWh) | ESS LFP | Wholly owned since Aug 2026; mass production plan H2 2028–early 2029 | 2026-10-29 | — |
| Gotion | Lujiang | 200,000 t/yr cathode material | Full production | 2026-10-29 | SMM |
| Sigenergy–Failte | India, site not chosen | Inverter plant, then ESS plant; size not stated | Reported, approvals in progress | 2026-10-23 | Reuters via EnergyTrend |
Samsung SDI said on its Q3 call (page dated 2026-10-29) that more than 60 GWh of orders through October keep the SPE and Ulsan lines full through 2028, and that orders for the two extra LFP lines are secured. EVE said on 2026-10-23 that Q4 capacity is fully booked. CATL says, citing PV Tech Research, that utilisation stayed above 90% in H1 2026.
Deye's "100M yuan" headline is the land price (RMB 103.587m); total project investment is not stated. Sigenergy's plan comes from an expo interview, not a company announcement; its USD 250m ≈ RMB 1.68bn implies about 6.72 RMB/US$ (1,680 / 250). The material has no window item on LG Energy Solution's North American lines or a ">50 GWh" target; its only LGES capacity figure is Intertek CEA's 33 GWh across three factories.
5.3 US supply chain and restrictions
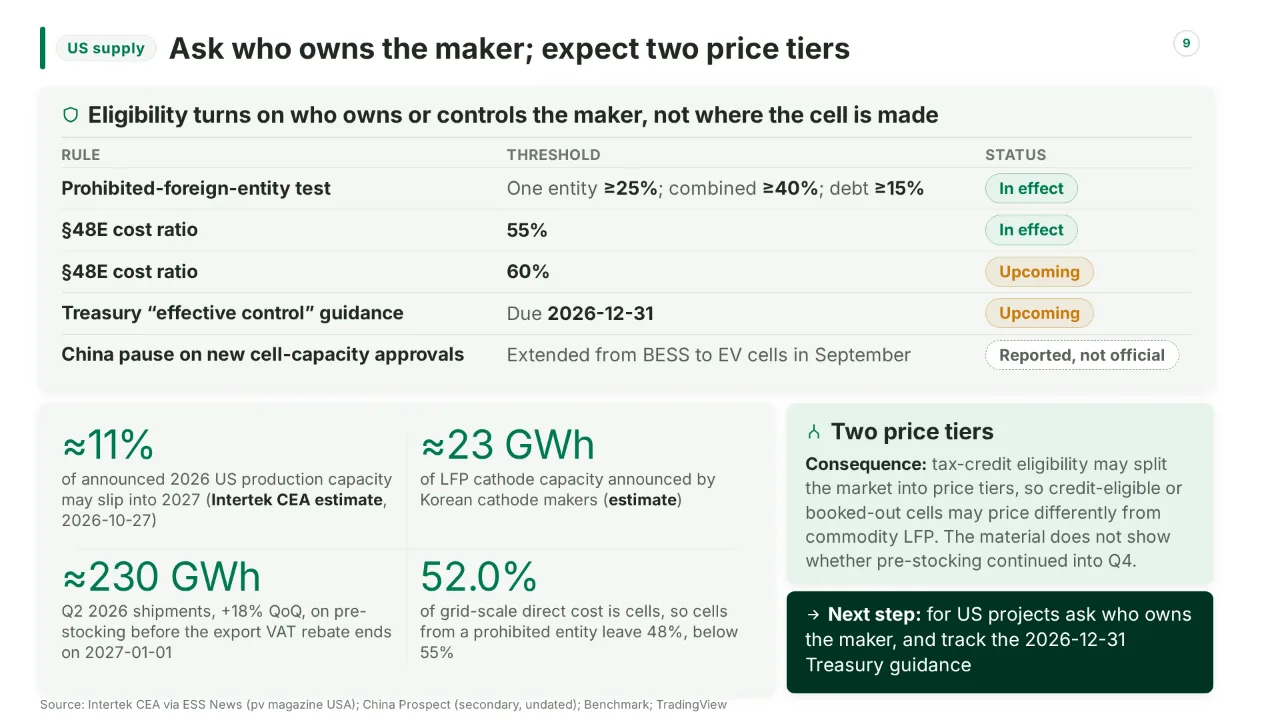
Intertek CEA's Q3 2026 report, carried by ESS News (from pv magazine USA) on 2026-10-27, says about 11% of announced 2026 US production capacity may slip into 2027 (line conversions, qualification, capital). Korean cathode makers L&F, Posco and EcoPro have announced about 23 GWh of LFP cathode capacity for 2026, enough for nearly 40% of US demand if fully realised (estimate). Because cathode is a main barrier to Section 45X compliance, Intertek expects tax-credit eligibility to split the market into price tiers.
| Rule | Threshold | Status on 2026-11-03 | Source |
|---|---|---|---|
| Prohibited foreign entity (PFE) test; "FEOC" is the older term | One specified entity ≥25%; combined ≥40%; debt ≥15%; licence signed or amended on or after 2025-07-04 | In effect | China Prospect |
| Material assistance cost ratio, §48E storage | 55% (construction begins 2026); 60% (2027) | 55% in effect; 60% upcoming | China Prospect |
| Treasury "effective control" guidance | Due 2026-12-31 | Upcoming; none published when page checked | China Prospect |
China Prospect is secondary and undated. The test turns on who owns or controls the maker, not where the cell is made. Cells are 52.0% of grid-scale direct cost in the IRS interim table, so cells from a PFE leave a ratio of 100 − 52.0 = 48%, below 55% (the source's arithmetic). The LGES–Energix MoU contemplates US-made FEOC-compliant systems; Samsung SDI says it is the only non-Chinese prismatic ESS supplier in North America (company says). On Section 301, the material gives no storage-cell rate: a handbook blurb mentions "Section 301 forced labor duties of July 2026" without a number, and Intertek calls further tariffs "potential".
5.4 What over-capacity and pre-stocking mean for prices
China's pause on new cell-capacity approvals was first limited to BESS and extended to EV cells in September, within a review of total battery capacity expected to conclude by year-end, according to Benchmark. TradingView says the freeze began in mid-May and became public in September, citing Macquarie's concern that cell makers cut output further in November and December (broker view). The material holds no official document, so the pause is reported.
Pre-stocking is the other distortion. Intertek CEA counts about 230 GWh of Q2 2026 shipments among tracked suppliers, up 18% on Q1 (implied Q1 ≈ 230 / 1.18 ≈ 195 GWh), driven by buying ahead of the battery export VAT-rebate end on 2027-01-01. The rebate fell from 9% to 6% on 2026-04-01 and is cancelled from 2027-01-01 (MoF/STA Announcement No. 2 of 2026, via TKG). The material has no window-dated shipment data showing whether pre-stocking continued into Q4.
The result is two markets. Full order books at Samsung SDI, EVE and CATL give tier-1 suppliers pricing room, while Benchmark expects lagged lithium declines still to reach cell quotes (see Chapter 2). Credit-eligible or booked-out cells may therefore price differently from commodity LFP.
6. Technology — solid-state, sodium-ion and beyond lithium
Chapter 5 tracked the capacity and orders filling today's lithium-ion lines; this chapter asks which technologies beyond them moved between 23 October and 2 November 2026, and at what stage.
6.1 Readiness table
| Technology | Company | Milestone | Stage (as of 2026-11-03) | Date | Source |
|---|---|---|---|---|---|
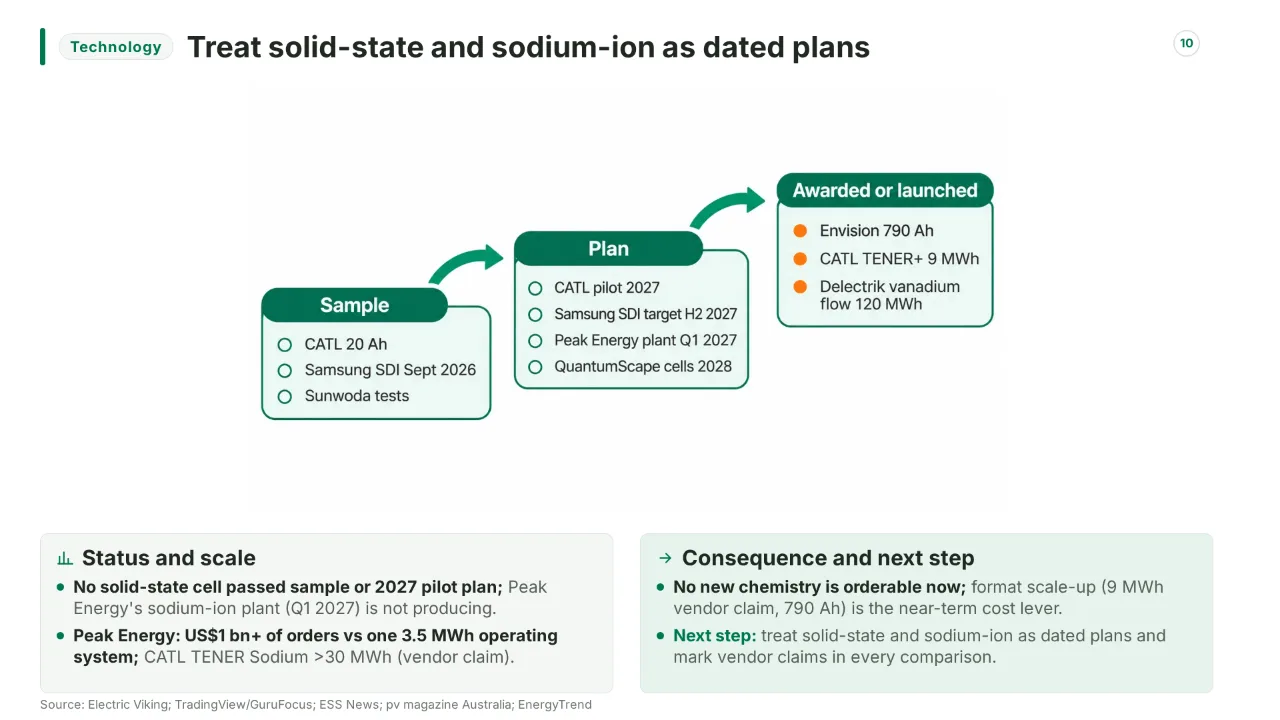
| All-solid-state (sulfide) | CATL | 20 Ah samples; small-batch pilot 2027 | Sample; pilot planned | 2026-10-27 | Electric Viking |
| All-solid-state | Samsung SDI | Samples Sept 2026; humanoid target H2 2027 | Sample (customer evaluation) | 2026-10-29 | TradingView/GuruFocus |
| Solid-state (polymer) | Sunwoda | Customer sample testing | Sample | 2026-10-30 | XenoSpectrum |
| Sulphide electrolyte | Solid Power | MOBIUS 45 mt/yr line | Commissioning; operation Q4 2026 | 2026-10-26 | SMM |
| Lithium sulfide | Tianqi Lithium | 50 mt/yr pilot line | Under construction; end-2026 plan | 2026-10-28 | SMM |
| Solid-state Li-metal | QuantumScape | 100 MWh line, cells from 2028 | Plan (pilot line operating) | 2026-10-21, context | EnergyTrend |
| Sodium-ion BESS | Peak Energy | 4 GWh Sacramento plant | Plan; production Q1 2027 | 2026-10-21 (context); reported 10-23 | ESS News |
| Sodium-ion BESS | CATL TENER Sodium | >30 MWh per system | Vendor claim: mass-produced | 2026-10-28 | pv magazine Australia |
| Large-format LFP | Envision AESC | 790 Ah cell, Renqiu tender win | Awarded; commissioning end-2026 | 2026-10-29 | EnergyTrend |
| 9 MWh container | CATL TENER+ | Global launch | Launched (vendor claim) | 2026-10-28 | pv magazine Australia |
| Vanadium flow | Delectrik | 20 MW/120 MWh, 6 h | Awarded | 2026-10-27 | Energy-Storage.news |
Core claim: in this window no solid-state cell went beyond the sample stage or a 2027 pilot plan, and sodium-ion advanced mainly as demonstration slices and a US plant not yet built. The concrete gains were in format: a 9 MWh container and a 790 Ah cell.

6.2 Solid-state: samples, pilot lines and dated targets
CATL told investors on its Shenzhen Stock Exchange platform on 27 October that pilot production starts in 2027; it has moved from a 10 Ah-class platform to 20 Ah samples with a team of over 1,000. The company says it targets about 500 Wh/kg and about 1% initial penetration. That density is not confirmed as a production specification, and no customer, output or vehicle date was disclosed. The "level 4 of 9" remark is not new: Notebookcheck attributes it to chairman Zeng Yuqun at Summer Davos, and Electrek (via UA.NEWS) dates it to June. Electrek calls the 20 Ah cells "pilot production"; other sources say samples, which we follow. East Asia Brief's uncorroborated extra details are not used.
Samsung SDI is the only maker in the window describing customer evaluation. On its Q3 call (page dated 29 October) EVP Han Jae Cho said cell and pack samples went to humanoid customers in September 2026, with commercialisation targeted for H2 2027. According to SMM, citing foreign media on 25 October, the target is 900 Wh/L, about 40% above liquid-electrolyte cells at roughly 650 Wh/L (900 ÷ 650 = 1.38), from a 6,500 m² Suwon pilot line; LG Energy Solution has pushed graphite-based solid-state to 2029. Sunwoda said on 30 October that design and process verification is complete and customer sample tests are under way, according to XenoSpectrum citing IT Home. It gave no customers, volumes or mass-production date, against a July 2024 outlook of 2026 mass production at 1 GWh; only a 0.2 GWh sample line is confirmed, one-fifth of that.
The materials chain moved too. Solid Power said on 26 October that its MOBIUS electrolyte line in Thornton, Colorado began commissioning: 45 mt/yr, taking SP2 capacity to about 75 mt/yr, a 150% rise (so 30 mt/yr before; 45 ÷ 30 = 1.5), with operation planned for Q4 2026. Tianqi Lithium said on 28 October that its 50 mt/yr lithium sulfide pilot will complete by end-2026, with samples at over 30 clients. QuantumScape's 100 MWh line (21 October, context) is a construction plan.
Judgement: every solid-state item here is a sample, pilot line or dated target; none is capacity a storage buyer can order.
6.3 Sodium-ion: backlog ahead of output
Peak Energy announced a US$108 m Series B led by GM Ventures on 21 October (context); ESS News reported it on 23 October. The 4 GWh Sacramento plant (capex about US$71 m, or US$17.75 per kWh of annual capacity: 71 ÷ 4,000) starts production in Q1 2027, and today's cells come from Chinese makers to Peak's specification. Peak says it holds over US$1 bn of orders, undisaggregated: Jupiter Power up to 4.75 GWh over 2027–2030, Energy Vault 1.5 GWh, and an RWE pilot. The only operating system is 3.5 MWh at SolarTAC since September 2025; Jupiter's maximum alone is about 1,360 times that (4,750 ÷ 3.5). The up-to-20% lower cost of energy is unverified.
CATL showed TENER Sodium in Australia for the first time at All-Energy on 28 October. CATL says it exceeds 30 MWh per system, with more than 10,000 cycles at 45 °C, 95% round-trip efficiency, over 20 years' life and over 10% lower total EPC cost than LFP containers — vendor claims. Elsewhere, Envision's Renqiu 100 MW/400 MWh tender win (29 October) is a 90% LFP / 10% sodium hybrid due by end-2026; the material does not say whether the split is by energy. The material has no dated Naxtra item in the window.
6.4 Long-duration and cell-format trends
CATL's TENER+ had its global launch at All-Energy Australia on 28 October: about 9 MWh per liquid-cooled container with a 25-year design life. CATL says it needs 40% fewer containers and a 35% smaller footprint. Against the 5 MWh containers Narada and Hysea deployed, 9 MWh gives 1 − 5/9 = 44% fewer containers; CATL's 40% implies a baseline near 5.4 MWh (9 × 0.6), so the claim is consistent.
On cells, Envision AESC's 790 Ah prismatic wound cell exceeds 2.5 kWh per cell, implying about 3.2 V (2,500 ÷ 790). Our material contains no dated Hithium 1,175 Ah or 1,300 Ah item, so we cannot place them. Beyond lithium, Delectrik was awarded a 20 MW/120 MWh six-hour vanadium flow project by GIPCL in Gujarat (27 October); Bondada reported a 20 MW/120 MWh EPC contract on 23 October, and the material does not say how the roles relate.
Judgement: format scale-up is the near-term cost lever; sodium-ion and solid-state remain dated claims, not procurement options.
7. China projects, tenders and policy
Chapter 6 covered which cell technologies are nearing production; this chapter turns to the Chinese projects and rules that decide where those cells get bought.
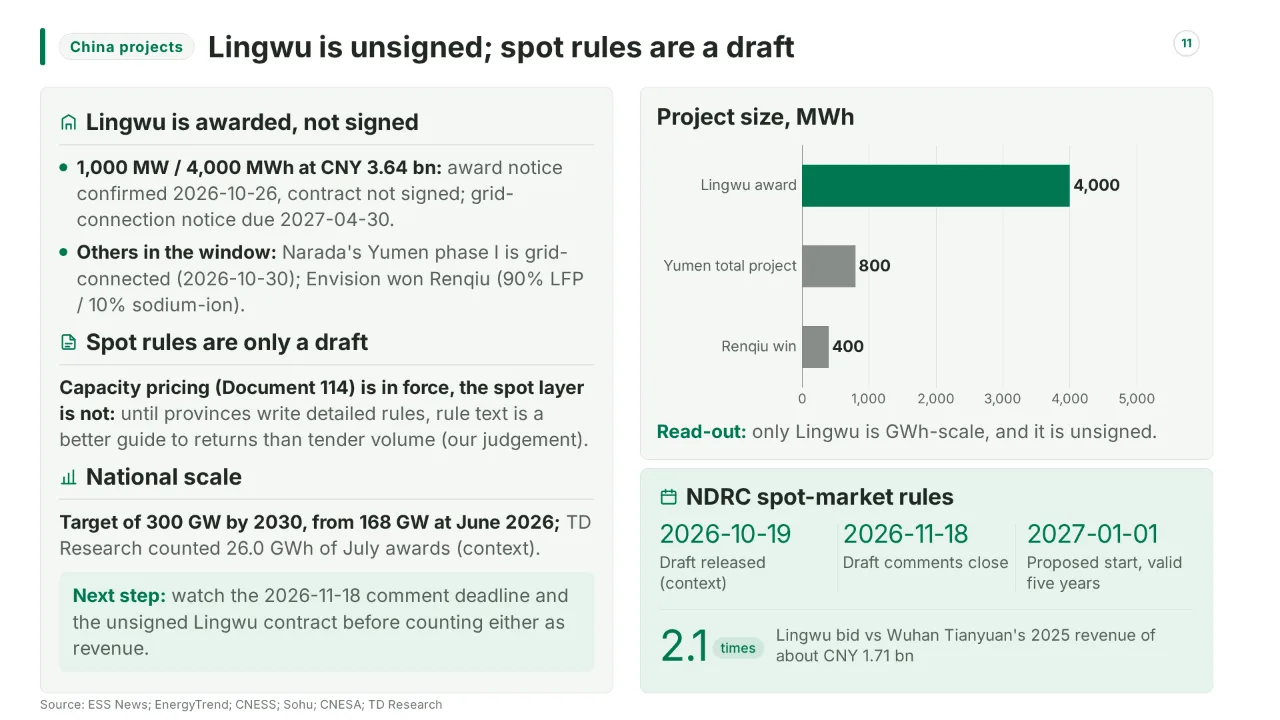
Core claim: the window holds one GWh-scale China award, the 1 GW / 4 GWh Lingwu project at CNY 3.64 billion, and its contract is still unsigned. The policy news is a draft: NDRC's spot-market rules, open for comment until 2026-11-18, proposed to start 2027-01-01. Neither is yet revenue.
7.1 Awards and tenders
| Project | Owner / winner | MW / MWh | Value | Date and status | Source |
|---|---|---|---|---|---|
| Lingwu, Ningxia, shared storage | Owner Lingwu Huaxin Comprehensive Energy Service; Wuhan Tianyuan-led consortium | 1,000 / 4,000 | CNY 3.64 bn (US$535 m) | Award notice confirmed 2026-10-26; contract not signed | ESS News |
| Renqiu, Hebei, standalone | Envision Energy Storage (LFP system) | 100 / 400 | Not stated | Win announced 2026-10-29; completion planned end-2026 | EnergyTrend |
| Yumen, Gansu, standalone shared | Narada Power (builder, cell supplier) | 200 / 800 (phase I 100 / 400) | Not stated | Phase I grid-connected, announced 2026-10-30 | EnergyTrend |
Lingwu is the window's largest award. A consortium of Wuhan Tianyuan (lead), Inner Mongolia Yinhe Electric Power Installation Engineering and Ningxia Communications Construction won the equipment supply and installation tender. The winning bid was published between 2026-10-21 and 2026-10-23, and Wuhan Tianyuan, Shenzhen-listed, confirmed the award notice on 2026-10-26. The scope covers equipment, design, civil works, commissioning, grid connection and a new 330 kV substation; chemistry and cell supplier are undisclosed. Grid-connection notice is due by 2027-04-30 and acceptance by 2027-10-30, with a two-year warranty.
The value works out at CNY 3.64 bn ÷ 4,000 MWh = CNY 0.91/Wh. This is an implied price for equipment plus construction, not a cell or system price. The US$535 m conversion implies about 6.80 CNY/US$ (3.64 ÷ 0.535); ESS News gives US$0.134/Wh. Chapter 3 compares it with other price series. The bid is 2.1 times Wuhan Tianyuan's 2025 revenue of about CNY 1.71 bn (3.64 ÷ 1.71). The company itself warns that payment terms are open, the split among consortium members is undisclosed, and the project may change or be delayed. Context: earlier in October (date not stated) a Wuhan Tianyuan subsidiary signed CNY 195 m for a 75 MW / 300 MWh Ningdong expansion, or CNY 0.65/Wh (195 m ÷ 300 m Wh) at a smaller scope.
The 2 November EnergyTrend "order" roundup is mostly agreements, not orders. Of its seven firms, only Envision's Renqiu win and Narada's Yumen grid connection are China projects. Renqiu is billed as one of China's first standalone demonstrations mixing LFP (90%) and sodium-ion (10%), with 790 Ah cells. Hoenergy signed a strategic cooperation agreement with Octopus Energy on 2026-10-30, covering equipment, digital energy and virtual power plants. It states no volume or value, so it is not an order.
The 30 October HKEX prospectus is RelyEZ's, and the material does not describe its business. RelyEZ Energy Storage Technology (stock code 9621) opened a global offering on 2026-10-30: 57,540,500 H shares at HK$8.54 to HK$11.10, or up to about HK$639 m at the top price (57,540,500 × 11.10). The offer closes 2026-11-04, pricing is expected 2026-11-05 and dealing 2026-11-09 (all upcoming). Proceeds are earmarked 45% R&D, 25% overseas expansion, 20% a Wuzhen factory and 10% working capital. The pages in the material give no GWh or standalone exposure, so we do not call it a standalone-storage issuer.
7.2 Policy changes and status
| Policy | What it does | Status at 2026-11-03 | Source |
|---|---|---|---|
| NDRC draft Basic Rules for Electricity Spot Markets | Supports joint bidding by renewables and co-located storage (Art. 8); names new-type storage as a market entity; nodal pricing; daily clearing, monthly billing | Draft, released 2026-10-19 (context); comments to 2026-11-18 (upcoming); proposed start 2027-01-01, valid five years | Southern Energy Observer via CNESS; CSPPLAZA via Sohu |
| NDRC Document 136 (2025) | Storage no longer a precondition for new-energy approval or grid connection | In effect | CNESA |
| NDRC Document 114 (2026) | First national recognition of capacity value for new-type storage | In effect; issue date not stated | CNESA |
| MOF/STA Announcement No. 2 (2026) | Battery export VAT rebate 9% to 6% from 2026-04-01; cancelled from 2027-01-01 | 6% in effect; cancellation upcoming | TKG China reproduction |
| 2% consumption tax, lithium-ion batteries | Domestic levy | In effect since 2026-09-01 | Benchmark |
The material does not contain NDRC's own announcement. Everything about the draft comes from trade and financial press, and a developer's web page repeats the dates. The draft makes joint bidding something NDRC "supports", not a requirement. Its economics will depend on provincial rules covering registration, revenue split and deviation penalties. Nodal pricing as the default (Art. 23) and a shift from difference-quantity to price-difference settlement (Art. 48) would widen the price spread that storage earns, and the draft also adds ramping as an ancillary service (Art. 42). Securities Daily frames this as three stacked revenue lines (energy, capacity, ancillary services) and lists open questions: capacity conversion, charge-discharge loss allocation and penalty responsibility.
Two timing points. The 2023 rules' stated validity ended 2026-10-15, yet the successor would start only on 2027-01-01, and the material does not say what applies in between. The southern regional spot market was planned to enter formal operation on 2026-10-24, but the material does not confirm that it did.
7.3 Market statistics
The material holds no TrendForce or CNESA monthly tender or award figure for September or October 2026, so none is shown. The one monthly series is TD Research's July review, which is context and carries no event date. It reports 26.0 GWh awarded, down 32.9% month on month and up 45.8% year on year. That implies a June base of about 38.7 GWh (26.0 ÷ 0.671). Four-hour projects took 61.6% of awarded capacity and average duration rose to 2.85 hours from 2.68 a year earlier. TD Research counts awarded project capacity; its prices belong to Chapter 3.
CNESA measures a different thing, installed capacity. In an interview dated 2026-10-12 (context), CNESA chairman Chen Haisheng gave 168 GW of cumulative new-type storage at June 2026. The interview's lead-in says "over 150 GW, +61%"; we follow the dated CNESA statistic. The July 2026 15th Five-Year Plan for the new power system sets 300 GW by 2030, with grid-side standalone storage adding 80 GW to 140 GW. From 168 GW, that means about 132 GW (300 − 168) over the remaining 4.5 years, roughly 29 GW a year. This is arithmetic on a target, not a forecast.
Our judgement: capacity pricing (Document 114) is in force, but the spot-market layer is not. Until provinces write detailed rules, rule text is a better guide to project returns than tender volume.
8. Overseas markets
Chapter 7 followed China's award and tender flow; outside China, the news of 23 October to 2 November 2026 shows the same gap between announced and operating capacity, so the tracker below keeps the stages apart.
| Project | Country | MW / MWh | Developer / supplier | Stage | Date | Source |
|---|---|---|---|---|---|---|
| SECI standalone BESS, Rajasthan + Gujarat | India | 4,000 / 16,000 | SECI (buyer); bidders open | RfS issued | 2026-10-28 | SolarQuarter |
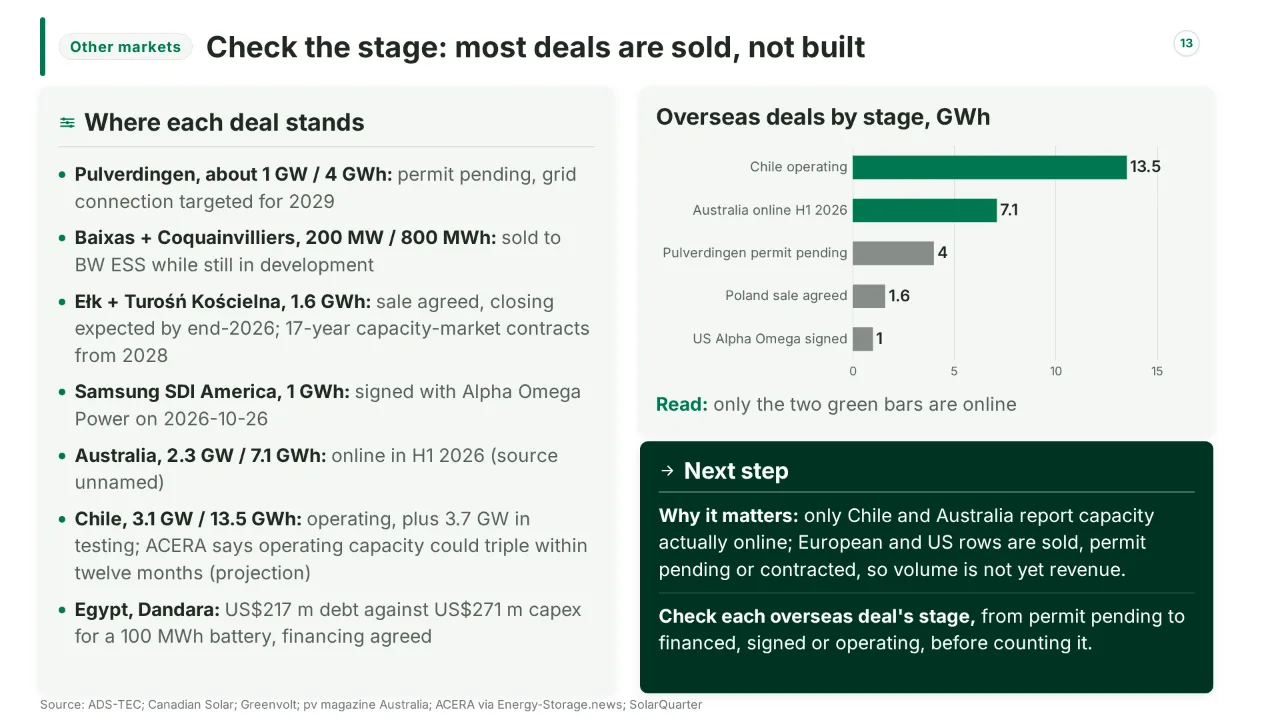
| Pulverdingen | Germany | ~1,000 / 4,000 | ADS-TEC Energy | Permit pending | 2026-10-28 | ADS-TEC (Business Wire) |
| TNPDCL solar + storage, Tranche XXI | India | 300 / 1,800 | TNPDCL via SECI | Regulator approved | order 2026-10-22 | SolarQuarter |
| Ełk + Turośń Kościelna | Poland | 400 / 1,600 | Greenvolt to A&R Investments | Built; sale agreed, not closed | 2026-10-23 | Greenvolt |
| ACME FDRE, Bikaner | India | 300 / 1,200 | ACME Solar | 781.4 MWh commissioned | 2026-10-29 | SolarQuarter |
| Samsung SDI supply to Alpha Omega Power | US | n/a / 1,000 | Samsung SDI America | Signed contract | 2026-10-26 | Samsung SDI (Business Wire) |
| Baixas + Coquainvilliers | France | 200 / 800 | Recurrent Energy to BW ESS | Sold; still in development | 2026-10-29 | Canadian Solar (PR Newswire) |
| GIPCL Vadodara flow battery | India | 20 / 120 | Bondada (EPC); Delectrik (flow-battery start-up) | EPC awarded (Bondada); award confirmed (Delectrik) | 2026-10-23 / 27 | SolarQuarter; ESN |
| Dandara phase 1 | Egypt | n/a / 100 (+569 MW solar) | Scatec | Financing agreed | 2026-10-29 | SolarQuarter |
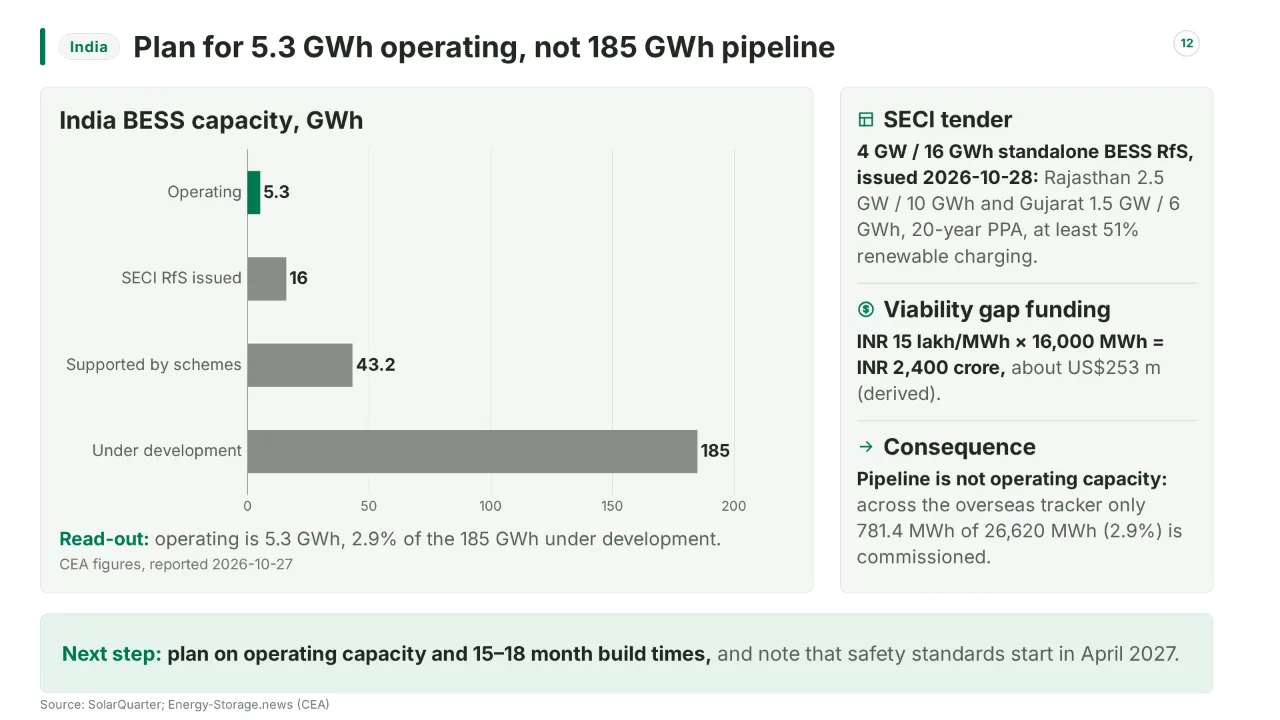
The tracker totals 26,620 MWh (ACME at its planned 1,200 MWh), of which only 781.4 MWh (2.9%) is commissioned. Every other row is tendered, permit-pending, financed, contracted or sold: pipeline is not operating capacity.
8.1 India: tenders outrun the fleet
On 28 October 2026 SECI issued an RfS for standalone BESS on a build-own-operate basis, according to SolarQuarter (the RfS itself is not in the material). Status: RfS issued. Package I is 2.5 GW / 10 GWh in Rajasthan and Package II 1.5 GW / 6 GWh in Gujarat, so 4 GW / 16 GWh in total, a four-hour design. Terms are a 20-year PPA with SECI, viability gap funding (VGF) of INR 15 lakh/MWh and at least 51% renewable charging power. VGF arithmetic: INR 15 lakh × 16,000 MWh = INR 2,400 crore (INR 24 bn), about US$253 m at the roughly INR 95/US$ implied by Energy-Storage.news' conversion of INR 90 bn to US$947.6 m (derived). Submission dates sit in a Notice Inviting Tender the material does not reproduce.
Operating capacity is small. Speaking at Energy Storage Summit India (reported 27 October), CEA's Prashant Bhamu put India at 5.3 GWh operating against 185 GWh under development; 5.3 ÷ 185 = 2.9%. SolarQuarter's 23 October page instead cites about 9.3 GWh installed, with no definition. We follow the CEA official. Bhamu said VGF of INR 90 bn supported 13.2 GWh (4 GWh was expected) and a separate 30 GWh scheme brings supported capacity to 43.2 GWh. Energy storage obligations for distribution utilities rose from 1% to 4%, and safety standards start in April 2027 (upcoming). SECI's Sivakumar Vopakomma said bidders per tender grew from six or seven to more than 20, but construction takes 15–18 months.
Individual projects show the stages. ACME Solar's Bikaner FDRE project reached 195.35 MW / 781.40 MWh, 65.1% of its planned 300 MW / 1,200 MWh, after a 35.77 MW / 143.08 MWh tranche with a scheduled COD of 29 October. TNERC's order of 22 October (one day before the window, reported 26 October) approved TNPDCL's purchase of 600 MW solar with a 300 MW / 1,800 MWh system (six hours) at INR 3.12/kWh plus a INR 0.07 SECI margin, or INR 3.19/kWh, on a 25-year PPA. Bondada Engineering won the EPC contract for a 20 MW / 120 MWh vanadium flow battery for GIPCL at Vadodara, with completion due 18 months from the notification of award; Delectrik separately confirmed its own award in the same GIPCL solicitation on 27 October; the material does not state how the two roles relate.
8.2 Europe: asset rotation, not new orders
ADS-TEC Energy said on 28 October that the authority confirmed its application for the Pulverdingen plant (about 1 GW / 4 GWh) complete and expects the permit shortly. Status: permit pending; construction has not started. Grid connection is targeted for 2029, and ADS-TEC intends to sell a majority stake in the project company. On 29 October Recurrent Energy (Canadian Solar) announced the sale of two 100 MW / 400 MWh projects, Baixas and Coquainvilliers, to BW ESS. The price is undisclosed. Recurrent keeps leading development to ready-to-build, so this is sold, not built. It is BW ESS's entry into France.
On 23 October Greenvolt agreed to sell the Ełk and Turośń Kościelna projects in Poland (2 × 200 MW / 800 MWh = 1.6 GWh) to A&R Investments, with closing expected by end-2026. Both were completed in Q3 2026 and hold 17-year capacity-market contracts from 2028, paying for 85% of rated capacity, plus 10-year tolling. The material has nothing dated in the window on Portugal's grid-access tender, Italy's MACSE derating, Bulgaria or Germany's nine-month installations.
8.3 Australia: conference confidence, delivery data
All-Energy Australia (Melbourne, 28–29 October) drew over 22,000 visitors, about 5,000 more than in 2025, according to organiser RX Global via pv magazine. The same article reports over 550,000 home batteries installed in 15 months under Cheaper Home Batteries, which subsidises about 30% of cost, with growth steadying. For grid scale, nine projects (2.3 GW / 7.1 GWh) came online in H1 2026, against 2 GW / 5.1 GWh in all of 2025 (7.1 ÷ 5.1 = +39%), and 13 projects (1.6 GW / 6.5 GWh) reached financial close; pv magazine does not name the source of these figures. Commercial storage is the next target. The SRES cap rose from 100 kW to 1 MW on 1 October (in effect), cutting qualifying upfront cost by about 20%. Sigenergy launched a 401 kWh C&I cabinet; its claim of 54.5 m² per 4 MWh is a vendor claim. CATL's 9 MWh TENER+ debut is covered in Chapter 6.
The material contains no CIS tender 8 result and no dated home-battery rebate step-down.
8.4 US, Chile, Middle East and Africa
Samsung SDI America signed a 1 GWh supply agreement with Alpha Omega Power on 26 October, taking the total to 1.5 GWh with a contract from late 2025. Status: signed contract. The Samsung Battery Box 1.7 uses NCA cells made at StarPlus Energy in Kokomo, Indiana, due for delivery by end-2026, with AOP construction in WECC and ERCOT starting in 2027. The 17% higher energy density than SBB 1.5 is a company claim.
In Chile, ACERA said on 26 October that 3.1 GW / 13.5 GWh is operating, with another 3.7 GW in testing while already dispatching, and operating capacity could triple within twelve months (ACERA projection).
In Egypt, Scatec signed loan agreements for phase 1 of Dandara: US$217 m non-recourse debt from EBRD, AfDB and EIB against US$271 m capex (217 ÷ 271 = 80%). Phase 1 pairs 569 MW of solar with a 100 MWh battery for Egypt Aluminium under a 25-year sovereign-guaranteed PPA, with COD targeted for H1 2028. Status: financing agreed, per SolarQuarter.
The material has nothing in the window on Saudi Arabia, Egypt's Nag Hammadi or Eskom.
9. Outlook and what to watch
Chapter 8 showed how far announced overseas capacity sits from operating capacity. This chapter turns the window into implications by reader. It adds no new facts: every figure is cited where Chapters 2–8 developed it, and none of it is investment, procurement or legal advice.
9.1 What changed, by reader
The common thread is a gap: between lithium and delivered prices, and between announcements and operating capacity.
| Reader | What changed | Implication | Evidence |
|---|---|---|---|
| Storage buyers | Lithium spot fell to about RMB 90,000/t by 30 Oct; the only cell series in the material fell 1.8% in Q3 | Spot and cell quotes run on different clocks; Benchmark expects lagged cuts in Q4, so tax treatment, delivery basis and lithium-linked terms decide what a quote means | SMM; Benchmark |
| China developers and EPC firms | One GWh-scale award (Lingwu, implied RMB 0.91/Wh, contract unsigned); NDRC spot rules still a draft | Award prices include construction scope; revenue depends on provincial rules still to be written | ESS News; CNESS; Sohu |
| Cell and system makers | Samsung SDI cites 60 GWh of orders and EVE says Q4 capacity is fully booked, while Sungrow's Q3 gross margin fell to 29.45% from 38.62% | Tier-1 cell suppliers have pricing room; margin pressure shows at integrator level | ESN; ESS News; Cailian via moomoo |
| Overseas developers | SECI issued a 4 GW / 16 GWh RfS; India has 5.3 GWh operating against 185 GWh under development | Stage matters: in the tracker only 781.4 MWh of 26,620 MWh (2.9%) is commissioned | SolarQuarter; ESN |
| US-exposed suppliers | Prohibited-foreign-entity test in effect; 55% cost ratio in effect, 60% upcoming; Intertek says about 11% of 2026 US capacity may slip to 2027 | Credit eligibility may split the market into price tiers | China Prospect; ESS News |
| Technology scouts | Solid-state at sample or 2027 pilot stage; sodium-ion plant not yet producing | None is orderable now; format scale-up (9 MWh, 790 Ah) is the near-term lever | Electric Viking; ESS News; EnergyTrend |
| Readers of company results | SMM notes that nine-month totals still carry the first-half price rise, while Q3-only profit fell 43% (Tianqi), 68% (Ganfeng) and 83% (Tianhua) | Single-quarter figures show the turn earlier than cumulative ones | SMM |
Judgement on prices. The lithium move has not finished passing through. UBS expects no rebound before year-end and both UBS and Macquarie point to support near RMB 80,000/t (estimates). Benchmark expects lagged declines to reach cell quotes. Against that, Intertek expects the end of the export VAT rebate on 2027-01-01 to soften cost deflation, and it ties Q2's 230 GWh of shipments (+18%) to pre-stocking. The material does not show whether pre-stocking continued into Q4.
Judgement on orders. The window's volume was mostly intent. One signed contract (1 GWh) sat beside two MoUs (about 5 GWh), and Samsung SDI says its SPE and Ulsan lines are full through 2028. Delivery, not demand, is the constraint to watch.
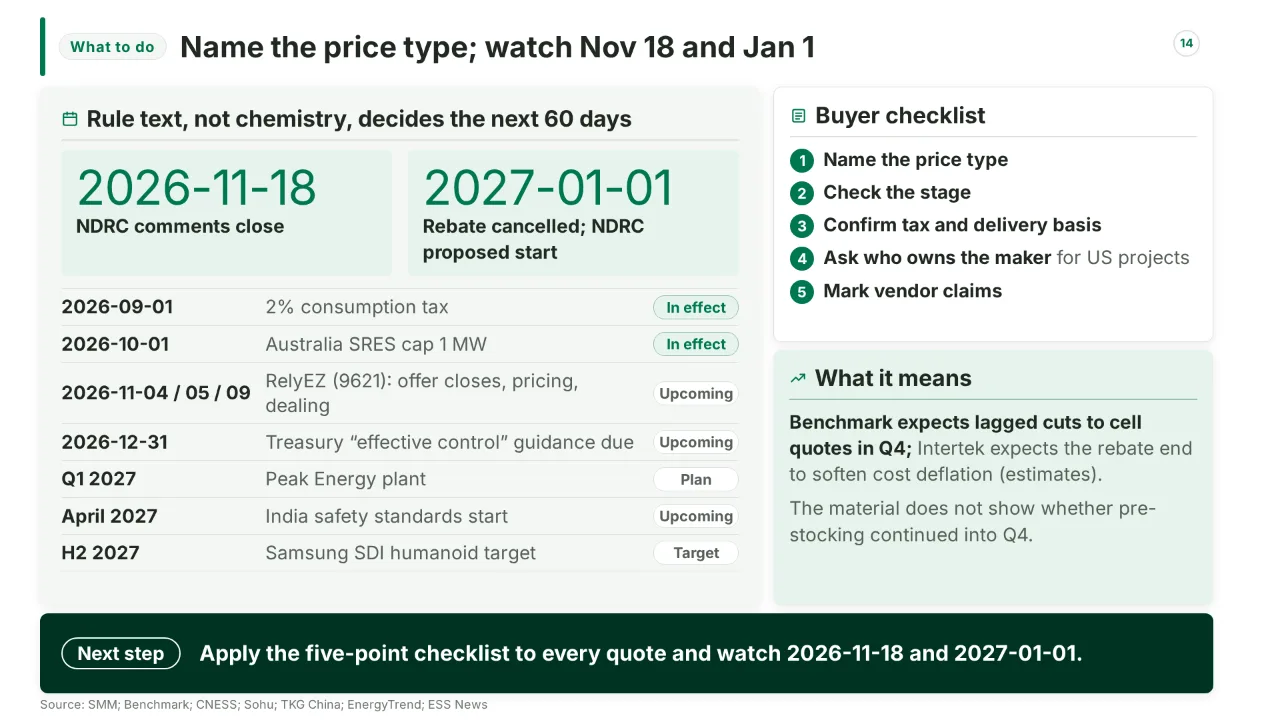
Core claim: The next 60 days will be settled by contract terms and rule text, not by chemistry: how far lithium's fall reaches cell quotes, whether NDRC's draft spot-market rules survive their comment period to 2026-11-18, and what changes when the export VAT rebate ends on 2027-01-01.
9.2 Buyer checklist
- Name the price type. SMM spot, futures settlement, Benchmark assessments and award values answer different questions (Chapter 2).
- Check the stage. An MoU, an RfS or a permit-pending project is not operating capacity.
- Confirm tax and delivery basis. The 2% consumption tax has applied since 1 September 2026, the export rebate is 6% until 2026-12-31, and Benchmark's September CIF North America cell price was about 20% above EXW China.
- For US projects, ask who owns the maker. The prohibited-foreign-entity test turns on ownership and control, not factory location.
- Mark vendor claims. TENER+ container savings and solid-state energy density are vendor claims.
9.3 Key dates
Status is judged against the run date, 3 November 2026.
| Date | Event | State on Nov 3, 2026 | Source |
|---|---|---|---|
| 2026-04-01 | Battery export VAT rebate cut from 9% to 6% | In effect | TKG China |
| 2026-09-01 | 2% consumption tax on lithium-ion batteries | In effect | Benchmark |
| 2026-10-01 | Australia SRES cap raised from 100 kW to 1 MW | In effect | pv magazine Australia |
| 2026-10-19 | NDRC draft spot-market rules released | Draft published | CNESS |
| 2026-10-26 | Lingwu 1 GW / 4 GWh award notice confirmed | Award notice confirmed; contract unsigned | ESS News |
| 2026-10-28 | SECI 4 GW / 16 GWh standalone BESS RfS | RfS issued | SolarQuarter |
| 2026-11-02 | NTPC Mouda 200 MW / 400 MWh EPC tie-up bids due | Closed; outcome not in the material | BHEL via Embassy of India |
| 2026-11-04 | RelyEZ (9621) global offering closes | Upcoming | EnergyTrend |
| 2026-11-05 | RelyEZ pricing expected | Upcoming | EnergyTrend |
| 2026-11-09 | RelyEZ dealing expected | Upcoming | EnergyTrend |
| 2026-11-18 | NDRC draft spot-market rules, comment deadline | Upcoming | CNESS; Sohu |
| 2026-12-31 | Export VAT rebate at 6% ends; Treasury "effective control" guidance due | Upcoming | TKG China; China Prospect |
| End-2026 | China cell-capacity approvals review expected to conclude | Upcoming (reported) | Benchmark |
| End-2026 | Greenvolt Poland sale (1.6 GWh) expected to close | Upcoming | Greenvolt |
| 2027-01-01 | Export VAT rebate cancelled; NDRC draft proposed start | Upcoming | TKG China; Sohu |
| Q1 2027 | Peak Energy 4 GWh sodium-ion plant, production start | Upcoming (plan) | ESS News |
| 2027-04-30 | Lingwu grid-connection notice due | Upcoming | ESS News |
| April 2027 | India energy-storage safety standards start | Upcoming | ESN |
| H1 2027 | Samsung SDI two further SPE LFP lines begin operation | Upcoming (plan) | TradingView/GuruFocus |
| 2027 | CATL all-solid-state small-batch pilot production | Upcoming (plan) | Electric Viking |
| H2 2027 | Samsung SDI all-solid-state humanoid target | Upcoming (target) | TradingView/GuruFocus |
10. References
This document draws on the following 80 sources, listed in the order they are first cited.
- SMM Lithium Carbonate Daily Review On October 28, spot lithium carbonate prices rose by 700 yuan/mt, while futures retreated after a rapid rise, falling on increased volume and open interest. - Shanghai Metals Market (SMM) — news.metal.com
- SMM Analysis Lithium Battery Q3 2026 Profit Divergence - Shanghai Metals Market (SMM) — news.metal.com
- Lithium's BESS hangover: UBS sees no rebound before year end — marketindex.com.au
- Battery Cell Price Review Q3 2026 — source.benchmarkminerals.com
- Consortium wins $535 million tender for 4 GWh storage project in China - Energy Storage — ess-news.com
- TD Research | July 2026 China BESS Tender Awards Review: 26.0 GWh Awarded; 4-Hour EPC/PC Price Reaches RMB 0.54/Wh — linkedin.com
- Industry Express | Cancellation of VAT Export Tax Rebates for Photovoltaic and Other Products - TKG China — tkgelectric.com
- US battery storage prices could fall up to 30% by 2030 - Energy Storage — ess-news.com
- Samsung SDI: 60GWh of ESS battery orders in 2026 so far, 53% year-over-year ‘revenue surge’ — energy-storage.news
- EVE Energy ships 67.52 GWh of storage batteries in first nine months of 2026 - Energy Storage — ess-news.com
- Sungrow Power Supply's Q3 Gross Margin Drops Nearly 9 Percentage Points Quarter-on-Quarter; Multiple Solar and Energy Storage Equipment Manufacturers Have Initiated Price Hikes | Financial Report Analysis — moomoo.com
- BYD (BYDDY) Q3 profit jumps 28% on exports, but inventory balloons 60% | Electrek — electrek.co
- CATL Advances 20 Ah Solid-State Battery Cells, Targets 2027 Small-Batch Production - The Electric Viking — theelectricviking.com
- Samsung SDI Co Ltd (FRA:XSDG) (Q3 2026) Earnings Call Highlights: Return to Profit on ESS Boom ... — TradingView News — tradingview.com
- Sodium-ion storage maker Peak Energy raises $108 million in GM-led round - Energy Storage — ess-news.com
- CATL TENER+ BESS gets global debut while deep interest in TENER Sodium grows - pv magazine Australia — pv-magazine-australia.com
- Intensive Energy Storage Order Updates from 7 Firms Including Narada Power and Envision Energy Storage - EnergyTrend — energytrend.com
- Samsung SDI and Alpha Omega Power Sign 1 GWh Supply Agreement for U.S.-Made Energy Storage — finance.yahoo.com
- Newsroom|LG Energy Solution — lgensol.com
- 3GWh!INTILION与宁德时代签约,钠电储能规模化出海 — catl.com
- India has 5.3GWh of operational BESS, with 185GWh under development, CEA official says — energy-storage.news
- SECI Issues Tender For 4 GW/16 GWh BESS Projects In Rajasthan And Gujarat With VGF - SolarQuarter — solarquarter.com
- 中国储能网 -国家政策 - 一文读懂新版《电力现货市场基本规则(公开征求意见稿)》 } — escn.com.cn
- 深度 | 2027年施行,新版电力现货市场基本规则对长时储能的影响_结算_收益_电价 — sohu.com
- ASX lithium crash: PLS, LTR, MIN face third bear market in a decade — marketindex.com.au
- SMM Lithium Carbonate Daily Review On October 26, spot lithium carbonate stopped falling and rebounded, ending its previous consecutive decline. - Shanghai Metals Market (SMM) — news.metal.com
- SMM Lithium Carbonate Daily Review Lithium Carbonate Futures and Spot Prices Rebound in Tandem on October 27 - Shanghai Metals Market (SMM) — news.metal.com
- Solid-state battery: Tinci Materials' hundred-mt-class sulphide solid-state electrolyte pilot line completed and trial production started, samples begin delivery - Shanghai Metals Market (SMM) — news.metal.com
- Prices hold steady ahead of the National Day; price negotiation to kick off after holiday — infolink-group.com
- Solar cell and module technology: Trends and outlooks-webinar-InfoLink Consulting — infolink-group.com
- ASX lithium crash: PLS, LTR, MIN face third bear market in a decade — TradingView News — tradingview.com
- Tender Ref: MANPBT0042 DT.23.10.2026: Pre bid Tie up/MOU for EPC package for development of 200MW/400MWh BESS at NTPC Mouda - Embassy of India, Tashkent — eoitashkent.gov.in
- ADS-TEC Energy nears final permit for 1 GW / 4 GWh battery project in Germany - Energy Storage — ess-news.com
- China's 2026 Export Tax Rebate Cut: Which Chemicals Changed — qiboch.com
- EVE Energy, Pylontech, and CosMX Report Q3 2026 Energy Storage Results - EnergyTrend — energytrend.com
- China's EVE Energy posts CNY 73.39 billion in first three quarters, power battery shipments up over 90% — BigGo Finance — finance.biggo.com
- BYD Delivers Strong Q3 2026 Profit Growth Amid Flat Year-to-Date Revenue - TipRanks.com — tipranks.com
- EVE Energy Q3 2026 revenue up 64.6% to RMB27.7bn; energy-storage cell shipments reach 67.5 GWh in nine months | SSG Events — ssg.events
- News - EnergyTrend — energytrend.com
- Deye Energy Storage Secures Cixi Phase II Land with 100M Yuan Investment for 9GWh Commercial & Industrial Energy Storage Production Line - EnergyTrend — energytrend.com
- BYD Q3 2026 results: Revenue rises 13.59% to RM 138.4 billion, net profit up 28.08%, overseas sales surge 90.7% | BitAuto Malaysia — bitauto.my
- Great Power, Sinexcel, and Kstar Announce Q3 2026 Financial Results - EnergyTrend — energytrend.com
- Tesla Q3 2026 energy storage revenues fall despite second-highest quarterly deployments — energy-storage.news
- CATL Retains Top AAA Rating in PV Tech’s Battery Storage Bankability Rankings — catl.com
- LG Energy Solution Signs MoU With Energix for Up to 4.5GWh of BESS Supply - Shanghai Metals Market (SMM) — news.metal.com
- Energix & LG Energy Solution sign 4.5 GWh battery storage MoU — solarbytes.info
- energy storage news - EnergyTrend — energytrend.com
- Samsung SDI Signs 1-GWh ESS Deal, Expands Indiana Storage Push — batterytechonline.com
- Sigenergy Plans Joint-Venture Energy Storage Factory in India with an Initial Investment of USD 250 Million - EnergyTrend — energytrend.com
- Battery Storage Tax Credit: Prohibited Foreign Entity Rules | China Prospect — chinaprospect.com
- The Battery Storage Development Handbook: Developing, Financing and ... - Julian R. Sterling - Google Books — books.google.com
- Sunwoda's Solid-State Battery Still in Customer Sample Testing, Putting 2026 Mass-Production Goal in Doubt | XenoSpectrum — xenospectrum.com
- Solid-state battery: Solid Power’s MOBIUS pilot line for continuous production of sulphide electrolyte begins commissioning, capacity to increase by 150% - Shanghai Metals Market (SMM) — news.metal.com
- Solid-state battery: Tianqi Lithium's 50 mt lithium sulfide pilot project expected to be completed in H2, samples already sent to over 30 clients - Shanghai Metals Market (SMM) — news.metal.com
- US-based QuantumScape Plans 100 MWh Solid-State Battery Production Line, Targeting AI Data Centers and Other Markets - EnergyTrend — energytrend.com
- India’s Delectrik Systems awarded 120MWh long-duration vanadium flow battery contract in Gujarat — energy-storage.news
- CATL sets 'industry-leading' solid-state battery production timeline - Notebookcheck News — notebookcheck.net
- CATL plans small-scale solid-state battery output in 2027 | UA.NEWS — ua.news
- CATL confirms 2027 solid-state battery pilot for premium EVs — eastasiabrief.com
- Solid-state battery: Samsung SDI reiterates mass production of 900Wh/L all-solid-state battery in H2 2027, with initial applications targeting luxury vehicles and humanoid robots - Shanghai Metals Market (SMM) — news.metal.com
- Nearly 2.2 GWh: Four Firms Including SVOLT and Samsung SDI Secure Energy Storage Orders - EnergyTrend — energytrend.com
- Bondada Engineering Wins Contract For 20 MW/120 MWh Vanadium Flow Battery Storage Project In Gujarat - SolarQuarter — solarquarter.com
- GLOBAL OFFERING — www1.hkexnews.hk
- RelyEZ Launches Hong Kong IPO, Aiming to Raise up to HK$639 Million - EnergyTrend — energytrend.com
- long-duration storage — CNESA China Update | Energy Storage Market Insights and Monthly Report — en.cnesa.org
- 国家发改委《电力现货市场基本规则》公开征求意见:新能源配储可联合报价,新型储能/虚拟电厂/绿电直连统一入场,场站通信与计量体系迎改造窗口 - 杭州领祺科技有限公司 — linkqi.cn
- 电力现货市场基本规则征求意见:2027年施行后光伏电站收益怎么算-安徽锦天新能源科技有限公司 — jintianne.com
- 电力现货市场新规拟支持新能源配储联合参与报价 _ 东方财富网 — stock.eastmoney.com
- ADS-TEC Energy Advances One of Europe’s Largest Battery Storage Projects as Building Permit Nears — finance.yahoo.com
- TNERC Approves 600 MW Solar Power With 1,800 MWh Storage At INR 3.12 per Unit In Tamil Nadu - SolarQuarter — solarquarter.com
- Greenvolt Power agrees to sell 400 MW/1.6 GWh Bess Projects to A&R Investments - Power — power.greenvolt.com
- ACME Solar Commissions Additional 35.77 MW/143.08 MWh BESS Capacity In Rajasthan - SolarQuarter — solarquarter.com
- Recurrent Energy Completes Sale of Two 100 MW / 400 MWh BESS Projects in France to BW ESS — prnewswire.com
- Scatec Secures $217 Million Financing For 569 MW Solar And 100 MWh BESS Project In Egypt - SolarQuarter — solarquarter.com
- India’s BESS pipeline needs bankable tenders and diversified revenue streams — energy-storage.news
- Germany moves forward with plans for one of Europe's largest battery storage projects — review-energy.com
- ADS-TEC Energy expects permit shortly for ~1 GW plant | ADSE SEC Filing - Form 6-K — stocktitan.net
- Batteries are big at All Energy Australia 2026 - pv magazine Australia — pv-magazine-australia.com
- Sigenergy unveils 401 kWh all-in-one battery for C&I sites - pv magazine Australia — pv-magazine-australia.com
- BESS already reducing curtailment in Chile, says ACERA; in-construction projects to triple capacity — energy-storage.news